
LENZ Therapeutics After VIZZ: Single-Product Leverage, Early Commercialization Frictions, and the Test of Presbyopia Adoption
With only one product—VIZZ—on the market and no pipeline, LENZ Therapeutics’ future depends on the speed and breadth of presbyopia treatment adoption, execution in commercial distribution, and its ability to convert liquidity into lasting market share before competitors or operational setbacks erode its opportunity.
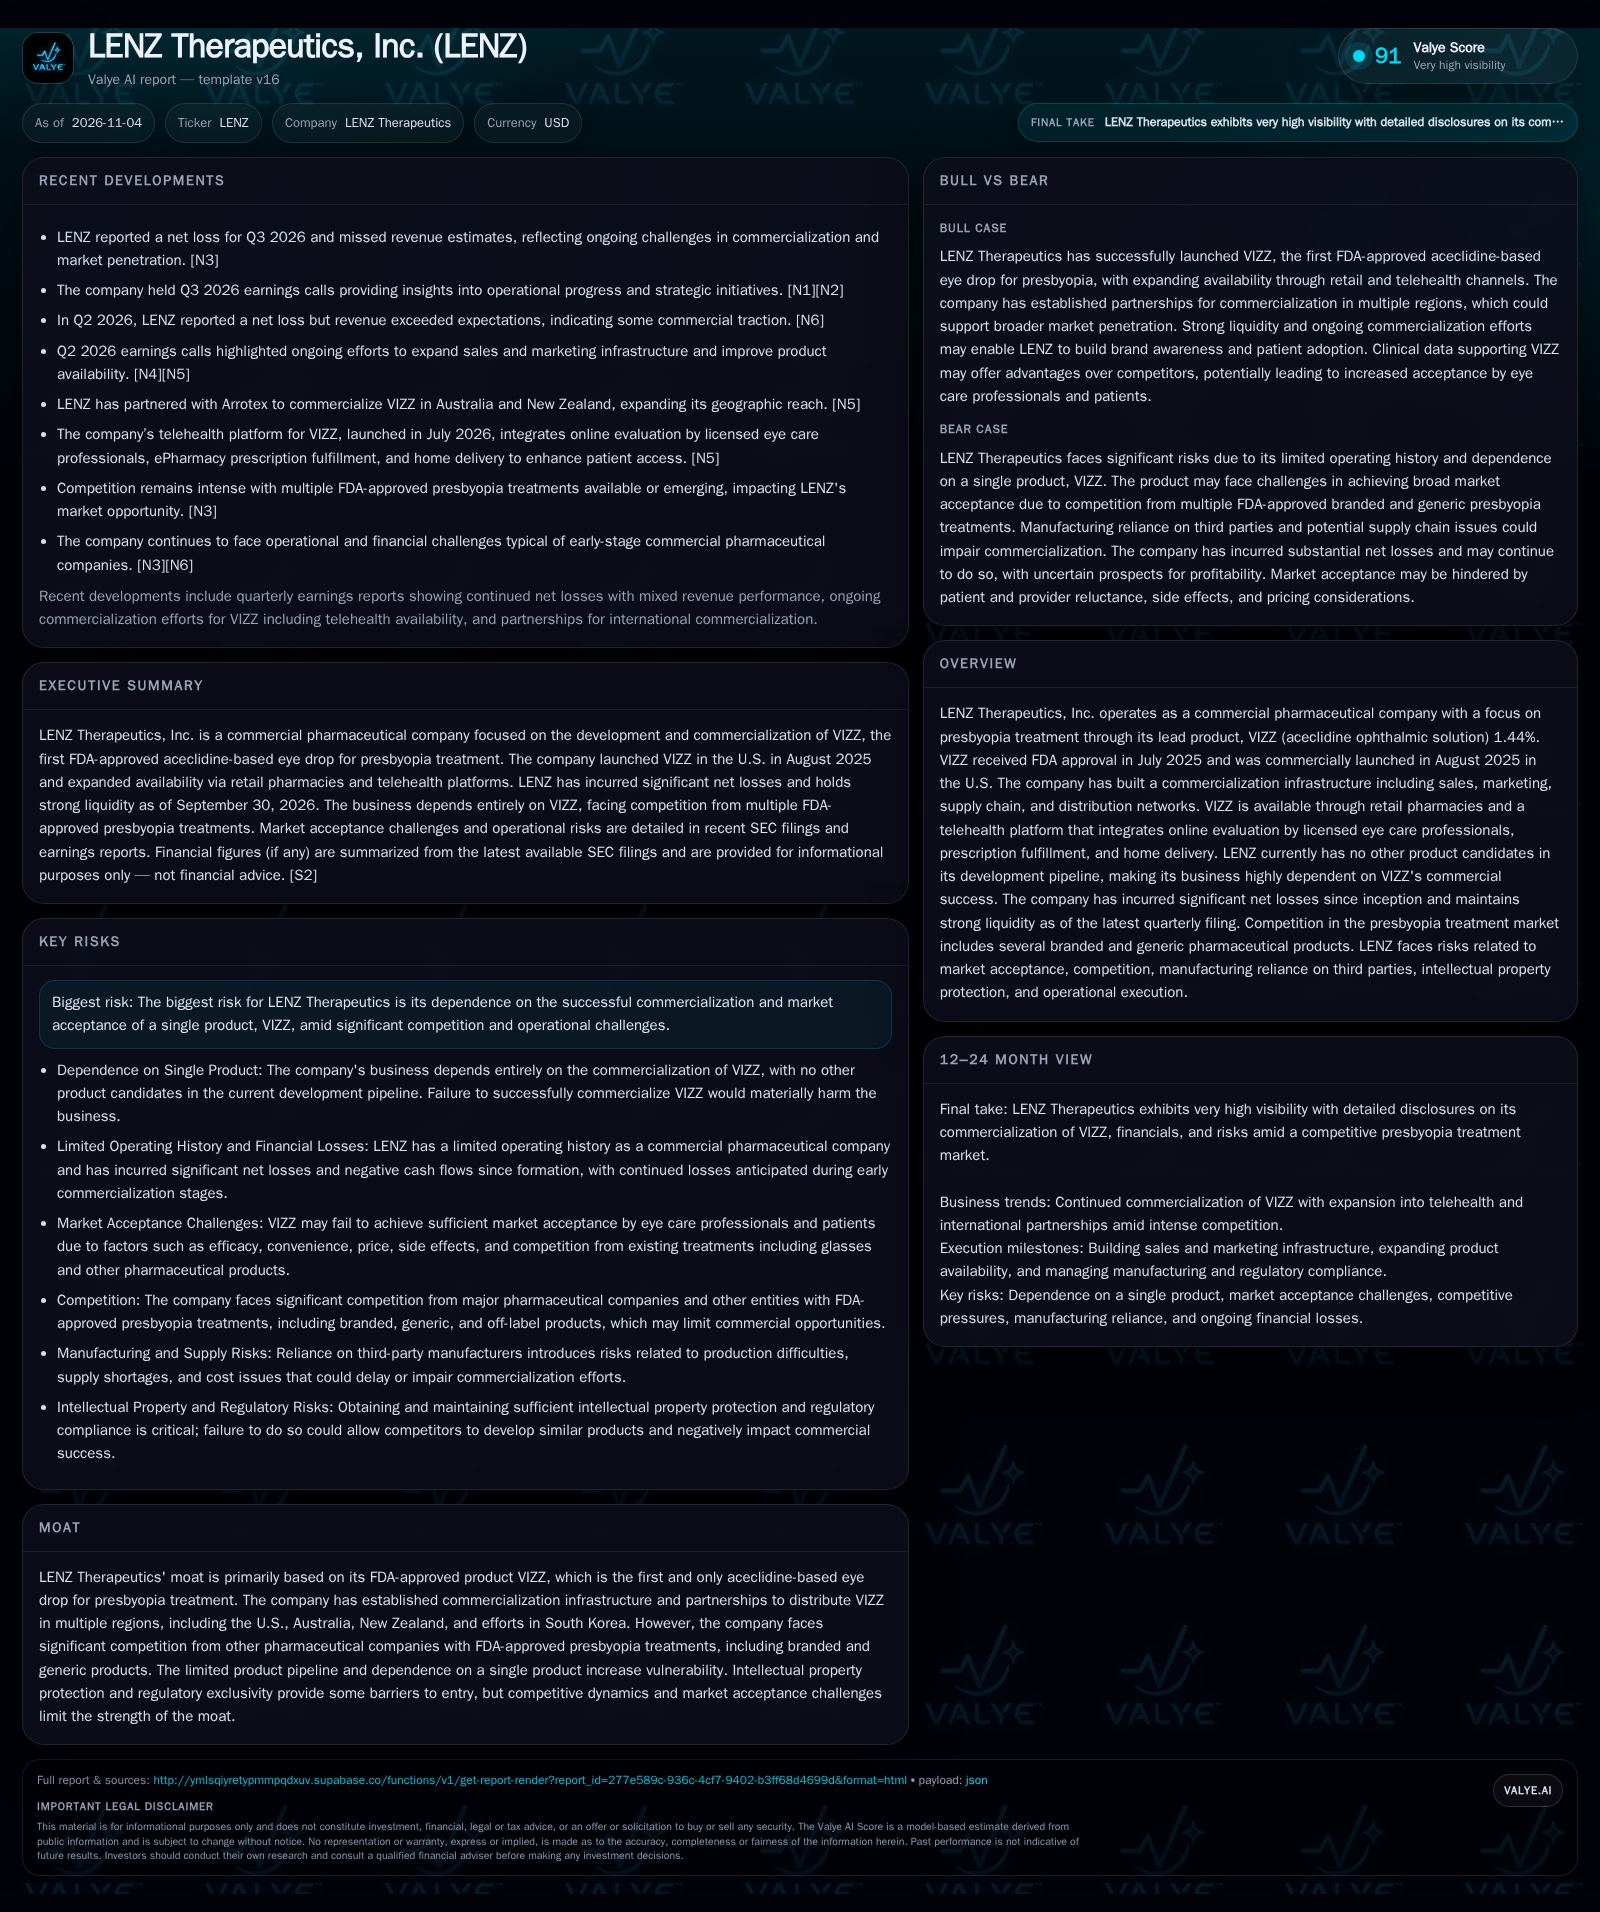
LENZ Therapeutics is an early-stage commercial pharma company built entirely around VIZZ, its FDA-approved presbyopia eye drop. Execution in sales, telehealth expansion, and international partnerships are critical levers, but with no pipeline, the margin for error is thin. [S2] [N3] [N6]
LENZ Therapeutics offers a pure-play bet on pharmaceutical presbyopia treatment, but its fate is tightly bound to the commercial performance of VIZZ, its only product. Despite securing FDA approval and rolling out to both brick-and-mortar pharmacies and a telehealth platform, LENZ remains in the early innings of market development. With substantial net losses and no diversification in its pipeline, the company must rapidly convert liquidity and infrastructure investments into sustainable adoption—before competitive, operational, or market acceptance headwinds close its window of opportunity. [S2] [N3] [N6]
Current Commercialization Status and Financial Position: The Stakes for VIZZ
LENZ Therapeutics’ entire business now revolves around VIZZ, an aceclidine ophthalmic solution for presbyopia, which received FDA approval in July 2025 and launched commercially in the U.S. in August 2025. By November 2025, VIZZ was broadly available at retail pharmacies, and in July 2026, LENZ expanded access via a telehealth platform that integrates evaluation, prescription fulfillment, and home delivery. However, the company has no other products in development, making VIZZ’s success existential. Financially, as of September 30, 2026, LENZ reported $30.55 million in cash, current assets of $206.9 million, current liabilities of $17.75 million, and a net loss of $31 million for Q3 2026, with an accumulated deficit of $331.5 million. [S2] [N3] [N6]
Given LENZ’s reliance on a single product, the company’s financial position must be viewed through the lens of runway and capital efficiency. The reported cash and current assets provide a snapshot, but a more telling metric would be the burn rate relative to the pace of revenue growth. If VIZZ’s commercialization accelerates, the incremental gross margin contribution could extend operational runway, deferring the need for external financing. Conversely, any delays or setbacks in market uptake would pressure liquidity, potentially forcing LENZ to prioritize cash conservation over marketing spend or telehealth expansion. The absence of a diversified portfolio increases the sensitivity of financial outcomes to the success or failure of VIZZ’s early commercial execution.
How LENZ Could Monetize VIZZ: Pricing, Volume, and the Single-Product Challenge
LENZ’s economics are dominated by the commercial trajectory of VIZZ. The company’s model likely relies on a mix of traditional pharmaceutical pricing (via retail pharmacy channels) and direct-to-consumer telehealth-enabled sales, each with different margin profiles and customer acquisition costs. The ability to secure reimbursement, price competitively with established alternatives (including branded and generic eye drops, as well as non-pharmaceutical options like reading glasses), and scale volume will determine gross margin leverage. Fixed costs are substantial at this stage, given the investment in commercialization infrastructure and sales force, but variable costs per prescription may decrease as volumes rise if manufacturing and distribution are efficiently managed. With no pipeline, LENZ cannot diversify revenue or leverage shared R&D, so break-even depends entirely on the adoption curve and pricing power of VIZZ. If the company fails to achieve sufficient market penetration before liquidity runs low, dilution or strategic alternatives may become necessary. [S2]
The dual-channel approach—retail pharmacy and telehealth—introduces complexity in unit economics that LENZ must carefully manage. Telehealth channels may offer lower customer acquisition costs and enhanced convenience, but could also face challenges in patient retention and adherence, which directly impact lifetime value per customer. Retail pharmacy sales, while potentially higher margin due to established reimbursement pathways, may require more substantial promotional investments to drive prescriber and patient awareness. The interplay between these channels will influence the overall cost structure and margin profile. If LENZ can optimize channel mix and improve prescription refill rates, it could achieve economies of scale that substantially improve profitability despite the high fixed costs inherent in pharmaceutical commercialization.
Market Dynamics: Competing for Presbyopia Patients and Professional Mindshare
LENZ faces a crowded and rapidly evolving presbyopia treatment landscape. VIZZ must compete with both branded and generic pharmaceutical products, as well as off-label therapies and the entrenched use of reading glasses. The pharmaceutical competitors may include established ophthalmology companies with deeper commercial resources, broader portfolios, and existing relationships with eye care professionals (ECPs). Non-pharmaceutical substitutes—especially glasses—are low-cost, widely accepted, and require no prescription, making the adoption of VIZZ a behavioral as much as a clinical challenge.
LENZ’s early-mover advantage in telehealth may help differentiate its offering and reduce friction for patients, but this channel’s economics and retention rates remain unproven. Intellectual property and regulatory exclusivity provide some temporary barriers, but the absence of a pipeline and reliance on third-party manufacturing limit moat durability. Partnerships for international expansion (e.g., Arrotex in Australia/New Zealand, Lotus Pharma in South Korea) offer access to new markets but also add regulatory and execution risk. The company’s ability to build and sustain share will depend on demonstrating superior efficacy, convenience, and cost-effectiveness, while overcoming physician and patient inertia.
The competitive environment for presbyopia treatments is multifaceted, involving not only pharmaceutical alternatives but also entrenched behavioral and clinical practices. LENZ’s ability to influence prescriber behavior is critical, as eye care professionals serve as gatekeepers for patient adoption. This requires compelling clinical differentiation, clear communication of benefits over existing therapies, and addressing concerns about side effects or convenience. The telehealth model may lower access barriers but also requires building trust and familiarity with a new care delivery format. Additionally, competitive responses—such as price adjustments, marketing campaigns, or new product launches—could rapidly alter market dynamics, underscoring the importance of LENZ’s agility and execution precision in maintaining a competitive edge.
What If VIZZ Becomes the Standard: The Path to Profitable Adoption
A favorable outcome for LENZ would require rapid and broad adoption of VIZZ by both patients and eye care professionals, driven by compelling efficacy, tolerability, and a differentiated access model (especially via telehealth). If LENZ can leverage its sales force, partnerships, and pharmacy/telehealth channels to accelerate prescription volume, fixed-cost leverage could drive the company toward profitability before competitive or operational setbacks arise. International partnerships could add incremental revenue streams, especially if regulatory approval is secured in Australia, New Zealand, and South Korea.
Confirmation of this scenario would come from accelerating prescription growth, improved gross margins, and evidence that ECPs are adopting VIZZ as a frontline therapy. Sustained positive revenue surprises, narrowing net losses, and successful expansion into new geographies would further validate this path. Pipeline expansion or lifecycle management (e.g., new indications, formulations) would also bolster the upside case.
Commercial Progress, but Margin for Error Remains Razor-Thin
The most plausible near-term scenario is that LENZ achieves moderate commercial traction: VIZZ sees gradual uptake among early adopters, but broader market penetration is constrained by competition (both pharmaceutical and non-pharmaceutical), pricing dynamics, and inertia among ECPs and patients. Telehealth expansion may improve access but may not fully offset the challenges of building prescriber confidence or overcoming entrenched alternatives like glasses.
Evidence of this scenario would include fluctuating quarterly revenue, persistent net losses, and only incremental improvements in market share.
If Adoption Stalls: The Risks of Single-Product Dependency and Market Inertia
In the downside scenario, VIZZ fails to achieve meaningful market acceptance, either due to underwhelming efficacy, side effect concerns, perceived inconvenience, or price sensitivity relative to alternatives. If eye care professionals remain skeptical or slow to adopt, and patients default to established solutions like glasses, prescription growth could stagnate. Manufacturing or supply chain setbacks could exacerbate these problems, while competitive launches or generic entry could erode any early-mover advantage.
Prolonged net losses would erode LENZ’s liquidity, eventually forcing the company to seek dilutive financing or strategic alternatives (such as out-licensing, asset sales, or acquisition). Signs of this scenario would include declining or flat prescription volumes, negative revenue surprises, widening losses, or public acknowledgment of operational or financial distress.
Milestones That Will Determine Whether LENZ Can Build a Sustainable Franchise
Quarterly VIZZ prescription volume and growth rate—if disclosed—are critical for gauging market traction and adoption curves.
Gross margin trends, particularly as telehealth and pharmacy channel mix evolves, would help test the scalability and profitability of the business.
Updates on payer coverage and out-of-pocket costs for patients, as insurance access could materially affect volume and price sensitivity.
Survey or reported data on eye care professional adoption and repeat prescribing behavior, which would indicate acceptance among key influencers.
Progress in international regulatory approvals and commercial launches (e.g., in Australia, New Zealand, South Korea), as these represent incremental revenue opportunities.
Any new product development, pipeline expansion, or lifecycle management initiatives that would reduce single-product risk.
Disclosure of manufacturing or supply chain disruptions, which could impact availability and reputation.
Evidence of competitor launches, generic entry, or off-label usage trends that could shift the competitive landscape.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments