
Life360’s Platform Expansion: Subscription Growth, Hardware Integration, and the Realities of Digital Safety Economics
Life360, Inc. is scaling its family safety platform by deepening its subscription base, integrating hardware tracking devices, and leveraging strategic partnerships. While recent financial results highlight robust revenue momentum, the company must navigate evolving cybersecurity threats, operational risks from AI integrations, and a fiercely competitive landscape where user retention and product innovation are paramount.
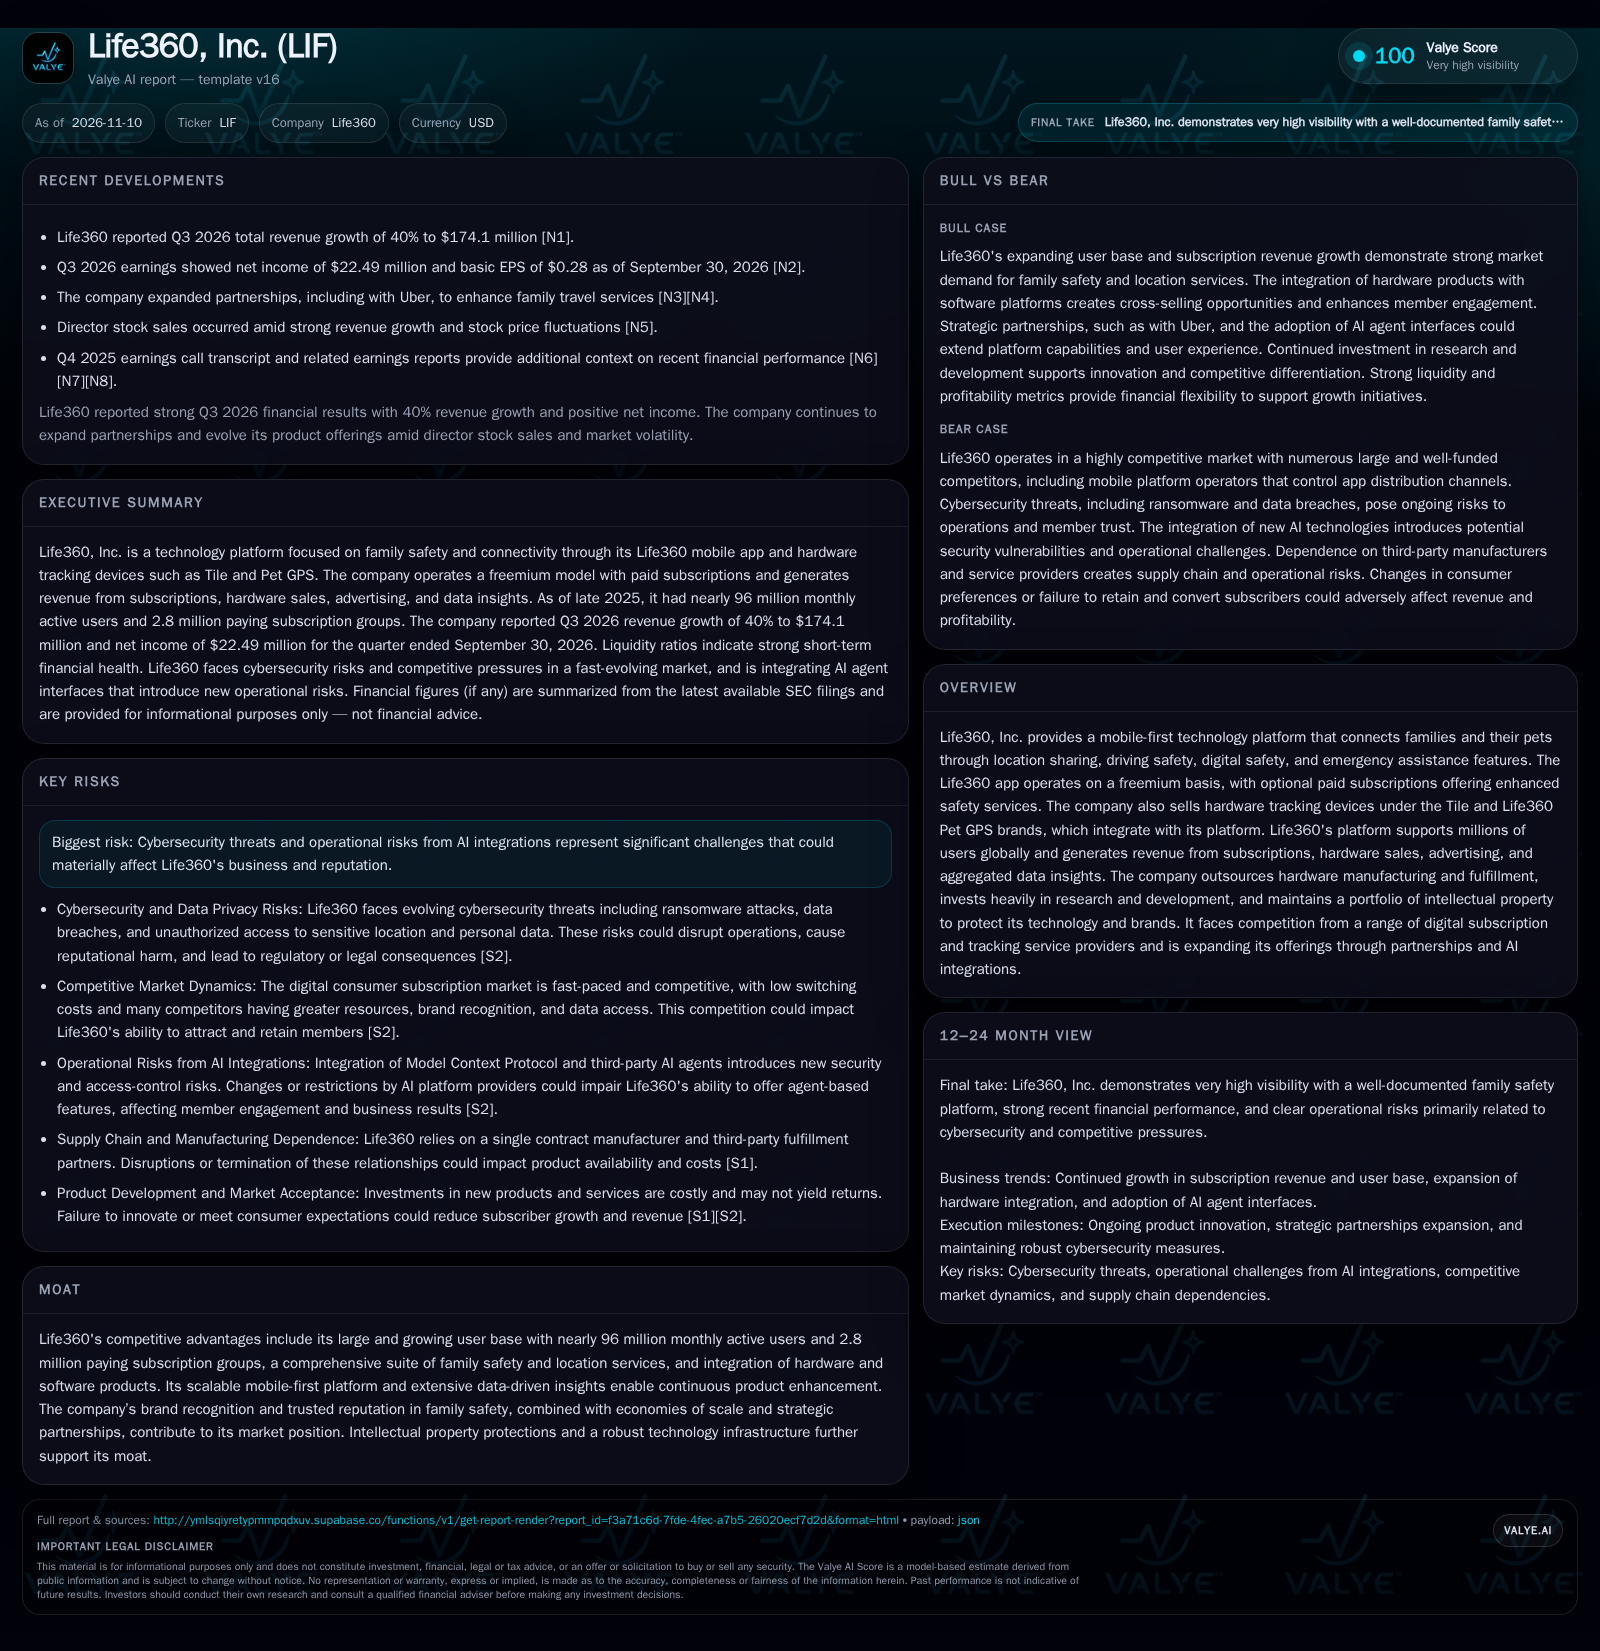
Life360’s Q3 2026 revenue surged 40%, powered by nearly 96 million monthly active users and 2.8 million paying Circles. The company’s hybrid model blends software subscriptions with hardware devices, aiming to increase user engagement and cross-selling. Key risks include cybersecurity, competitive pressure, and the operational complexity of integrating third-party AI agents.
Life360, Inc. is evolving from a family location-sharing app to a broader digital safety platform, combining software subscriptions, connected hardware, and data-driven services. The company’s recent 40% revenue growth and expanding user base suggest traction in a growing market for family, pet, and asset safety. However, as Life360 integrates AI agent interfaces and forges new partnerships, it confronts increased operational complexity, cybersecurity exposure, and the challenge of sustaining engagement amid intense competition. The next phase will test its ability to convert scale into durable economics while protecting user trust and platform integrity.
Recent Revenue Surge and Platform Scale: What’s Changed for Life360 in 2026
Life360 reported Q3 2026 revenue of $174.1 million, a 40% year-over-year increase, alongside net income of $22.49 million and diluted EPS of $0.26 [N1] [S2]. This growth coincides with the company reaching approximately 95.8 million monthly active users and 2.8 million paying Circles (subscription groups) as of December 2025, reflecting expansion in both free and paid user segments [S1]. The business model now blends core app subscriptions with hardware sales (Tile, Pet GPS), advertising, and data monetization, positioning Life360 as a hybrid digital safety platform. As of September 2026, Life360 reported $333.1 million in cash and a current ratio of 5.31 [S2]. Strategic partnerships, notably with Uber, and ongoing R&D investments are cited as key drivers of product and revenue growth [N3] [N4] [S1]. These developments collectively signal a phase of operational scale and financial momentum, but also introduce new operational and strategic complexities.
How Life360 Monetizes Safety: Subscription Stickiness, Hardware Mix, and Platform Leverage
Life360’s economics are anchored in a freemium-to-premium model: the free app drives user acquisition and engagement, while paid Circles convert a portion of the base to recurring subscription revenue [S1]. Premium tiers offer enhanced safety features, driving higher ARPU, but the company must continually innovate to justify upgrades and reduce churn. Hardware sales (Tile Bluetooth trackers, Pet GPS devices) provide incremental revenue and cross-sell opportunities, potentially increasing platform stickiness if device owners are more likely to remain engaged. However, hardware margins are often lower than software, and the company outsources manufacturing to Jabil, which may limit gross margin expansion but reduces capital intensity [S1].
Advertising and aggregated (non-PII) data sales offer supplementary, likely lower-margin revenue streams that leverage the platform’s large user base. The integration of third-party AI agents and partnerships (e.g., Uber) could unlock new monetization avenues—such as contextual services or higher-value subscription bundles—but also raise costs and operational complexity. R&D spending, $128.4 million in 2025, suggests high fixed costs and a need for scale to drive operating leverage [S1]. The model could produce attractive profitability as the subscriber base grows, but margin dilution is possible if hardware or lower-margin services outpace subscription growth.
Defending the Family Safety Niche: Where Life360 Stands Among Digital Consumer Platforms
Life360 operates in a crowded digital subscription market, competing with both large platform operators (who control app distribution and own integrated location services) and specialized tracking/device startups [S2]. Its advantages include a large, engaged user base, a suite of safety-focused features, and the integration of hardware and software, which may increase switching friction for families invested in both the app and devices. Brand trust and a reputation for family safety are differentiators in a segment where privacy and reliability matter. However, low switching costs and the threat of platform operators bundling similar features directly into mobile OS ecosystems are persistent counterforces.
The addition of AI agent interfaces and partnerships may expand Life360’s relevance, but also exposes the company to rapid feature commoditization if competitors replicate core functionality or undercut on price. The hardware component could be a source of lock-in, but only if device integration is seamless and value-added. Life360’s competitive moat will depend on its ability to deepen user engagement, maintain data-driven feature leadership, and avoid disintermediation by larger tech ecosystems.
Platform Flywheel: Subscription Expansion and Ecosystem Effects Drive Durable Growth
In a favorable scenario, Life360 leverages its growing user base and cross-device integration to accelerate paying Circle conversion and ARPU expansion. Strategic partnerships (e.g., with Uber) and third-party AI agent integrations enhance the platform’s utility, creating new revenue streams and reinforcing engagement. If hardware adoption increases retention—because families and pet owners are more deeply embedded in the ecosystem—churn could fall and customer lifetime value would rise.
A positive feedback loop emerges: more users attract more partners and service integrations, which drive further differentiation and premium conversion. Evidence confirming this scenario would include sustained double-digit subscription growth, rising ARPU, hardware attachment rates trending upward, and successful launches of bundled or AI-enhanced premium offerings. Reduced churn and growing cross-platform engagement would further validate the flywheel.
Sustaining Growth: Balancing Innovation, Retention, and Margin Pressures
The most plausible trajectory is continued, but moderating, user and revenue growth as the market for family safety and connected tracking becomes more saturated. Subscription expansion may slow as penetration increases, but overall revenue could still rise through ARPU optimization, incremental hardware adoption, and new feature launches. Operating leverage improves as fixed R&D and platform costs are spread over a larger base, but margin gains are tempered if hardware or lower-margin services grow faster than subscriptions.
Competition intensifies, requiring sustained product innovation and marketing investment to maintain share. AI agent integrations and partnerships provide incremental value, but introduce new operational and cybersecurity risks, which may periodically disrupt growth or require additional investment. Confirming evidence for this scenario would be steady growth in paying Circles, stable or slightly rising ARPU, and manageable churn, with gross margins remaining flat or improving modestly.
Erosion of Trust and Value: When Cybersecurity, Competition, or Platform Fatigue Bite
The adverse scenario centers on a major cybersecurity incident or data breach that undermines user trust and prompts regulatory or reputational fallout. Integration of third-party AI agents, while offering upside, could create new attack surfaces or operational failures, compounding risk. If competitors—especially platform operators—bundle similar safety features at low or no cost, Life360 could face elevated churn, declining subscription growth, and pricing pressure.
Hardware supply chain disruptions, dependence on a single manufacturer, or failure to innovate could further erode differentiation. Evidence for this scenario would include a spike in churn, declining paying Circle count, margin compression, or a publicized security failure. Regulatory scrutiny or negative press around privacy could further accelerate subscriber losses and depress cross-selling opportunities.
What Will Prove Life360’s Platform Durability and Growth Thesis?
ARPU and hardware attachment rates: Rising average revenue per user and higher device adoption would indicate successful upselling and cross-platform engagement.
Churn and retention: If disclosed, stable or improving churn rates would signal durable user engagement and effective product differentiation.
Gross margin trends: Tracking the mix of subscription versus hardware revenue and overall gross margin would help test the scalability of the business model.
R&D spend as a percentage of revenue: Monitoring whether innovation investment is driving feature leadership and not eroding profitability.
Incidents of cybersecurity breaches or operational disruptions: Any publicized event could materially alter trust and growth trajectories.
Effectiveness and uptake of AI agent-enabled features: Evidence of user adoption and partner integrations would validate the value of recent technology bets.
Competitive responses and pricing dynamics: Shifts in competitor offerings, especially by platform operators, would help gauge future margin and retention pressures.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments