
Medinotec Inc.: Proprietary Device Expansion Confronts Geographic Reliance and Trade Risk
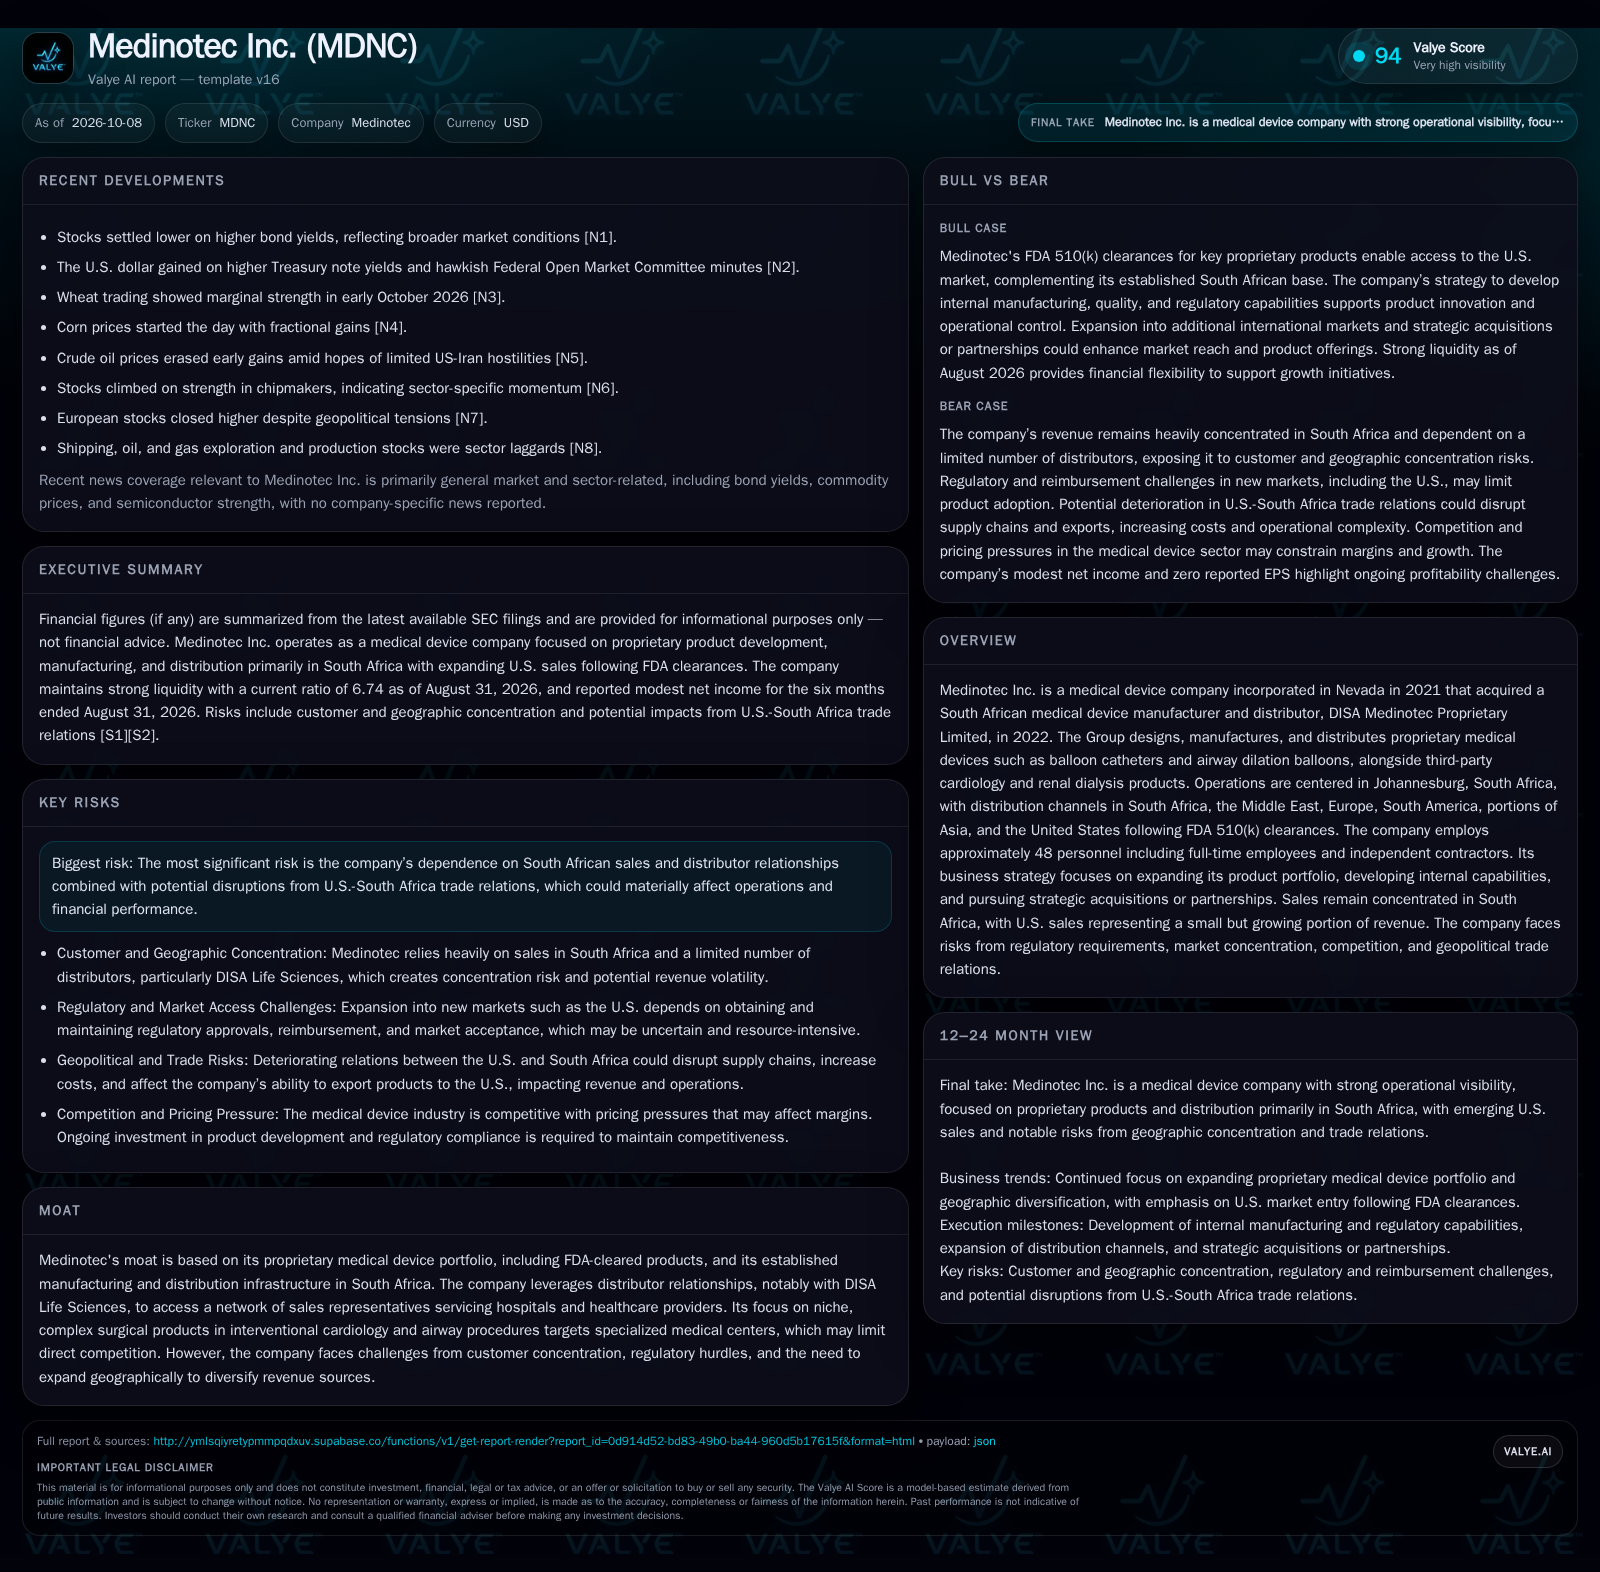
Medinotec leverages a focused portfolio of proprietary interventional devices and a strong South African base to pursue international growth, but faces acute risks from market concentration, regulatory hurdles, and the potential for U.S.-South Africa trade disruption.
Medinotec designs and manufactures proprietary medical devices, with operations and most sales concentrated in South Africa. Recent FDA clearances enable entry into the U.S. market, but U.S. sales remain a small share of revenue.
Medinotec Inc. exemplifies the strategic tension facing emerging medical device firms: a robust proprietary product suite and regulatory achievements enable international ambitions, but core revenues remain tethered to a concentrated South African base and a limited set of distribution partners. With recent FDA clearances opening the door to the U.S. market, early evidence suggests traction is modest and contingent on complex supply chains and geopolitical factors.
Recent Financials, U.S. Market Entry, and Geographic Exposure
Medinotec reported $3.2 million in revenue and $40,866 in net income for the six months ended August 31, 2026, with a current ratio of 6.74, indicating a reported liquidity position [S2]. U.S. sales, enabled by FDA 510(k) clearances for proprietary products like Trachealator (2021) and Outflo (2025), accounted for only 6% of total sales for fiscal 2026, down slightly from the prior year [S2]. The company’s operations, manufacturing, and distribution remain centered in South Africa, with exports to the U.S. dependent on stable trade relations [S1] [S2]. These facts underscore both the company’s financial stability and its vulnerability to geographic concentration and external shocks.
Geographic concentration not only influences revenue stability but also complicates supply chain resilience. Medinotec’s reliance on South African manufacturing and export logistics means that any regional disruptions—whether political, infrastructural, or regulatory—could cascade into delays or increased costs internationally. This dependence underscores the importance of diversified manufacturing footprints or alternate distribution hubs to mitigate single-region risks. Furthermore, currency volatility between the South African rand and major trading partners’ currencies can affect pricing competitiveness and reported financials, adding another layer of complexity to international expansion strategies.
Proprietary Devices, Distribution Leverage, and Structural Margin Potential
Medinotec’s revenue model is built on a mix of internally designed, manufactured, and distributed proprietary medical devices—primarily balloon catheters for interventional cardiology and airway management—and the distribution of third-party medical products under exclusive or non-exclusive agreements [S1]. Proprietary products generally offer higher gross margins than distributed third-party goods, especially when protected by regulatory clearances and technical complexity. However, the company’s scale is modest, with only 48 employees and a reliance on South African manufacturing and logistics [S1]. This structure provides some variable cost flexibility but also limits operating leverage until volumes scale, particularly in higher-value international markets.
The capital requirements for regulatory clearances, quality systems, and manufacturing expansion are non-trivial and may necessitate additional funding as the company seeks to grow its proprietary portfolio and geographic reach [S1]. Pricing power is potentially enhanced in niche and complex surgical applications, but Medinotec remains exposed to reimbursement trends, competitive bidding, and hospital procurement cycles. U.S. expansion—while promising—carries substantial fixed costs related to regulatory compliance, distribution setup, and clinical marketing, which may outpace near-term revenue contributions until a critical mass of adoption is achieved.
The interplay between proprietary product development and distribution agreements creates a nuanced margin profile. While proprietary devices command higher margins due to intellectual property and regulatory barriers to entry, the incremental costs of compliance, ongoing clinical validation, and post-market surveillance can erode net profitability if volumes remain low. Conversely, third-party distribution offers steadier but thinner margins, potentially stabilizing cash flow but limiting scalability. Achieving a favorable balance depends on scaling proprietary device sales to offset fixed costs and leveraging distribution networks to expand market reach without proportionally increasing overhead.
Niche Focus Versus Sector Heavyweights: Competitive Threats and Defensible Segments
Medinotec’s moat is grounded in its proprietary, FDA-cleared devices tailored for complex interventional procedures and its established South African manufacturing and distribution base [S1]. Its focus on niche markets—such as tracheal and aortic valve dilation—can limit direct competition from global device giants, at least in the short term. However, the medical device sector is crowded, with multinational incumbents able to leverage broader portfolios, deeper channels, and aggressive pricing, especially in the U.S. and Europe.
The company’s distribution-dependent model, particularly reliance on DISA Life Sciences in South Africa, creates both reach and risk. Should a key distributor underperform or switch allegiance, sales could be severely impacted. Substitutes include both established branded devices and lower-cost generics, with hospital purchasing committees often prioritizing cost and regulatory status. Medinotec’s ability to defend premium pricing will depend on continued innovation, clinical differentiation, and the ability to navigate complex reimbursement and procurement landscapes abroad.
Medinotec’s niche focus may yield defensibility through specialized applications, but it also narrows the addressable market, necessitating precise targeting and education efforts for clinicians and procurement entities. Larger competitors can undercut pricing or bundle offerings, pressuring Medinotec’s margins and market share. The company’s ability to sustain premium pricing hinges on demonstrating superior clinical outcomes or operational efficiencies that justify higher costs. Additionally, regulatory pathways and reimbursement environments differ substantially across regions, requiring tailored strategies that balance investment in market entry against realistic adoption timelines and competitive responses.
Unlocking International Growth: What Would Prove Sustainable Expansion?
The most favorable scenario for Medinotec involves accelerated adoption of its proprietary devices in the U.S. and other international markets, enabled by successful FDA and other regulatory clearances. If the company can demonstrate clinical superiority or cost-effectiveness, secure additional distribution partnerships, and maintain supply chain reliability even amid geopolitical tensions, revenue diversification and margin expansion could follow. Confirmation would come from a rising share of revenue from outside South Africa—especially sustained double-digit U.S. sales growth—and evidence of recurring orders from major hospital systems or distributor networks.
Additional upside could be driven by successful execution of strategic acquisitions or partnerships, expanding the proprietary portfolio into adjacent interventional categories, and leveraging internal manufacturing for scale efficiencies. Evidence that would falsify this scenario includes persistent stagnation of non-South African sales, margin compression from pricing pressure, or regulatory setbacks in new markets.
Incremental Progress Amid Concentration Risk and Operational Constraints
A more probable trajectory is that Medinotec’s core South African business remains stable, with only gradual growth in international markets as regulatory, distribution, and clinical adoption hurdles slow expansion. U.S. sales may increase modestly but remain below a level that would materially alter the company’s geographic risk profile over the next 12–24 months. Margins could improve slightly if proprietary product mix increases, but operating leverage is likely to be constrained by the need to invest in regulatory, quality, and commercial infrastructure.
This scenario would be confirmed by continued dependence on South African sales and distributor relationships, modest but positive net income, and limited movement in U.S. or other international revenue share. Signs that would falsify this case include a sharp drop in South African sales or a step-function increase in U.S./international revenue, suggesting either disruption or breakthrough, respectively.
Trade Disruption and Distribution Shakeup: How Geographic and Customer Reliance Could Backfire
The most acute risks to Medinotec stem from its heavy reliance on South African operations and key distributor relationships. A deterioration in U.S.-South Africa trade relations could disrupt exports, raise costs, or introduce regulatory barriers, materially impacting U.S. sales and overall profitability [S2]. Simultaneously, the loss or underperformance of a major distributor—such as DISA Life Sciences—could drive a rapid revenue contraction in the company’s core market.
Downside confirmation would include a sudden decline in export sales, sharp increases in logistics or compliance costs, or the reporting of major customer or distributor losses. Margin compression from competitive pricing in South Africa or abroad would further stress the business, potentially necessitating cost cuts, new funding, or a retrenchment of international ambitions.
Milestones That Will Define Medinotec’s Transition to a Diversified Device Company
Track the percentage of total revenue generated outside South Africa—especially in the U.S.—as a measure of successful geographic diversification.
Monitor changes in the customer concentration profile, particularly the share of revenue contributed by DISA Life Sciences and other key distributors (if disclosed).
Watch for new or expanded distribution agreements in the U.S., Europe, or Asia, as evidence of commercial traction and broader market access.
Evaluate gross margin trends, which could signal a shift toward higher-margin proprietary product sales or, conversely, increased pricing pressure.
Observe regulatory milestones—additional FDA clearances, CE marks, or approvals in new geographies—as leading indicators for pipeline expansion.
Assess any announced strategic acquisitions or partnerships that could bolster the proprietary portfolio or accelerate market entry.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments