
SEGG: Diversified Digital Sports Media Ambitions Confront Structural Liquidity and Platform Dependence
Sports Entertainment Gaming Global Corp (SEGG) has rapidly expanded its digital sports and entertainment portfolio via acquisitions and rebranding, targeting engagement across sports, gaming, and event media.
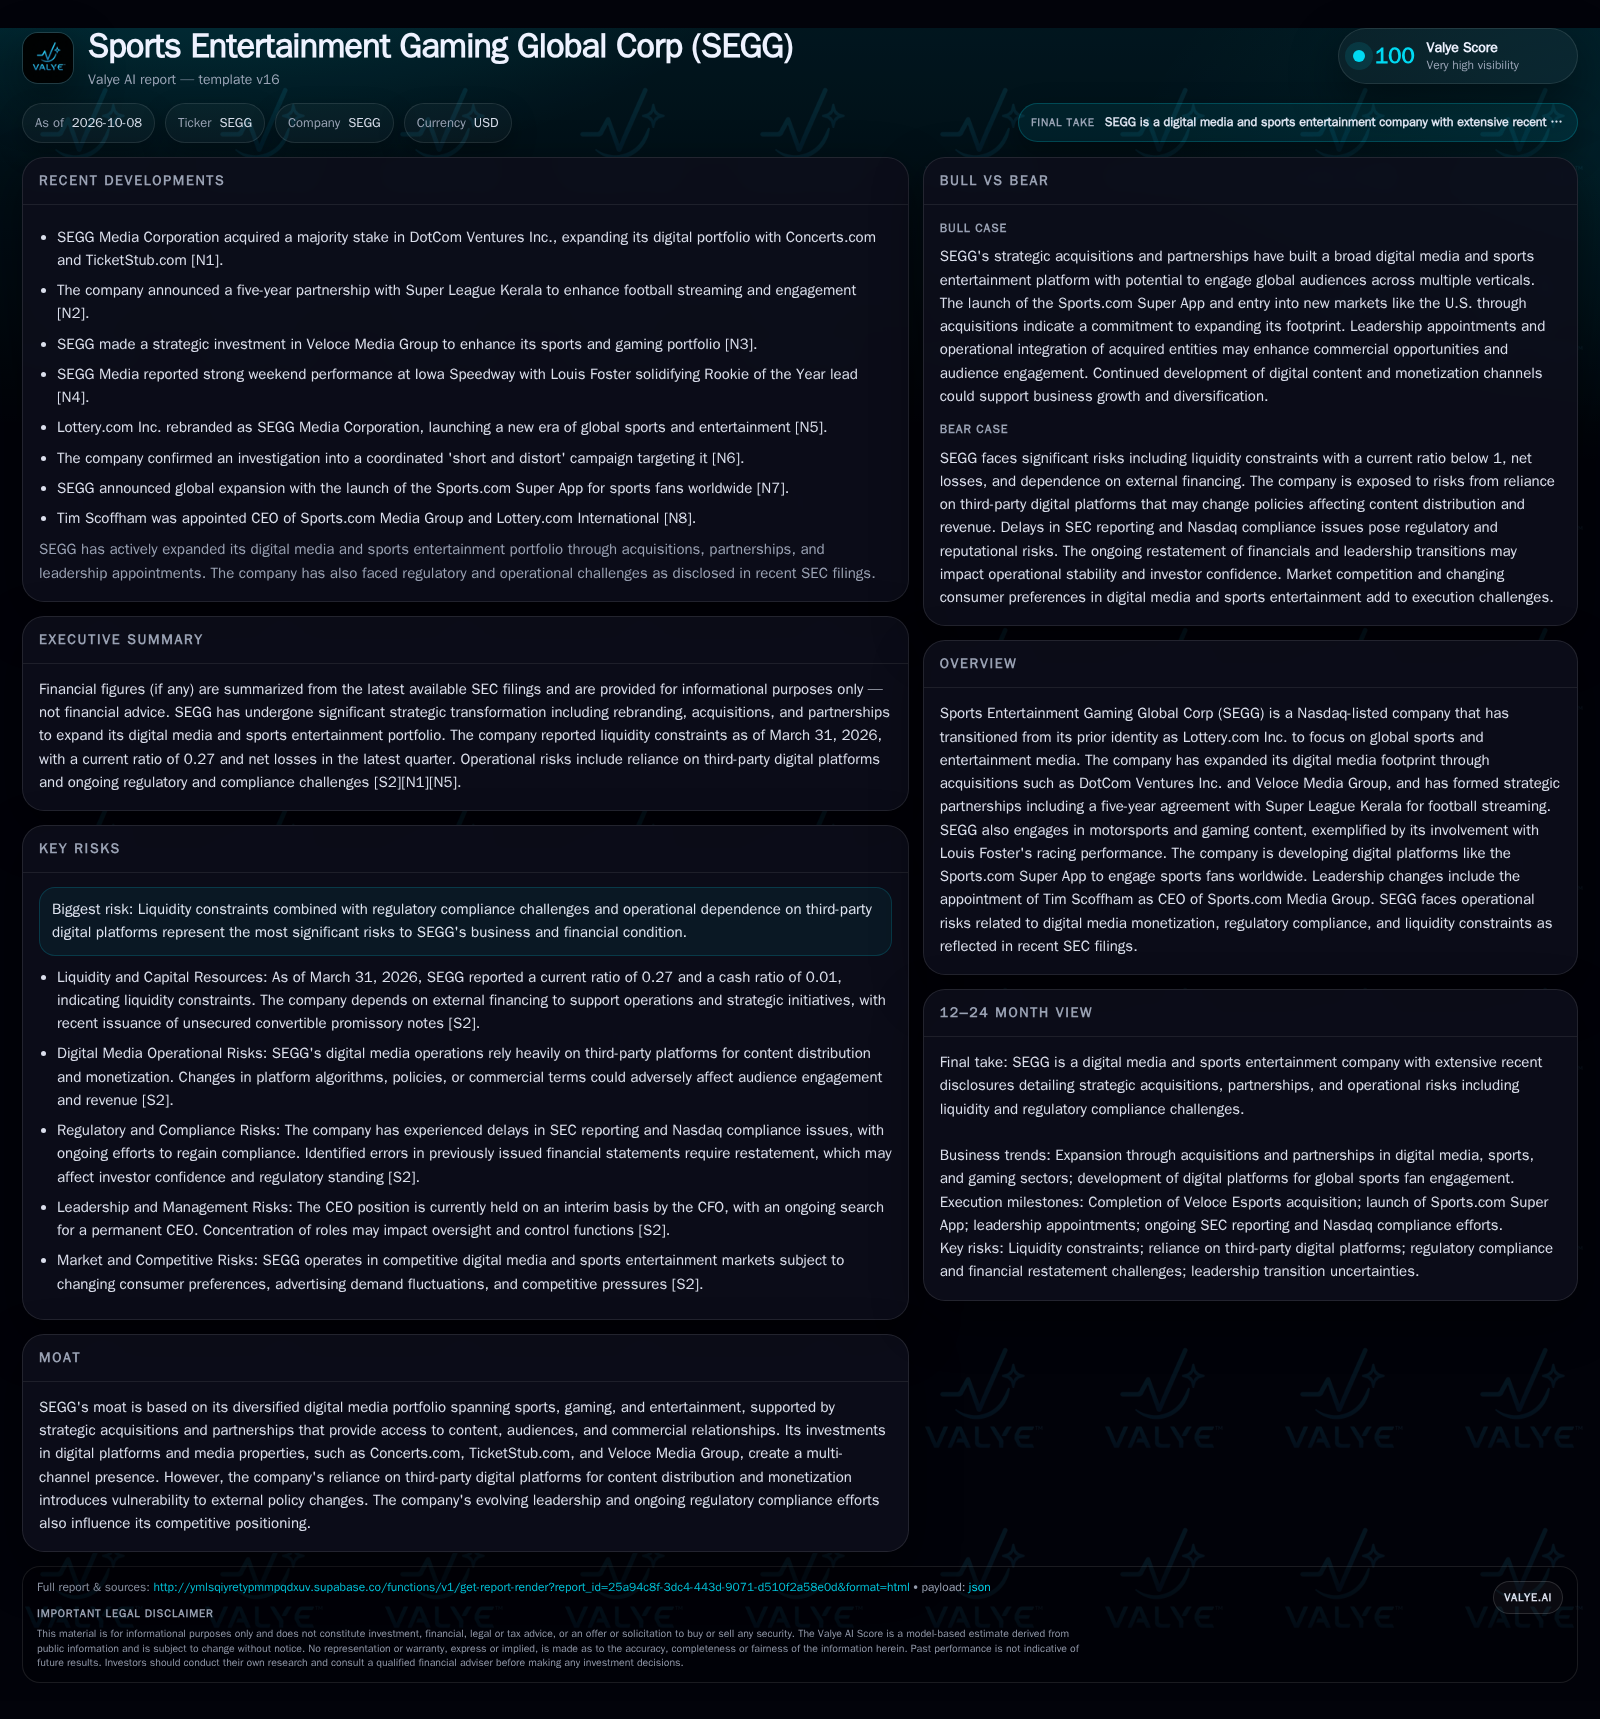
Sports Entertainment Gaming Global Corp (SEGG) has rapidly expanded its digital sports and entertainment portfolio via acquisitions and rebranding, targeting engagement across sports, gaming, and event media. However, as of March 2026, SEGG faces critical liquidity pressure, ongoing regulatory and financial restatement complexities, and high operational dependence on external digital platforms. The company’s ability to monetize its broadened asset base and transition to sustainable growth remains an open question amid pronounced execution and capital risks. [S2] [N1] [N5]
Sports Entertainment Gaming Global Corp (SEGG) has pursued a bold transformation from a lottery-focused operator to an aspiring digital sports and entertainment media conglomerate. Acquisitions of DotCom Ventures and Veloce Esports, a rebranding effort, and the launch of new digital engagement platforms signal a shift toward multi-vertical, global digital reach. The central question is whether SEGG can stabilize its operations and convert its diversified asset base into sustainable revenue and cash flow before capital and credibility erode further.
Strategic Expansion Meets Immediate Financial and Regulatory Headwinds
SEGG has made a series of high-profile moves to reposition itself as a global sports and entertainment media company, completing the acquisitions of DotCom Ventures (owner of Concerts.com and TicketStub.com) and Veloce Esports, and securing a five-year partnership with Super League Kerala to drive football streaming engagement. These developments have diversified SEGG’s digital asset base and extended its reach into motorsports, gaming, and live event media. [N1] [N2] [N3] [S2]
However, as of March 31, 2026, SEGG reported cash and equivalents of just $785,905 against current liabilities of $54 million, yielding a current ratio of 0.27 and a cash ratio of 0.01. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S2]
Compounding these financial strains are ongoing regulatory and reporting issues: SEGG has experienced delays in SEC reporting, faces Nasdaq compliance challenges, and is restating prior financials after uncovering legacy transaction irregularities. The CEO position is held on an interim basis by the CFO, reflecting leadership instability during a critical period. [S2] [N8]
Digital Media Monetization: Scale, Platform Risk, and Funding Realities
SEGG’s business model now centers on aggregating and monetizing digital audiences across sports, entertainment, and gaming verticals. The company’s assets—including event-focused domains (Concerts.com, TicketStub.com), esports content (Veloce), and the Sports.com Super App—could generate revenue through advertising, sponsorships, subscription models, ticketing fees, and digital content sales if successfully scaled.
However, these revenue streams are highly sensitive to audience scale, engagement, and the terms of distribution. SEGG relies on external digital platforms (e.g., social media, streaming services) for content reach and monetization, meaning any unfavorable algorithm or policy changes can materially impact traffic and ad yield. This introduces structural volatility in both top-line and margin outcomes.
On the cost side, digital media and content operations typically carry high fixed costs (content creation, rights, platform development), with variable costs tied to audience acquisition and technology infrastructure. If SEGG can grow its user base and engagement, operating leverage could drive margin expansion; if not, fixed costs could outpace revenue. [S2]
Multi-Asset Portfolio: Differentiation vs. Platform and Peer Pressures
SEGG’s competitive position rests on its attempt to integrate a portfolio of digital sports, entertainment, and gaming assets, creating a multi-channel brand ecosystem. The company’s acquisitions provide access to global sports fans, event attendees, and gaming communities. Strategic partnerships—such as with Super League Kerala—may further enhance audience relevance and content breadth. [N2] [N3]
However, the landscape is intensely competitive, featuring both global digital media giants (with deep content libraries and proprietary platforms) and nimble single-vertical specialists. SEGG’s lack of proprietary distribution infrastructure increases dependence on third-party platforms, limiting its pricing power and heightening vulnerability to external gatekeepers.
Switching friction for digital consumers remains low: sports fans and gamers can migrate to alternative platforms with minimal cost. SEGG’s ability to foster differentiated engagement—potentially via exclusive content, community features, or integrated experiences—will be key to defending against substitution and achieving sustainable retention.
If Platform Integration and Audience Growth Accelerate, Monetization Leverage Could Emerge
In a favorable scenario, SEGG successfully integrates its acquired assets, leverages the Sports.com Super App, and forges high-engagement partnerships. This could drive rapid audience acquisition and retention, creating a compelling platform for advertisers, sponsors, and direct-to-consumer monetization.
Evidence supporting this scenario would include sharp growth in active users and engagement metrics across SEGG’s digital properties, visible traction for the Super App, and successful launches of exclusive content or live events. Early signs of commercial partnership expansion and improved gross margin would further validate the transition from asset aggregation to scalable monetization.
If SEGG can demonstrate positive operating cash flow and renewed regulatory compliance, the company could regain access to lower-cost capital and attract strategic partners, reinforcing a virtuous cycle of growth and operational stability.
Piecemeal Progress and Persistent Constraints Define Near-Term Outlook
The most plausible near-term scenario is one of incremental progress: SEGG continues to integrate acquisitions, builds out digital offerings, and pursues partnerships, but faces ongoing liquidity and regulatory headwinds. Revenue may grow modestly from new digital channels, but margins remain pressured by fixed costs and platform fees.
Operational execution is likely uneven: delays in product launches, leadership turnover, and sporadic regulatory developments could disrupt momentum. The company remains reliant on external financing to bridge cash gaps, with the risk of dilution or unfavorable funding terms.
Confirmation of this scenario would come from stable or slightly rising top-line figures, continued net losses, and recurring updates on compliance efforts and financing rounds. Falsification would require either a decisive operational turnaround (e.g., cash flow breakeven) or a severe funding or regulatory setback.
Liquidity Crunch and Platform Shocks Could Trigger Value Erosion
A significant change in third-party platform policies or a drop in digital traffic could sharply reduce monetization, compounding financial distress.
Further regulatory setbacks—such as loss of Nasdaq listing, additional restatements, or unresolved leadership gaps—could undermine investor and partner confidence, accelerating outflows and impairing SEGG’s strategic flexibility.
This scenario would be confirmed by missed financial obligations, workforce reductions, asset sales under duress, or public statements about going concern risk.
Milestones and Metrics That Will Determine SEGG’s Digital Media Trajectory
Sustained growth in active users and engagement metrics across the Sports.com Super App and other core digital platforms (if disclosed) would indicate successful audience acquisition.
Revenue mix evolution: Tracking the proportion of revenue from advertising, sponsorships, ticketing, and digital content sales would clarify monetization progress (if disclosed).
Gross margin and operating cash flow trends: Improvement here would suggest operating leverage and monetization effectiveness.
Updates on external financing: Announcements of new capital raises, debt terms, or equity dilution will signal funding sustainability and cost.
Regulatory and compliance milestones: Restoration of timely SEC filings, resolution of Nasdaq listing issues, and completion of financial restatements are essential for credibility.
Leadership stability: Appointment of a permanent CEO and retention of key operational talent would reduce execution risk.
Material changes in third-party platform policies or distribution agreements could significantly impact digital reach and monetization.
Announcements of major new partnerships, exclusive content deals, or high-profile event activations would provide evidence of commercial traction.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments