
NeoVolta’s Scale Ambition: From Niche Residential Storage to Utility-Scale Battery Manufacturing
NeoVolta Inc. is pursuing an aggressive transformation from a regional residential energy storage manufacturer to an integrated, multi-segment energy solutions provider, underpinned by new product launches, strategic acquisitions, and a major utility-scale manufacturing joint venture. The company’s ability to translate rapid revenue growth and product innovation into sustainable economics will be tested by capital intensity, competition, and execution complexity as it enters the next phase.
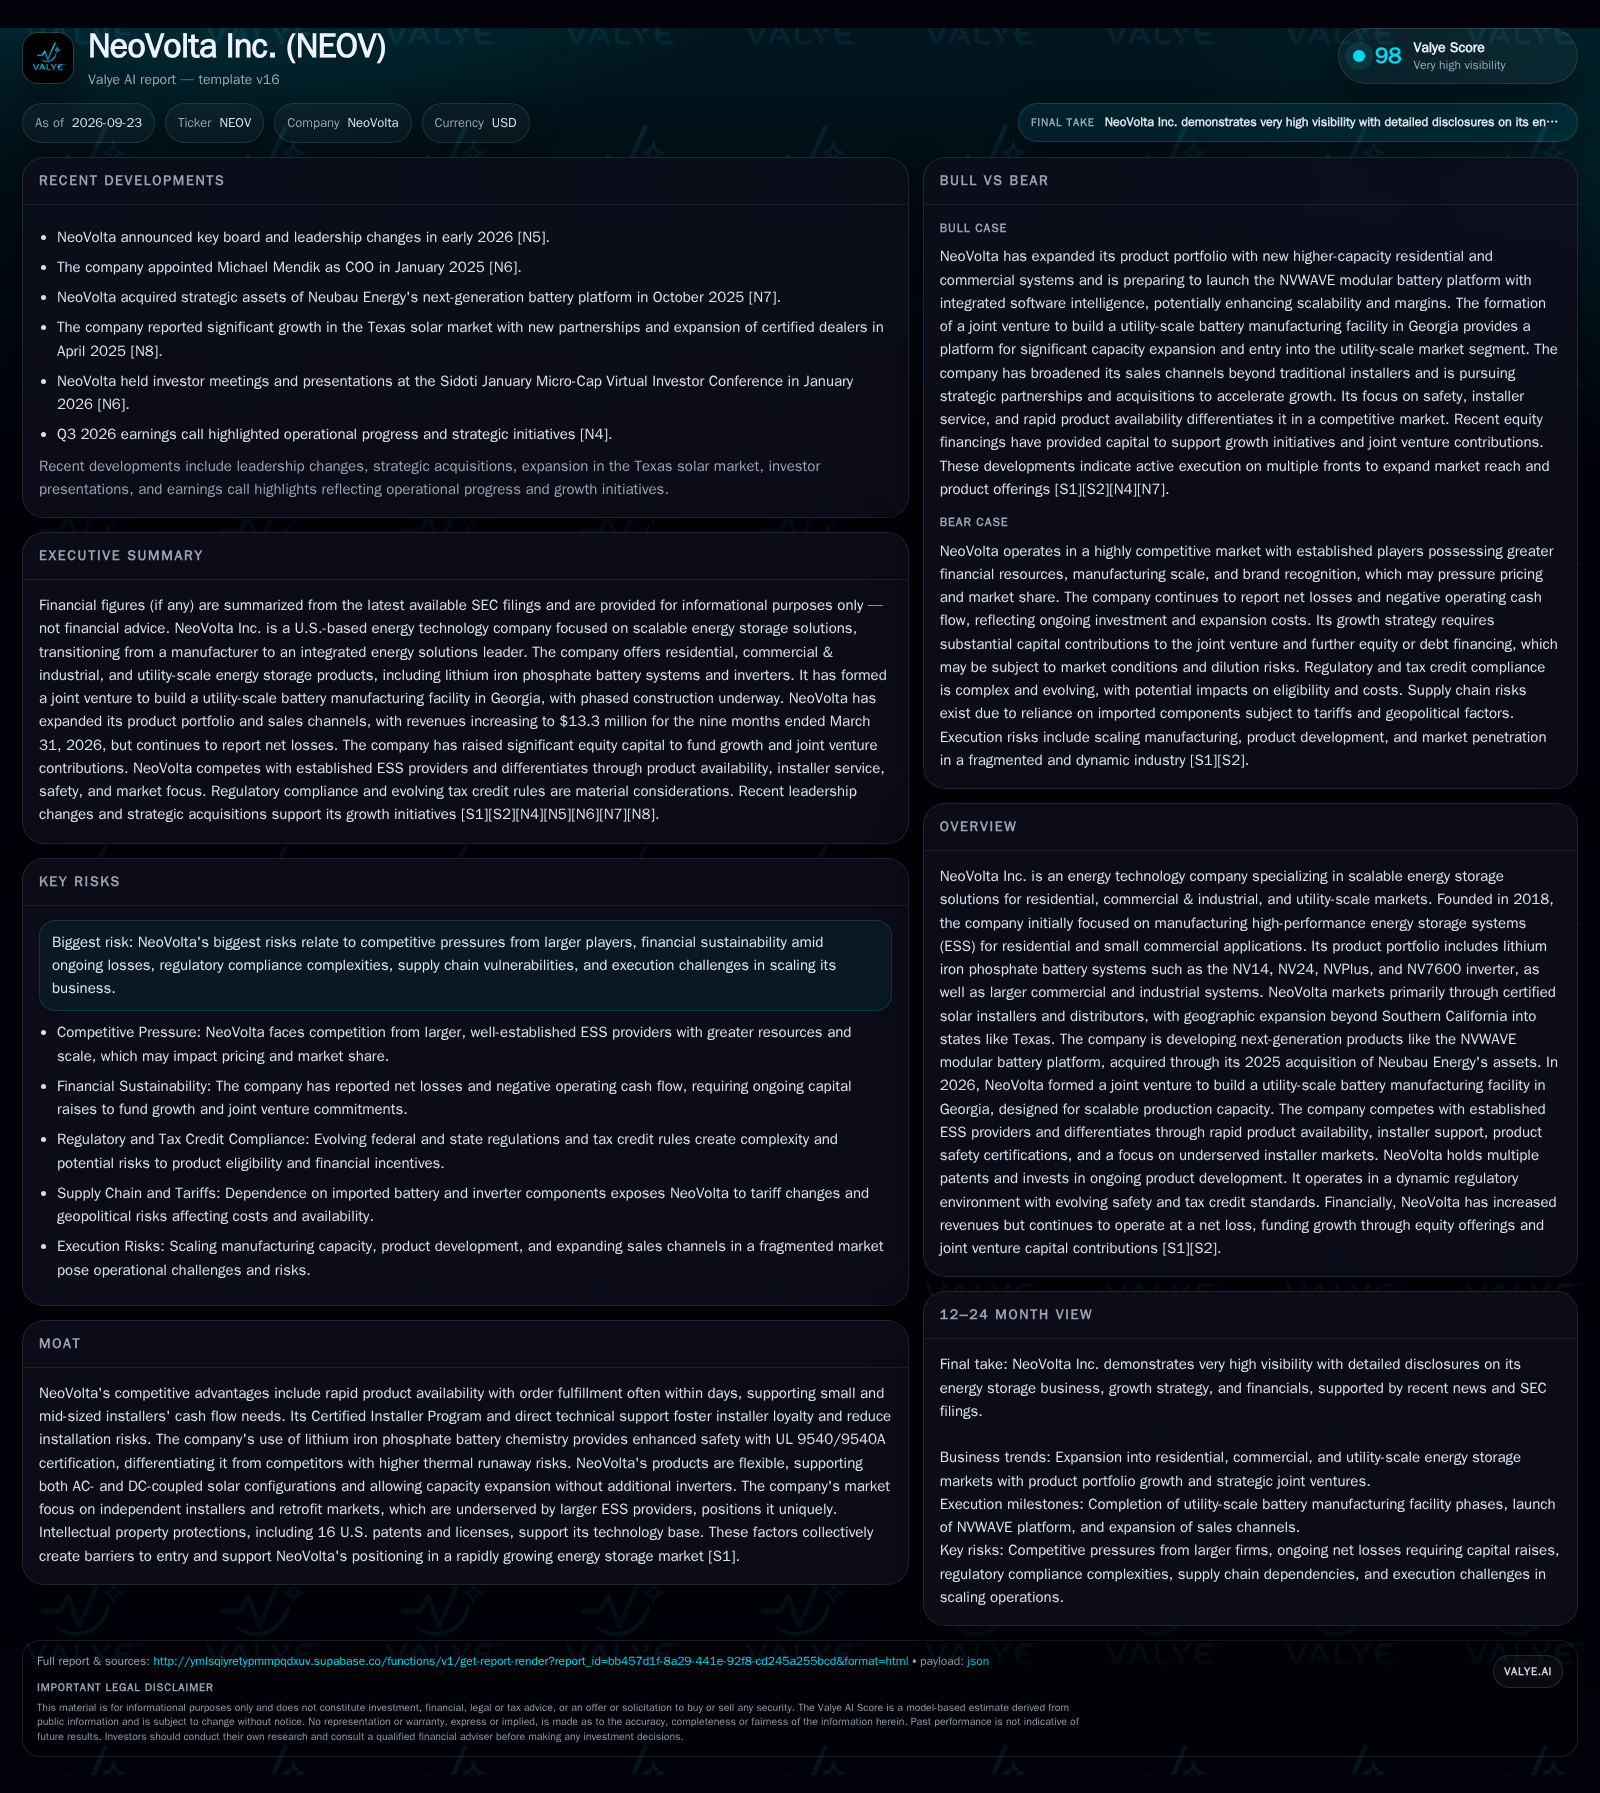
NeoVolta is rapidly expanding from residential energy storage into commercial and utility-scale markets, with a new modular platform, major joint venture manufacturing buildout, and strong revenue acceleration. The company’s future will depend on scaling its new Georgia facility, integrating acquired technology, and achieving profitable growth amid sector competition and capital needs. [S1] [S2]
NeoVolta Inc. stands at a strategic inflection point: its transition from a focused residential energy storage manufacturer to a broader, integrated energy solutions provider is now underway. With rapid revenue growth, a significant pipeline of new products, and a transformative utility-scale manufacturing joint venture in Georgia, NeoVolta is betting that its differentiated technology and installer-focused model can carve out share in the expanding U.S. energy storage market. However, the company’s ability to achieve profitable scale will hinge on execution in manufacturing, capital deployment, and navigating entrenched competition.
Recent Moves Redefine NeoVolta’s Scale and Market Ambition
NeoVolta’s most material current developments reflect a bold expansion strategy. Revenues for the nine months ended March 31, 2026, reached $13.3 million, up sharply from $3.7 million in the prior-year period, marking a phase of rapid commercial traction. Gross margins have stabilized around 25%, but operating expenses and net losses have grown, with a net loss of $21.5 million for fiscal 2026. [S2]
The company’s most transformative step is its January 2026 joint venture to build a utility-scale battery manufacturing facility in Georgia, where NeoVolta holds an 80% stake. The initial phase targets 2 GWh of annual capacity, scalable to 8 GWh, with production expected to begin in fiscal 2027 Q1. NeoVolta has already made $15 million in capital contributions and raised $26.3 million net in a public equity offering to fund expansion. [S1]
Product innovation is also front and center: NeoVolta is preparing to launch the NVWAVE modular battery platform, a scalable, plug-and-play system for residential and C&I use, developed with technology acquired from Neubau Energy in October 2025. [S1] [N7]
These moves signal NeoVolta’s intent to compete beyond its original residential niche, pursuing a multi-segment strategy with substantial capital and operational requirements.
How NeoVolta’s Business Model Could Scale—and Where Economics Get Tested
NeoVolta’s core business model is built around selling energy storage systems (ESS) and inverters to residential, commercial, and utility-scale customers, primarily via certified solar installers and distributors. The company’s value proposition emphasizes rapid product delivery, safety (lithium iron phosphate chemistry), and flexibility for retrofit applications. [S1]
The economics of the residential and C&I segments are largely driven by system volume, product mix (battery-only, inverter-only, or integrated solutions), and the ability to capture margin through differentiated features or channel relationships. Gross margins are currently around 25%—in line with premium hardware providers but below those of pure software or recurring revenue models. [S2]
The launch of the NVWAVE modular platform could improve average selling prices and margins if it enables larger system deployments and reduces installation complexity. However, these gains are not automatic: the capital cost of new product development and inventory, as well as installer incentives, can pressure near-term profitability.
The utility-scale joint venture introduces a fundamentally different economic profile. Manufacturing at scale could provide operating leverage and lower per-unit costs, but initial capital outlays are high and ramping a new facility carries execution risk. NeoVolta’s 80% ownership means it bears most of the upside and capital requirements. The addressable U.S. market across all segments is estimated at $45 billion by 2030, but actual capture will depend on channel access, production reliability, and the ability to meet evolving regulatory requirements. [S1]
Installer Focus, Safety, and Speed: Can NeoVolta Carve Out a Defensible Niche?
NeoVolta operates in a highly competitive landscape. Incumbents like Tesla, LG Chem, Sonnen, Enphase, SunPower, Sunrun, and Fluence have greater scale, brand recognition, and vertically integrated offerings. [S1]
NeoVolta differentiates itself with rapid product availability—often fulfilling orders within days—and an installer-centric service model. Its Certified Installer Program and direct technical support are designed to foster loyalty among independent installers, a segment often underserved by larger players. The use of lithium iron phosphate chemistry, with UL 9540/9540A safety certification, is another distinguishing feature, addressing fire safety concerns that have dogged some competitors.
The company’s patent portfolio (16 U.S. patents, including those from Neubau Energy) adds some intellectual property protection, but defensibility in hardware-centric businesses often relies more on channel relationships, execution, and service than on patents alone.
NeoVolta’s focus on retrofit and independent installer markets could allow it to avoid direct price wars with national or vertically integrated solar/storage providers, but these markets can be fragmented and cost-sensitive. Moving into the utility-scale segment brings new competitors—industrial conglomerates and global battery manufacturers—with deep pockets and established customer relationships. NeoVolta’s ability to maintain speed, service, and safety advantages at scale remains an open question.
From Rapid Growth to Profitable Scale: What Would Confirm a Breakout
The favorable scenario for NeoVolta hinges on its ability to successfully ramp its Georgia manufacturing facility, launch the NVWAVE platform, and translate installer/channel momentum into accelerated sales across residential, C&I, and utility segments.
If the joint venture achieves its targeted 2 GWh annual output on schedule, NeoVolta could establish itself as a credible domestic supplier at a time when U.S. grid resilience and domestic content requirements are increasingly valued. The modular NVWAVE platform could drive higher average deal sizes and enable more standardized, lower-cost installations, improving gross margins and channel stickiness.
Evidence that would confirm this scenario includes: a smooth production ramp and on-time commissioning of the Georgia facility; multi-quarter growth in system shipments and revenue per system; a rising proportion of sales from new products; and a trajectory toward positive operating cash flow. New partnerships or contracts for utility-scale deployments would further validate market acceptance.
Margins could improve if scale reduces per-unit costs and if software/energy optimization features drive premium pricing. A sustained ability to attract and retain installers, especially in expansion markets like Texas, would indicate differentiation is holding.
Managing Growth Pains: The Most Likely Near-Term Trajectory
The most plausible scenario is that NeoVolta continues to grow revenues rapidly, but profitability remains elusive through the next 12–24 months. The company may achieve moderate sales traction with the NVWAVE platform and expand its commercial/industrial presence, but faces ongoing cost pressures from R&D, marketing, and the capital intensity of scaling manufacturing.
The Georgia facility’s ramp may encounter typical new-factory challenges—yield issues, supply chain delays, or regulatory approval bottlenecks—delaying the intended cost and scale benefits. Installer loyalty and channel expansion may be offset by competitive discounting from larger players or macroeconomic softness in the residential solar/storage market.
Evidence supporting this scenario would include continued double-digit revenue growth, but persistent operating losses, periodic equity raises to fund working capital and joint venture contributions, and a gradual rise in product mix complexity. Gross margins may fluctuate as new products and channel incentives are introduced, and operating expenses could remain elevated as the company invests ahead of scale.
The company’s ability to maintain strong relationships with independent installers and deliver on new product timelines will be central to this outcome.
Capital Strain and Competitive Pressure Could Derail the Expansion
The adverse scenario centers on NeoVolta’s inability to achieve sufficient sales growth or manufacturing scale to offset capital requirements and operating losses. If the Georgia facility faces prolonged delays, cost overruns, or underutilization, the company could be forced to raise additional capital on unfavorable terms or reduce its expansion ambitions.
Aggressive pricing or bundling from major ESS competitors could erode NeoVolta’s installer base and compress margins, especially if residential solar/storage demand softens or regulatory/tax credit regimes shift unfavorably. The capital-intensive nature of manufacturing, combined with ongoing R&D and channel investments, could stretch liquidity and trigger dilution or debt burdens.
Execution risk is amplified by the complexity of scaling new products and manufacturing lines, while supply chain disruptions or regulatory changes (e.g., new safety or domestic content rules) could increase costs or delay market access.
Evidence of this scenario would include missed production milestones at the Georgia facility, declining gross margins, evidence of installer churn, larger-than-expected equity raises, or any signal that NeoVolta is losing share to better-capitalized rivals.
Milestones That Will Test NeoVolta’s Strategic Bet on Scale and Differentiation
Commissioning and production ramp rate of the Georgia battery manufacturing facility—on-time delivery and initial output volumes will be crucial.
Adoption rate and revenue contribution of the NVWAVE modular platform; a useful metric would be percentage of total system shipments attributable to NVWAVE, if disclosed.
Gross margin trends by product line, especially as new modular and commercial systems are introduced.
Installer and channel partner retention rates, particularly in new geographies such as Texas; evidence of expanding or contracting certified installer base would help test the thesis.
Operating cash flow trajectory—progress toward positive cash flow as scale increases.
Frequency and size of additional equity or debt financings, which would signal capital sufficiency or strain.
Regulatory developments affecting tax credits, safety standards, or domestic content requirements that could impact demand or cost structure.
Competitive responses—any signs of price wars, new product launches, or strategic moves from larger incumbents targeting NeoVolta’s core installer segment.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments