
Natera’s Diagnostic Platform: Scaling Personalized Genomics While Navigating Adoption and Regulatory Shifts
Natera’s personalized molecular diagnostics in oncology, women’s health, and organ transplantation are driving robust revenue growth and clinical adoption. As the company narrows net losses and expands its footprint via acquisitions and evidence-building, the next phase will hinge on the pace of payer adoption, regulatory clarity for lab-developed tests, and the ability to defend differentiated technology against advancing competition.
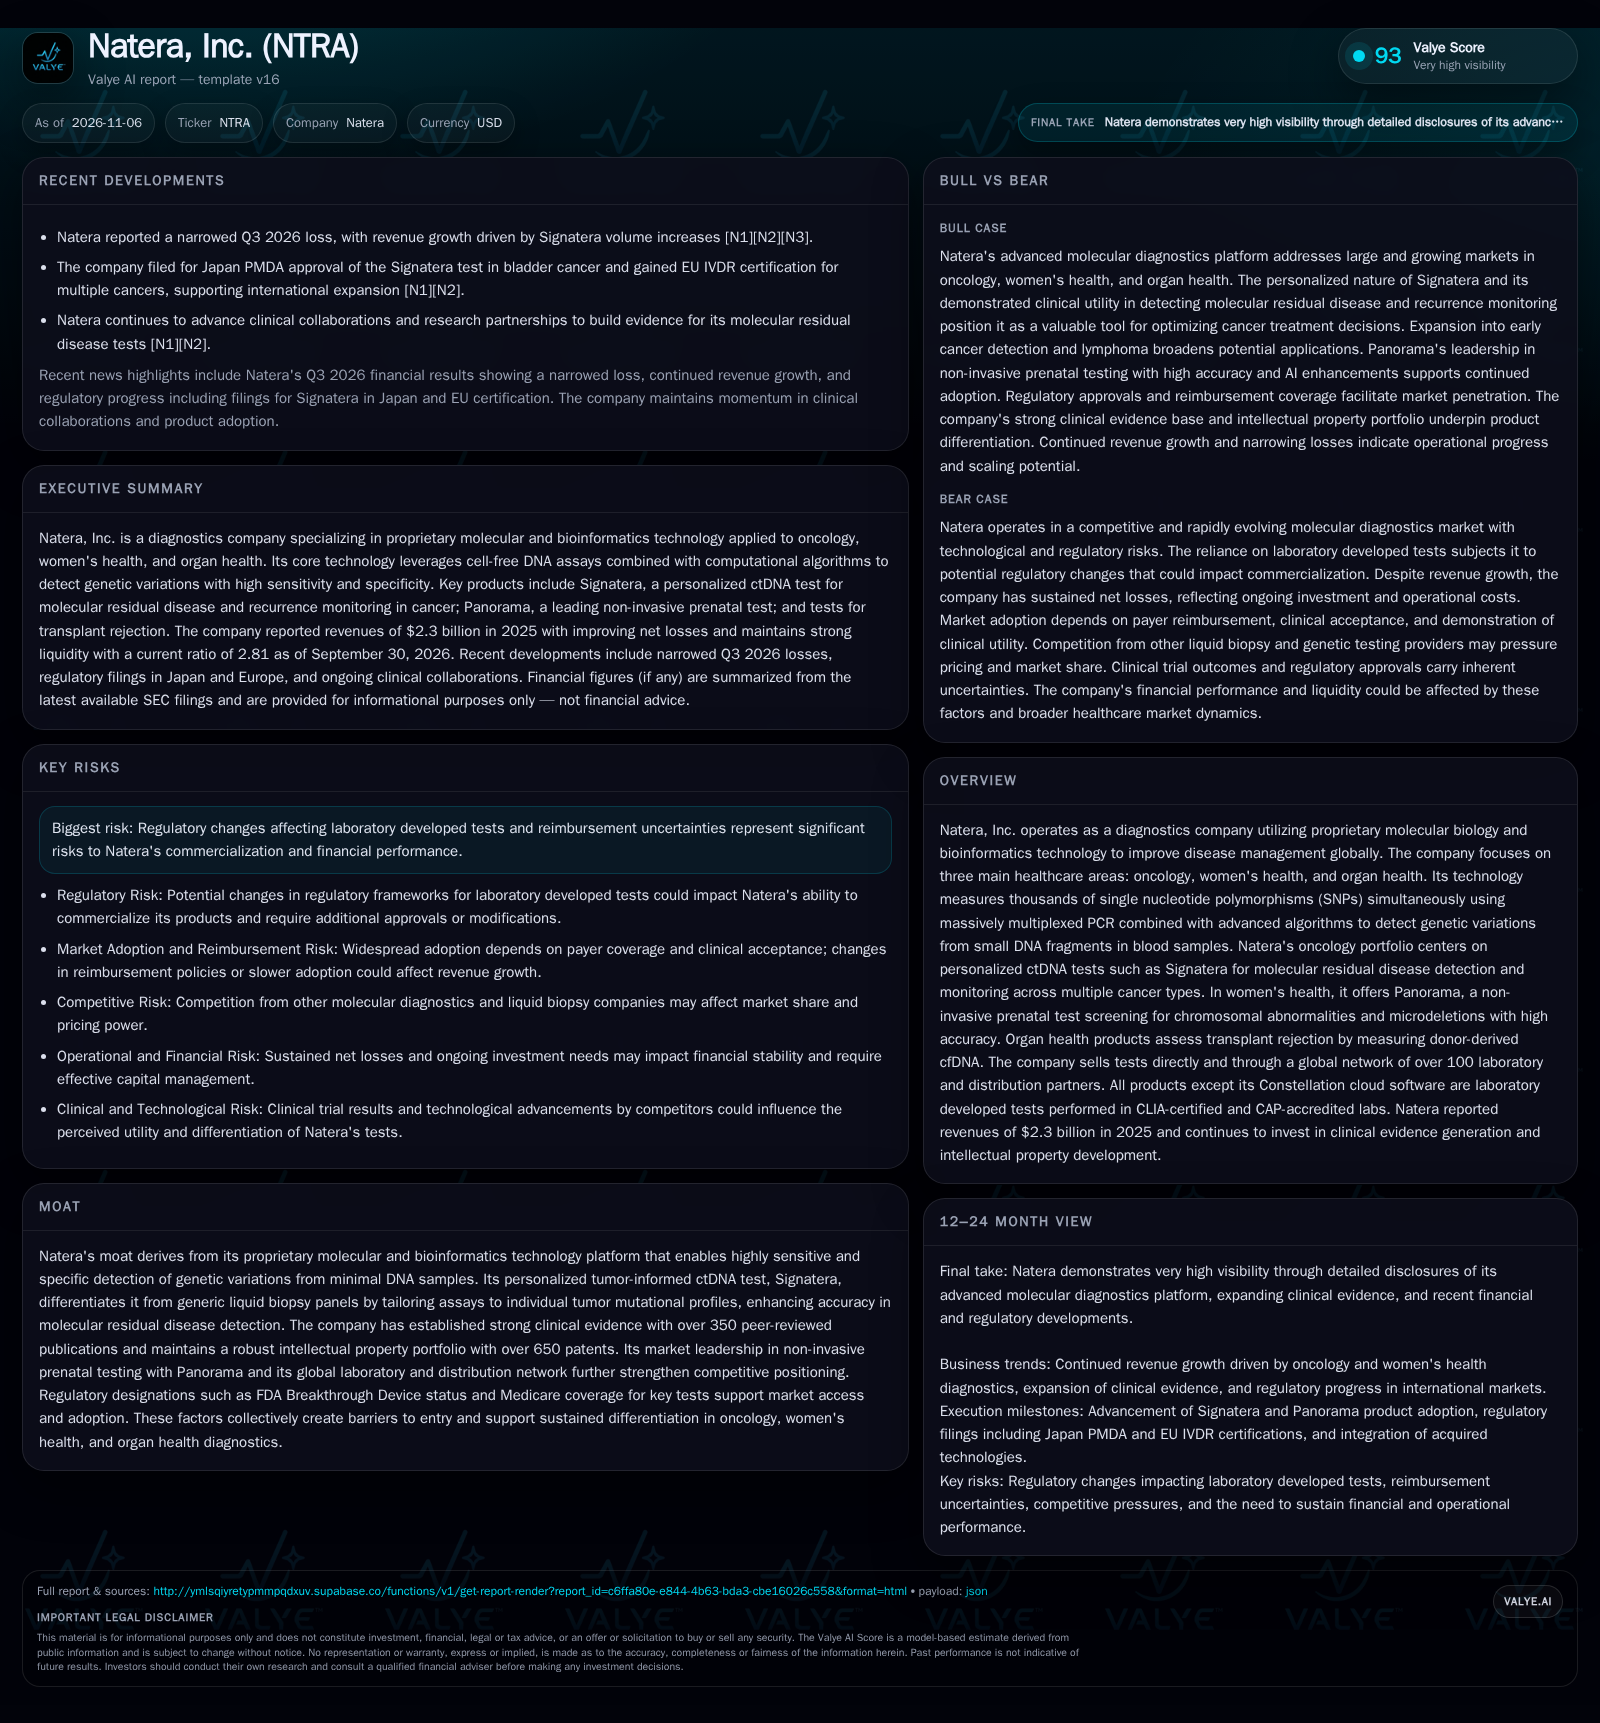
Natera’s revenue climbed to $2.3 billion in 2025, propelled by its proprietary cell-free DNA diagnostics, especially Signatera in oncology and Panorama in prenatal testing. The company’s net losses have narrowed, and it retains a reported current ratio. Key future drivers include expanding payer coverage, clinical adoption, and regulatory clarity for its lab-developed test model, while competitive and reimbursement risks remain elevated. [S1] [S2]
Natera is advancing the frontier of molecular diagnostics with a platform built on proprietary cell-free DNA analysis, targeting high-value applications from oncology to prenatal and transplant care. Its latest results show significant revenue growth and narrowing losses, underpinned by the clinical traction of flagship products like Signatera and Panorama. However, as the company scales, it must navigate complex reimbursement dynamics, a shifting regulatory landscape for lab-developed tests, and mounting competition in liquid biopsy and genetic testing. The next phase will test whether Natera’s scientific differentiation and expanding evidence base can sustain commercial momentum amid these evolving external pressures.
Recent Financial Performance and Product Expansion Shape Natera’s Strategic Position
Natera reported 2025 revenues of $2.3 billion, a substantial increase from $1.7 billion in 2024, reflecting strong demand for its molecular diagnostics across oncology, women’s health, and organ health. Net losses narrowed to $208.2 million in 2025 from $434.8 million in 2023, and Q3 2026 saw a further reduction with a net loss of $59.9 million. This trajectory signals improving operating leverage as test volumes scale, particularly for Signatera, the company’s personalized ctDNA test for molecular residual disease (MRD) detection. [S1] [S2]
The December 2025 acquisition of Foresight Diagnostics has extended Natera’s MRD capabilities into lymphoma and enhanced detection sensitivity, broadening the clinical and commercial reach of the Signatera platform. Meanwhile, Panorama continues to lead the U.S. non-invasive prenatal testing market by volume, benefiting from AI-driven accuracy improvements. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S1] [S2]
How Natera’s Diagnostics Convert Clinical Innovation into Revenue Growth
Natera generates revenue primarily through laboratory-developed tests (LDTs) performed in CLIA-certified and CAP-accredited labs, with commercial mechanics driven by test volume, payer mix, and reimbursement rates. In oncology, Signatera’s personalized ctDNA approach commands premium pricing relative to generic liquid biopsy panels, reflecting both the complexity of the assay and its clinical utility in recurrence monitoring, MRD detection, and treatment response assessment. As payer coverage expands—particularly Medicare for multiple cancer types—test volume and revenue per test may both rise, supporting top-line growth.
Women’s health is anchored by Panorama, where high test volume and relatively stable reimbursement help drive scale. The economics of Natera’s model feature high fixed costs (lab infrastructure, R&D, evidence generation), but variable costs per test are moderate, enabling margin expansion as volume increases. This operating leverage is now visible in narrowing net losses despite sustained R&D and commercial investment. However, gross margins and cash flow are sensitive to changes in reimbursement rates and payer mix, as well as the pace of adoption for new tests in early cancer detection and organ health.
Future economics will depend on the company’s ability to shift a larger share of volumes to higher-margin, clinically differentiated tests and on the durability of payer coverage as competition intensifies.
Defending Leadership Amid Intensifying Liquid Biopsy and Genomics Competition
Natera’s core differentiation lies in its proprietary molecular and bioinformatics platform, enabling highly sensitive ctDNA detection at low variant frequencies and SNP-based prenatal testing. The tumor-informed approach of Signatera, customizing assays to each patient’s tumor profile, is a key advantage over more generic liquid biopsy panels. This specificity supports both clinical adoption and payer coverage, underpinned by a robust evidence base (350+ publications) and a deep intellectual property portfolio (650+ patents). [S1]
However, the molecular diagnostics landscape is highly dynamic, with established players and emerging entrants investing heavily in liquid biopsy, early cancer detection, and genetic testing. Competitor categories include large diagnostics conglomerates, genomics start-ups, and academic spinouts—many of which are pursuing similar cfDNA and MRD opportunities. Advances in sequencing technology, AI, and multi-cancer early detection could compress Natera’s lead if rivals achieve comparable sensitivity or lower costs. Additionally, channel partnerships and global distribution, while broad, may not guarantee exclusive relationships, leaving Natera vulnerable to competitive displacement if clinical data or payer economics shift.
The company’s moat is reinforced by clinical guidelines, Medicare and commercial coverage, and regulatory designations, but these can evolve. Long-term defensibility will depend on maintaining technological, evidentiary, and operational advantages as the field matures.
If Payer Adoption Accelerates and Regulatory Stability Holds, Natera’s Growth Could Outpace Expectations
In a favorable scenario, Natera leverages its clinical evidence and payer relationships to drive accelerated adoption of Signatera across new cancer indications—especially following the Foresight Diagnostics acquisition and expansion into lymphoma. As additional clinical trials validate the utility of MRD-guided treatment and early detection, both Medicare and commercial payers broaden coverage, supporting higher test volumes and improved reimbursement rates. Women’s health continues to grow as Panorama maintains leadership, while organ health diagnostics gain traction in transplant centers.
If regulatory frameworks for LDTs remain stable or move toward formal approval pathways that Natera is well-positioned to satisfy, the company could avoid costly operational disruptions and maintain speed to market for new assays. Operating leverage would improve as fixed infrastructure costs are spread across rising volumes, driving profitability inflection. Evidence confirming this scenario would include sustained double-digit revenue growth, margin expansion, new payer contracts, and positive regulatory developments.
Sustained Growth with Margin Improvement—But Competitive and Regulatory Uncertainties Persist
The most plausible outcome is that Natera continues to grow revenue in the high single-digits to low double-digits, driven by steady adoption in oncology (Signatera), women’s health (Panorama), and organ health. Net losses narrow further as operating leverage materializes, but the company remains sensitive to reimbursement dynamics and the pace of clinical adoption for newer tests. Competitive pressure from other liquid biopsy and genomics players results in modest pricing pressure, but Natera’s evidence base, payer relationships, and product differentiation help defend share.
Regulatory changes for LDTs remain a persistent uncertainty but do not result in immediate disruption. The company continues to invest heavily in R&D and clinical studies, maintaining its evidence-generation flywheel. Confirmation of this scenario would come from stable or improving gross margins, continued publication of positive clinical data, and maintenance of payer coverage for core products.
Regulatory Shocks or Payer Retrenchment Could Undercut Revenue and Delay Profitability
In a negative scenario, regulatory authorities implement stricter requirements for laboratory developed tests, imposing new approval processes or restricting the use of existing assays. Natera faces delays or increased costs in bringing new tests to market, and some current products risk losing reimbursement eligibility if they cannot rapidly meet evolving standards. Simultaneously, payers—faced with budget constraints or new evidence—tighten coverage for MRD testing or prenatal screening, reducing reimbursement rates or eligibility criteria.
Competitive advances erode Natera’s pricing power or clinical differentiation, particularly if rivals demonstrate equivalent or superior performance in head-to-head trials. Revenue growth slows or reverses, operating leverage stalls, and net losses widen. Leading indicators of this scenario would be negative regulatory news, payer coverage cuts, weaker-than-expected test volumes, or loss of key commercial contracts.
What Will Determine Natera’s Trajectory in Advanced Diagnostics?
Quarterly test volume growth for Signatera and Panorama—if disclosed—would clarify the pace of adoption in core markets.
Updates on payer coverage expansions or contractions, especially for MRD in new cancer types and for Panorama in women’s health.
Gross margin trends, as evidence of improved reimbursement mix or, conversely, pricing pressure and cost escalation.
Clinical trial readouts and new peer-reviewed publications supporting utility in early cancer detection, MRD, and transplant rejection.
Regulatory developments impacting laboratory developed tests (LDTs), including FDA or CMS policy shifts.
Competitive launches or trial results from other liquid biopsy or genomics companies targeting similar indications.
Cash burn rate and capital allocation, especially given ongoing R&D and potential for further acquisitions or regulatory-driven investment.
Progress in international expansion and uptake through laboratory and distribution partners, indicating global demand.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments