
Nova Minerals: Alaska Ambitions, Financial Realities, and the Road to Estelle Project Ownership
Nova Minerals’ redomicile to the U.S. and NYSE American listing mark a strategic pivot as the company seeks to advance its Estelle Project in Alaska. The next phase will test Nova’s ability to convert exploration into lasting value.
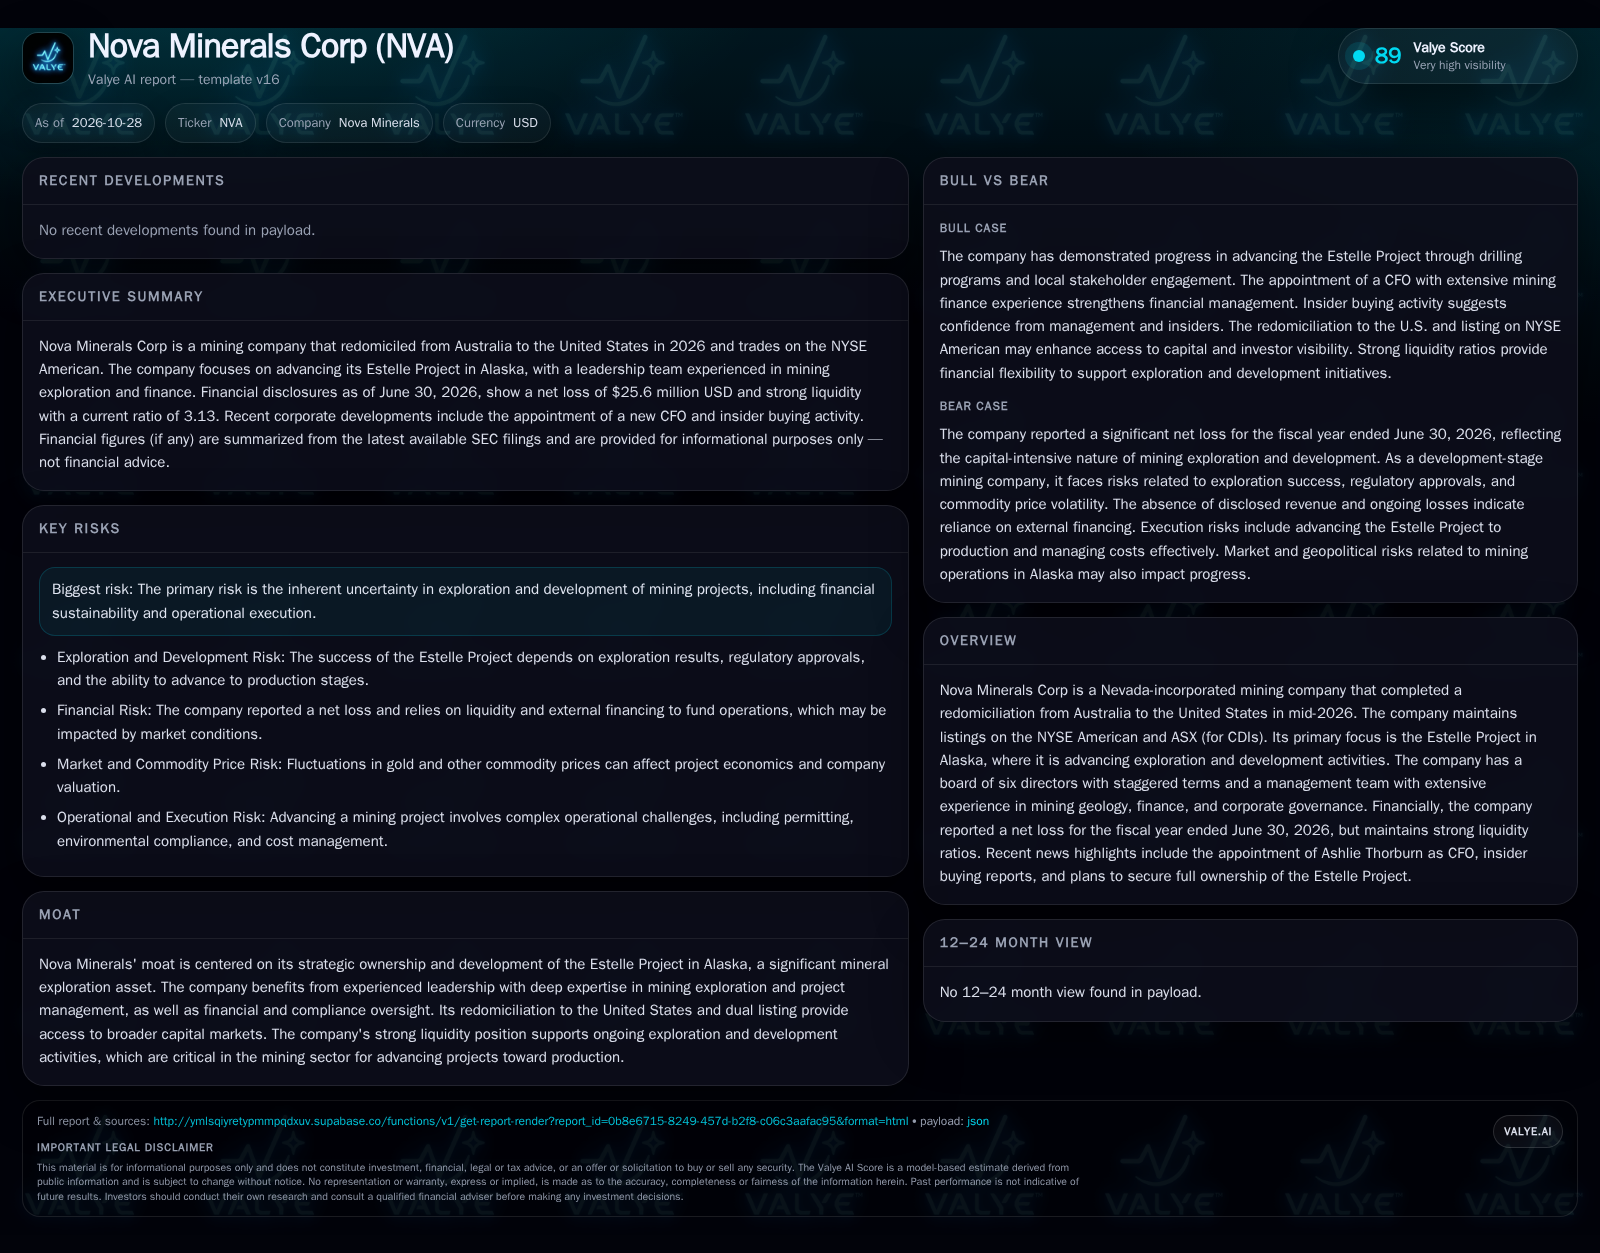
Nova Minerals has repositioned itself as a U.S.-domiciled mining developer with a primary focus on Alaska’s Estelle Project.Insider transaction activity was reported in the cited source; this activity does not by itself establish insider confidence. However, the company remains pre-revenue and loss-making, underscoring the importance of successful project advancement, cost control, and external funding capacity as it seeks 100% project ownership and moves toward potential production. [S1] [N1] [N2] [N3] [N5]
Nova Minerals Corp’s transition from an Australian to a U.S. domicile—coupled with a dual NYSE American and ASX listing—signals a deliberate bid to access deeper capital pools and enhance investor visibility. With the Estelle Project in Alaska as its flagship asset, Nova is squarely in the capital-intensive, high-risk phase of mineral exploration and early-stage development.
Strategic Redomicile, Project Focus, and Financial Position Define Today’s Nova Minerals
In June 2026, Nova Minerals completed its redomiciliation from Australia to the United States, positioning itself as the parent of the Nova Minerals group and listing on both the NYSE American and ASX. This move is intended to broaden access to U.S. capital markets and enhance the company’s visibility among North American investors. The company’s core operational focus remains the Estelle Project in Alaska, with ongoing exploration and a stated goal of seeking 100% ownership. However, the company reported a net loss of $25.6 million for the fiscal year, with no disclosed revenue—underscoring its pre-production, development-stage status. Recent insider buying activity and the appointment of Ashlie Thorburn as CFO, who brings significant mining finance experience, add to the current narrative of management commitment and operational readiness. [S1] [N1] [N2] [N3] [N5]
How Nova Minerals’ Economics Depend on Exploration Outcomes and Capital Efficiency
Nova Minerals’ business model is typical of early-stage mining developers: substantial upfront investment in exploration, drilling, permitting, and feasibility studies, with no current revenue stream to offset expenditures. The company’s $25.6 million net loss for FY2026 reflects heavy spending on exploration and corporate overhead, funded primarily by equity capital and potentially by future debt or strategic partnerships. Fixed costs are high due to the technical, regulatory, and logistical demands of Alaskan mineral development, while variable costs will rise as drilling and resource delineation accelerate.
Operating leverage in mining is binary—intense negative cash flow persists until commercial production begins, at which point fixed costs are spread over production volumes, potentially enabling high margins if resource grades and commodity prices are favorable. Until then, Nova’s economics hinge on its ability to advance the Estelle Project efficiently, control costs, and maintain access to capital. The absence of current revenue and the scale of reported losses reinforce that Nova’s future value is almost entirely tied to the successful progression of its flagship project and the broader capital markets’ continued willingness to finance high-risk, high-reward mineral development.
Project Location, Leadership, and Capital Access Shape Nova’s Position in the Mining Value Chain
Nova’s primary asset is its stake in the Estelle Project, located in Alaska—a jurisdiction with both geological promise and significant permitting, logistical, and environmental challenges. The company’s competitive positioning is influenced by several factors: the scale and quality of the Estelle resource (yet to be fully established), the experience of its executive team, and its recent U.S. redomicile and dual listing, which could facilitate access to capital relative to smaller, single-market peers.
Nova’s leadership team brings direct experience in North American and global mining projects, which may help navigate regulatory and operational hurdles. However, the project’s early stage means Nova is competing less on production metrics and more on its ability to generate credible exploration results, attract funding, and de-risk its asset relative to other gold and copper developers targeting U.S. and Canadian projects. The company faces indirect competition from other junior explorers and developers seeking capital and attention from the same investor and partner pool, as well as from established producers looking for acquisition targets. Substitution risk is tied primarily to global gold and copper supply dynamics, commodity price cycles, and the ability of Nova to demonstrate that Estelle can ultimately move from resource to reserve and into profitable production.
A Winning Sequence: Successful Resource Delineation, Stakeholder Alignment, and Capital Inflows
The most favorable scenario for Nova Minerals is a virtuous cycle in which the company’s drilling and exploration programs at the Estelle Project yield robust, scalable resource estimates that compare favorably with peer projects in Alaska and beyond. Effective stakeholder engagement, including local community and regulatory buy-in, would reduce permitting friction and enhance the project’s investability. This, combined with visible insider support (as suggested by recent insider buying), could attract new institutional and strategic investors, enabling non-dilutive or less-dilutive capital infusions.
Confirmation of this scenario would come from: the publication of materially upgraded resource estimates; positive, independent technical reports; successful completion of permitting milestones; and evidence of third-party investment or joint-venture interest in Estelle. Signs of cost discipline and prudent capital allocation would further reinforce the upside case. Falsification would come from disappointing drill results, escalating costs without commensurate progress, or an inability to secure the financing needed to advance the project toward a construction decision.
Most Likely Trajectory: Incremental De-Risking, Ongoing Losses, and the Search for Strategic Capital
In the central scenario, Nova continues to make measured progress at Estelle, advancing exploration and technical studies while maintaining a disciplined but negative cash flow profile. The company’s liquidity, while sufficient for near-term activities, is gradually depleted as drilling, permitting, and corporate costs persist. To bridge the gap to more advanced project stages (such as a pre-feasibility study or permitting submission), Nova likely returns to the capital markets for additional equity funding, which may be moderately dilutive.
The base case is characterized by incremental resource upgrades, steady stakeholder engagement, and ongoing efforts to attract strategic partners or investors. Revenue remains absent, and the company’s valuation is driven by resource expansion potential, commodity price sentiment, and investor appetite for development-stage mining risk. This scenario would be confirmed by periodic resource updates, timely capital raises, and continued progress on technical and regulatory milestones. Unexpected permitting delays, cost overruns, or a sharp downturn in gold/copper prices would challenge this path.
Adverse Outcomes: Exploration Disappointment, Funding Gaps, and Project Stagnation
The negative scenario for Nova Minerals involves a combination of lackluster exploration results, escalating costs, and deteriorating capital market conditions. If drilling at Estelle fails to deliver compelling resource upgrades or exposes technical/geological complications, investor enthusiasm could wane. In the absence of revenue, persistent losses would erode liquidity, and the company could struggle to raise additional funds on reasonable terms—potentially forcing asset sales, project delays, or highly dilutive financings.
This scenario would be confirmed by negative or underwhelming drill results, repeated delays in technical or permitting milestones, and increasingly distressed capital raises or the entrance of predatory financing. Prolonged commodity price weakness or a shift in regulatory sentiment toward Alaskan mining could exacerbate the downside. Evidence against this scenario would include consistently positive exploration news, successful and non-dilutive capital raises, and visible project de-risking.
What Will Determine Whether Nova Minerals Creates Lasting Value?
Progress and quality of resource estimates at the Estelle Project, including size, grade, and comparison to regional benchmarks.
Updates on permitting, environmental approvals, and community stakeholder engagement—delays or opposition would be material.
Cash burn rate and runway relative to planned exploration and development activities; a useful metric would be quarterly operating cash flow if disclosed.
Frequency, pricing, and scale of future capital raises—especially the balance between equity dilution and alternative funding sources.
Evidence of third-party validation, such as strategic partnerships, joint ventures, or independent technical reports supporting project economics.
Insider transaction activity was reported in the cited source; this activity does not by itself establish insider confidence.
Commodity price trends for gold and copper, as these directly impact project economics and investor sentiment toward resource developers.
Appointment of key technical, operational, or project development personnel, which would signal readiness for the next phase of advancement.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments