
Norwood Financial: Exceptional Profitability, Community Lending, and Regional Bank Resilience Dynamics
Norwood Financial’s record Q3 2026 profitability underscores disciplined risk management and a diversified loan book, but concentrated regional exposure and commercial lending risk introduce vulnerability to local economic shifts. The next phase hinges on asset quality, margin discipline, and the ability to balance growth against geographic and credit risk.
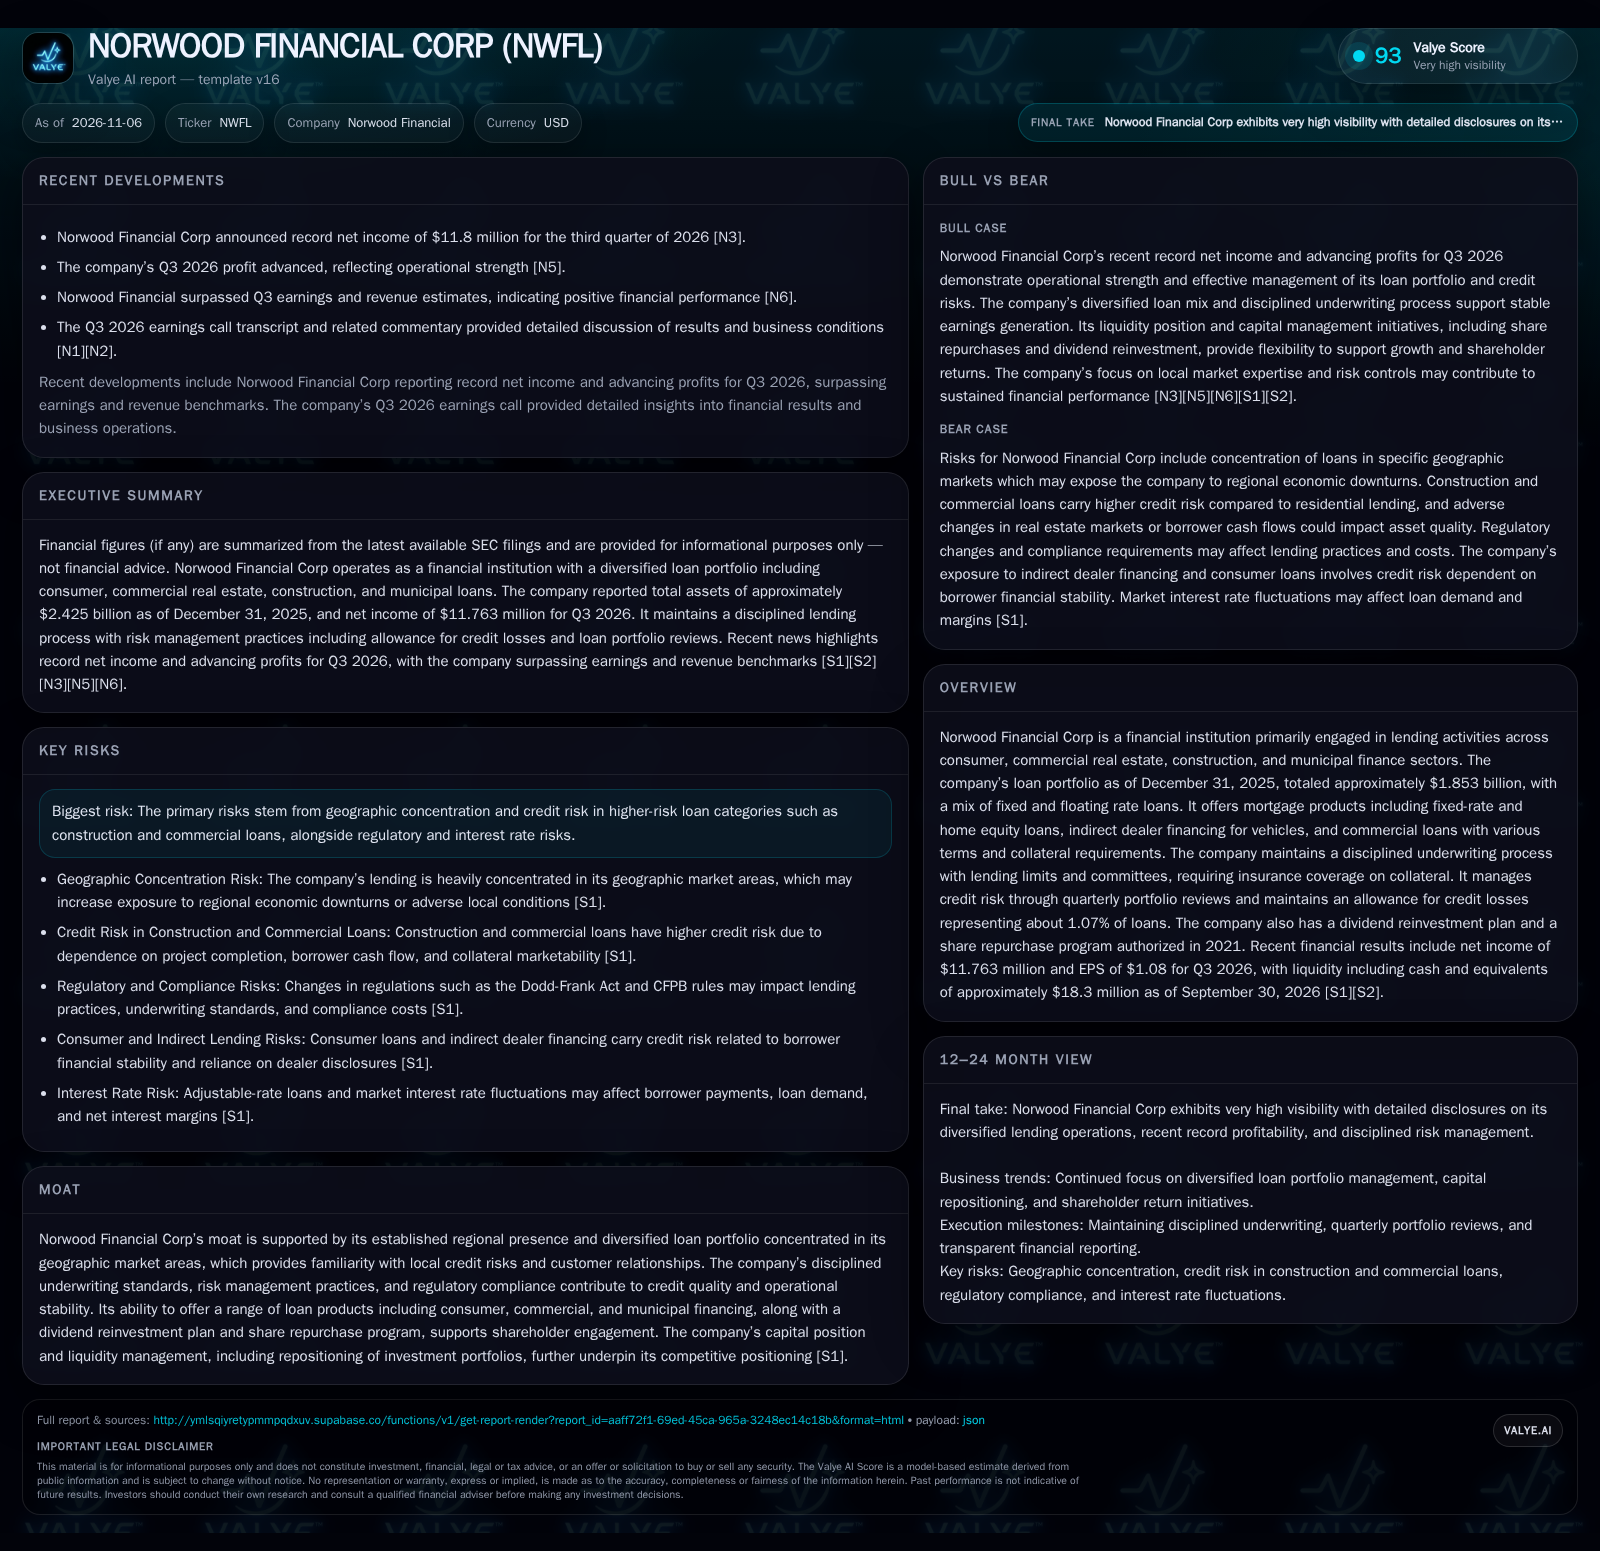
Norwood Financial reported record net income in Q3 2026, supported by a diversified lending mix and prudent underwriting. While recent profitability and asset growth highlight operational strength, the company’s geographic concentration and exposure to commercial and construction lending remain key watchpoints. The business outlook depends on maintaining credit discipline, managing interest rate and regulatory headwinds, and executing on capital allocation plans. [S1] [S2] [N3] [N5] [N6]
Norwood Financial Corp’s third-quarter 2026 results mark a high point in the company’s profitability trajectory, driven by a disciplined approach to credit risk and a diversified yet locally concentrated loan portfolio. With net income reaching a new record and asset quality metrics remaining robust, Norwood stands out among regional banks for its operational consistency. However, the bank’s focus on its core markets and exposure to higher-risk commercial and construction lending mean that its fortunes remain closely tied to local economic dynamics and broader regulatory and interest rate environments. The coming quarters will test whether Norwood can sustain its momentum while managing the inherent risks of its business model.
Norwood’s Latest Profit Milestones and Balance Sheet Composition
Norwood Financial reported record net income of $11.8 million for Q3 2026, with basic and diluted earnings per share of $1.08, surpassing both internal and external expectations. This performance was achieved on a foundation of total assets of approximately $2.425 billion and loans receivable totaling $1.853 billion as of December 31, 2025. The bank’s loan book is broadly diversified across consumer, commercial real estate, construction, and municipal finance, but remains geographically concentrated in its core market areas. Allowance for credit losses stood at $19.88 million (1.07% of total loans), with low net charge-offs (0.11% of average loans in 2025), suggesting current asset quality stability. Liquidity as of September 30, 2026, included $18.3 million in cash and equivalents. [S1] [S2] [N3] [N5] [N6]
Revenue Drivers: Loan Portfolio, Margin Trends, and Capital Deployment Strategy
Norwood’s core earnings engine is its net interest margin, driven by interest on a diversified loan portfolio and offset by funding costs (primarily deposits). The loan mix includes fixed-rate mortgages (up to 30 years), home equity loans, indirect dealer vehicle financing, commercial loans, and construction lending. Each segment carries distinct risk and yield profiles: commercial and construction loans often offer higher yields but greater credit risk, while residential mortgages contribute stability and duration. The bank’s underwriting discipline—eschewing riskier products like option ARMs and subprime loans—supports credit quality but may limit upside in risk-on cycles.
Operating leverage is modest, typical of regional banks, with a largely fixed cost base (branches, compliance, personnel) but limited scalability unless loan growth is robust. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. Shareholder returns are addressed through a dividend reinvestment plan and a share repurchase program, indicating a balanced approach to capital allocation. [S1]
Leveraging Local Expertise: Strengths and Risks in Regional Banking
Norwood’s competitive positioning is rooted in its deep familiarity with local credit risks and borrower relationships, a hallmark of successful community and regional banks. This local knowledge may improve underwriting outcomes and customer loyalty, particularly in the commercial and municipal lending segments. The bank’s diversified loan mix reduces single-sector concentration risk, and owner-occupied commercial real estate lending typically carries lower default risk compared to investor-owned properties.
However, Norwood’s geographic concentration is a double-edged sword. While it enables market intimacy, it also exposes the bank to regional economic shocks—such as a downturn in local real estate or employment. Competitor categories include other community banks, credit unions, and increasingly, digital-first lenders targeting consumer and small-business segments. Larger regional banks may also compete aggressively for commercial and municipal business, especially as technology platforms reduce the importance of physical proximity. Norwood’s disciplined risk management and product breadth are defensive strengths, but its moat is not insurmountable if local economic conditions deteriorate or if digital disruption accelerates.
Potential Gains from Sustained Asset Quality and Market Expansion
If Norwood continues to maintain low charge-offs and stable asset quality, while expanding its loan book in core and adjacent markets, the bank could compound earnings growth and deliver above-peer returns. A favorable economic backdrop in the region—supporting commercial and real estate activity—would drive higher loan demand and enable the bank to capture share from less nimble competitors. Successful execution would be evidenced by continued record or rising net income, stable or declining credit losses, and growth in loans receivable without a commensurate rise in risk metrics.
Confirmation of this scenario would come from sequential growth in loan balances, maintenance of an allowance for credit losses near or below current levels, and positive operating leverage (i.e., revenue growth outpacing expense growth). Evidence against this outcome would include a spike in nonperforming loans, rising charge-offs, or a contraction in lending due to local economic weakness.
Forecasting Steady Earnings Growth with Cautious Risk Management
The most plausible path for Norwood is continued steady profitability, with loan growth pacing local economic expansion and credit losses remaining within historical norms. Net interest margins may come under modest pressure if funding costs rise faster than asset yields, but disciplined underwriting and portfolio management should keep asset quality stable. Capital allocation is likely to remain conservative, with dividends and moderate share repurchases balanced against capital needs for loan growth and regulatory buffers.
This scenario would be confirmed by incremental growth in both loans and deposits, stable nonperforming asset ratios, and consistent quarterly profitability. A shift toward riskier lending or a pronounced pickup in construction/commercial charge-offs would challenge this outlook.
Impact of Regional Economic Shifts and Credit Cycle Volatility on Norwood
An adverse scenario would play out if the local economy enters recession, triggering rising delinquencies in commercial real estate and construction loans. Given Norwood’s geographic concentration, a regional downturn—such as a collapse in local property values or major employer closures—could quickly erode asset quality and compress net interest margins as credit losses mount. Regulatory scrutiny might intensify, and the bank could be forced to increase its allowance for credit losses, further pressuring earnings.
This scenario would be confirmed by a rapid escalation in nonperforming loans, a spike in net charge-offs, and a need to raise additional capital or curtail lending. Signs of market share loss to digital lenders or larger banks, or a sharp rise in deposit costs outpacing asset yields, would also support a more negative outlook.
Factors Shaping Norwood’s Future in the Evolving Regional Banking Sector
Quarterly trends in nonperforming loans and net charge-offs—evidence of asset quality stress or resilience.
Sequential growth or contraction in loans receivable, especially in higher-yielding commercial and construction segments.
Allowance for credit losses as a percentage of loans—whether it remains stable, rises, or falls, and how it compares to peer banks.
Deposit growth and funding cost trends, particularly in a rising or volatile interest rate environment.
Loan portfolio geographic breakdown (if disclosed)—to assess evolving concentration risk.
Net interest margin evolution as rates and competitive dynamics shift.
Shareholder return actions—actual share repurchases or dividends paid, and any changes to capital allocation policy.
Any disclosed changes in underwriting standards, risk appetite, or regulatory findings.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments