
Osprey Bitcoin Trust: Shrinking Asset Base, Nasdaq Listing, and the Stakes of Passive Crypto Exposure
OBTC’s transition to Nasdaq and a sharp contraction in assets highlight the volatility and structural trade-offs of passive Bitcoin trusts. The business’s future hinges on regulatory clarity, investor sentiment, and its ability to maintain relevance as more sophisticated Bitcoin investment vehicles proliferate.
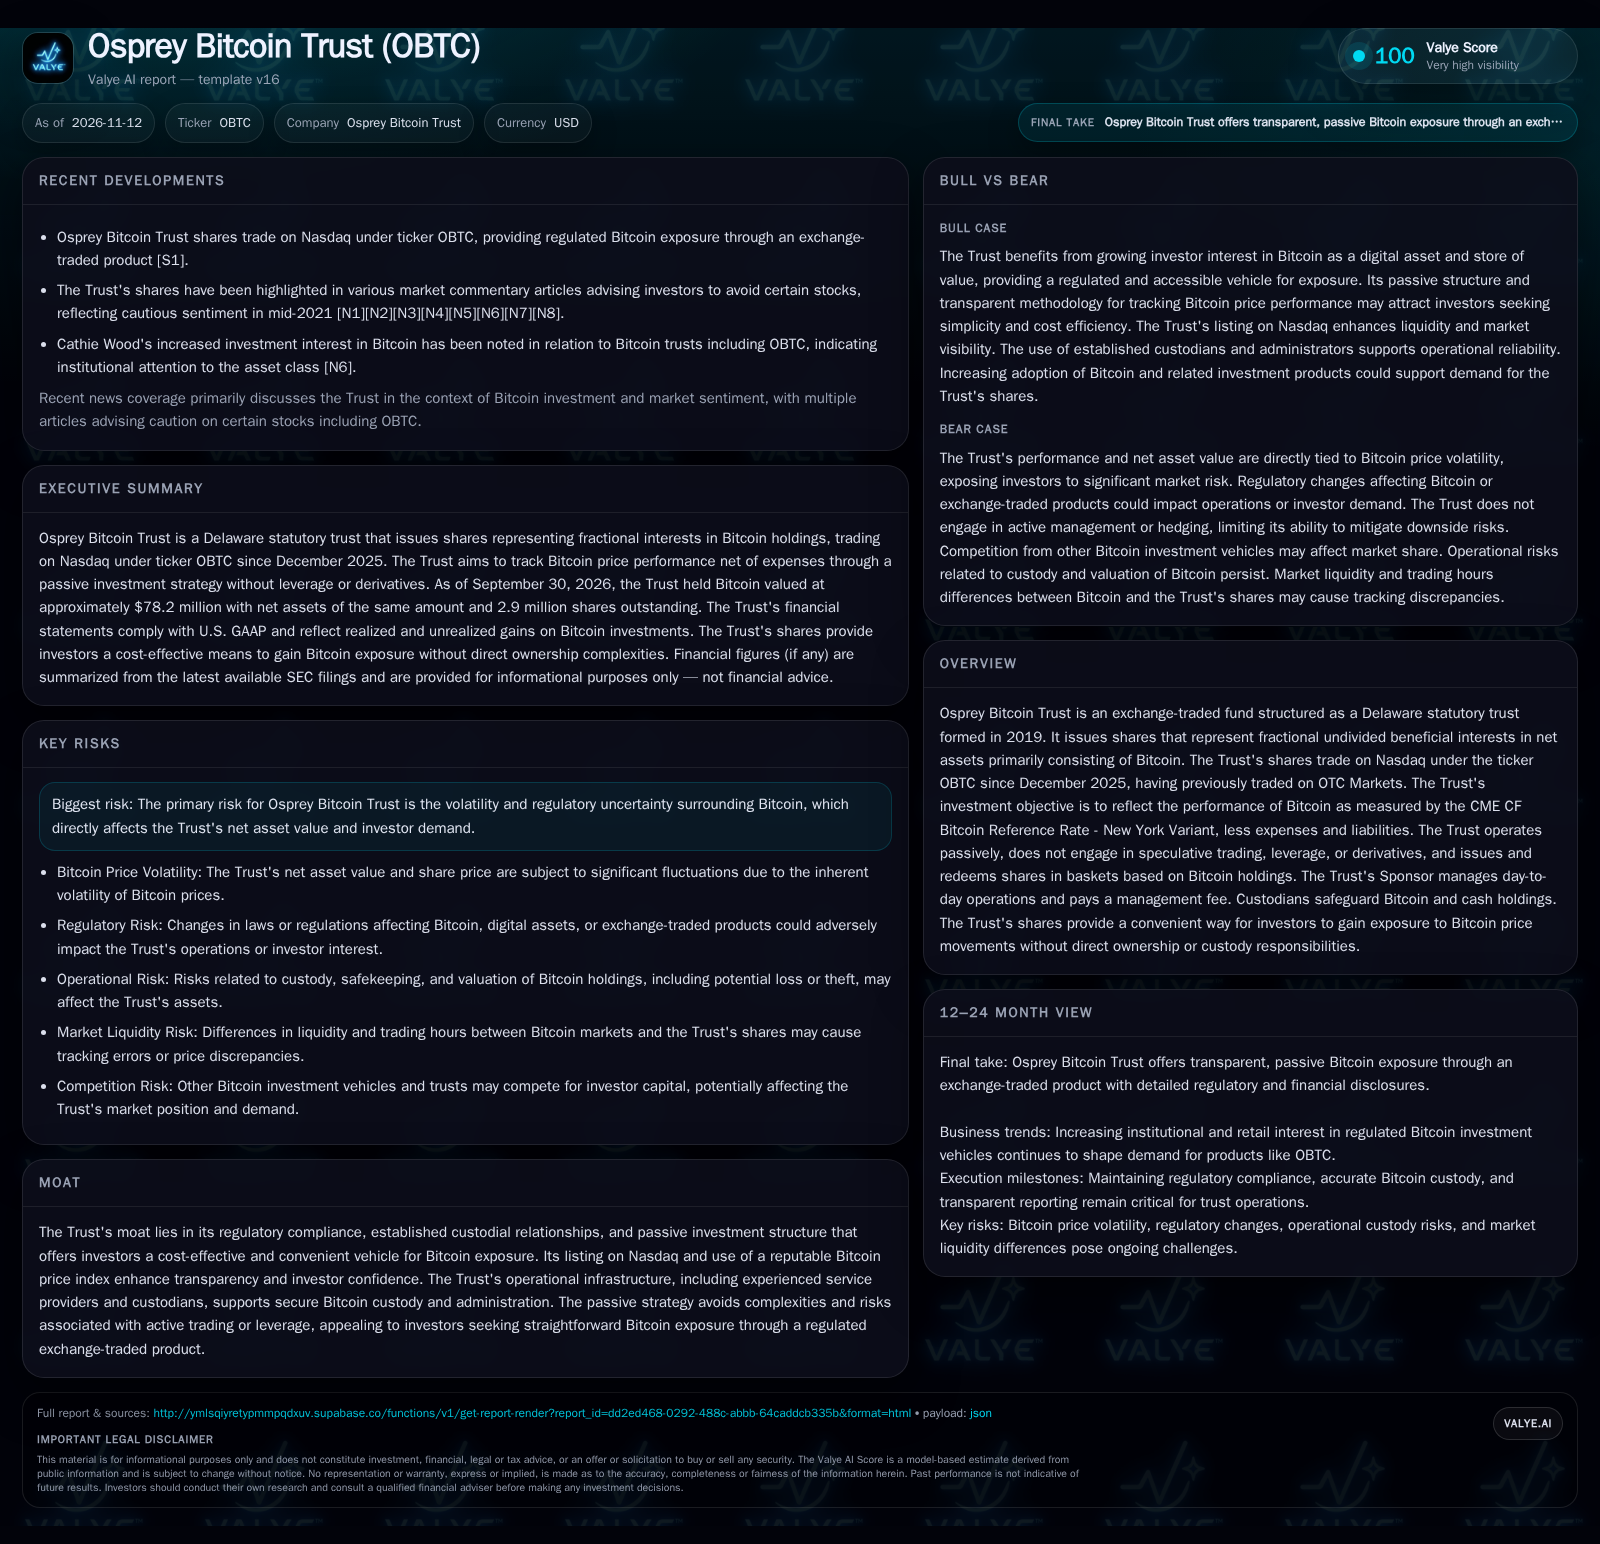
Osprey Bitcoin Trust (OBTC) now trades on Nasdaq but saw its net assets fall from $136.7M to $78.2M in 2026, driven by redemptions and Bitcoin price movement. As a passive, cost-efficient Bitcoin exposure vehicle, OBTC’s economics are tightly coupled to Bitcoin’s volatility and investor demand for regulated, easily accessible crypto products. Its future will be shaped by regulatory shifts, competitive pressure from larger and lower-fee vehicles, and ongoing market appetite for Bitcoin-linked securities. [S2]
Osprey Bitcoin Trust (OBTC) exemplifies the structural opportunities and existential challenges facing passive Bitcoin investment vehicles. The trust’s 2025 move to a Nasdaq listing aimed to boost its profile and accessibility, yet 2026 saw a dramatic contraction in both assets and outstanding shares. These developments underscore how OBTC’s fate is inextricably linked to Bitcoin’s price trajectory, investor risk appetite, and the evolving landscape of regulated crypto investment products. As competition intensifies and regulatory scrutiny persists, OBTC must defend its value proposition amid structural headwinds and shifting market sentiment.
A Year of Volatility: OBTC’s Assets Fall and Shares Contract Post-Nasdaq Listing
As of September 30, 2026, Osprey Bitcoin Trust held net assets of approximately $78.2 million, down sharply from $136.7 million at the end of 2025. The number of shares outstanding fell from 4.86 million to 2.91 million over the same period, reflecting significant redemption activity. Net asset value per share also slipped from $28.12 to $26.87. These changes coincided with OBTC’s December 2025 transition from OTC to Nasdaq trading, a move designed to improve liquidity and investor access. The Trust’s net income for the third quarter of 2026, at $23.4 million, was driven by realized and unrealized gains on its Bitcoin holdings, but the contraction in AUM and shares highlights the volatility and redemption sensitivity of the product. [S2]
How OBTC’s Passive Structure Shapes Its Revenue and Cost Dynamics
OBTC’s business model is fundamentally simple: it earns management fees based on net assets, while expenses (primarily custody, administration, and reporting) are paid out of the trust’s assets. There is no active trading, leverage, or derivatives exposure, and the trust does not seek to outperform Bitcoin but merely to track its price, net of costs. This model offers operational simplicity and cost efficiency, but also leaves OBTC highly exposed to Bitcoin’s price swings and the ebb and flow of investor demand.
The trust’s cost base is largely fixed in the short term (administration, regulatory compliance, custody), but its revenue is variable, scaling directly with assets under management (AUM). As AUM shrinks, as seen in 2026, fee income drops while some expenses remain, compressing margins. Without mechanisms to stem outflows or differentiate on service, OBTC has limited levers to manage profitability beyond maintaining scale and minimizing costs.
Redemption activity—particularly when share redemptions are settled in Bitcoin rather than cash—can exacerbate liquidity management and may force asset sales at inopportune times, although OBTC’s structure is designed to facilitate orderly in-kind redemptions. The trust’s minimal cash holdings indicate a lean operational approach, but also mean it is reliant on the smooth functioning of creation/redemption processes to handle investor flows. [S2]
Regulated Bitcoin Access: OBTC’s Advantages and the Threat of Fee Compression
OBTC’s core value proposition is straightforward: regulated, exchange-traded Bitcoin exposure without the need for direct custody or technical know-how. Its Nasdaq listing and use of reputable custodians (Coinbase Custody, U.S. Bank) enhance its credibility and market accessibility. These factors are attractive to investors seeking simplicity, transparency, and institutional-grade security in their Bitcoin exposure.
However, OBTC operates in an increasingly crowded field. Larger Bitcoin trusts and ETFs, some with lower fees, deeper liquidity, and more aggressive marketing, have eroded the first-mover advantages enjoyed by early products. The risk of fee compression is acute, as larger players can afford to lower fees to capture market share. Product innovation—such as the introduction of spot Bitcoin ETFs, options overlays, or multi-asset crypto funds—also threatens to make simple passive trusts less relevant.
Switching costs for investors are low, as products are largely interchangeable and the underlying asset is undifferentiated. OBTC’s ability to maintain or grow AUM will depend on its cost structure, operational reliability, and the overall market’s demand for passive, regulated Bitcoin vehicles.
Renewed Bitcoin Bull Market and Regulatory Stability Could Revitalize OBTC
A sustained rally in Bitcoin prices, coupled with renewed retail and institutional inflows into regulated crypto products, could drive a resurgence in OBTC’s net assets and fee income. Regulatory clarity—such as SEC approval of additional spot Bitcoin ETFs, or clear guidance on crypto taxation and custody—may boost investor confidence and increase the addressable market for regulated Bitcoin vehicles.
OBTC could benefit if investors seek out cost-efficient, passive exposure vehicles as a hedge or portfolio diversifier, especially if its fee structure remains competitive relative to peers. Continued operational reliability (no major custody or reporting failures) and successful navigation of compliance hurdles would further support investor trust.
Evidence for this scenario would include a reversal in share redemptions, growth in outstanding shares and AUM, and narrowing discounts (or premiums) to NAV. Rising trading volumes and positive net inflows would also confirm renewed demand.
Incremental Asset Flows and Persistent Fee Pressure Define the Likely Trajectory
The most plausible path for OBTC is one of moderate asset base fluctuations, closely tracking Bitcoin’s price and broader investor sentiment toward crypto. In this scenario, OBTC maintains a niche role among passive Bitcoin exposure vehicles but faces ongoing fee compression and competitive churn as larger, lower-fee ETFs and trusts vie for the same investor dollars.
Operational reliability remains a requirement, not a differentiator. Investors may continue to redeem shares during Bitcoin downturns or shift to more liquid or cost-effective alternatives as they become available. OBTC’s economics will remain tightly coupled to Bitcoin’s volatility and the sector’s regulatory environment.
Confirmation would come from relatively stable (but not growing) AUM, modest fluctuations in shares outstanding, and management fees that track sector norms. Persistent discounts to NAV and periodic redemptions would signal the product’s ongoing but undifferentiated relevance.
Prolonged Crypto Bear Market and Market Share Loss Threaten OBTC’s Viability
A prolonged decline in Bitcoin prices, coupled with continued outflows and intensifying competition from larger, lower-fee or more innovative products, could erode OBTC’s asset base to the point where fixed costs become unsustainable. Regulatory setbacks—such as stricter rules on digital asset trusts or unfavorable tax treatment—could further impair demand.
In this scenario, persistent redemptions shrink AUM, compressing fee income while expenses remain, potentially leading to negative operating leverage. If OBTC is unable to differentiate or lower its fee structure, it risks a downward spiral of outflows and irrelevance, especially as switching costs for investors are minimal.
Evidence supporting this outcome would include ongoing declines in assets and shares outstanding, widening discounts to NAV, fee reductions under pressure, and possible operational strain (such as delayed redemptions or reporting errors).
Milestones and External Catalysts That Will Shape OBTC’s Business Outcome
Quarterly changes in assets under management (AUM) and number of shares outstanding: Persistent declines or sudden inflows will be the clearest signals of investor sentiment and business health. [S2]
NAV discount or premium relative to underlying Bitcoin: A persistent discount may indicate weak demand or structural product issues; a narrowing spread could signal improved sentiment or competitive positioning.
Fee structure relative to peer trusts and ETFs: Any announced fee reductions or changes in expense ratios would indicate competitive pressure and margin outlook.
Trading volume and liquidity metrics on Nasdaq: Sustained low volumes may undermine the trust’s value proposition as a liquid, accessible Bitcoin exposure vehicle.
Regulatory developments affecting Bitcoin trusts or ETFs: New SEC guidance or approval of competing products could alter the competitive landscape materially.
Operational reliability: Any disclosure of custody, valuation, or reporting issues would be a red flag for investor confidence.
Market share trends versus larger or lower-fee Bitcoin products: If disclosed, shifts in OBTC’s share of total assets in the Bitcoin trust/ETF segment would help test its competitive resilience.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments