
PDF Solutions: Hybrid Revenue Model and Strategic Acquisitions Shape Semiconductor Growth
PDF Solutions’ blend of recurring SaaS, license, and hardware revenues positions it as a specialized player in semiconductor yield enhancement, but customer concentration and industry cyclicality present persistent risks.
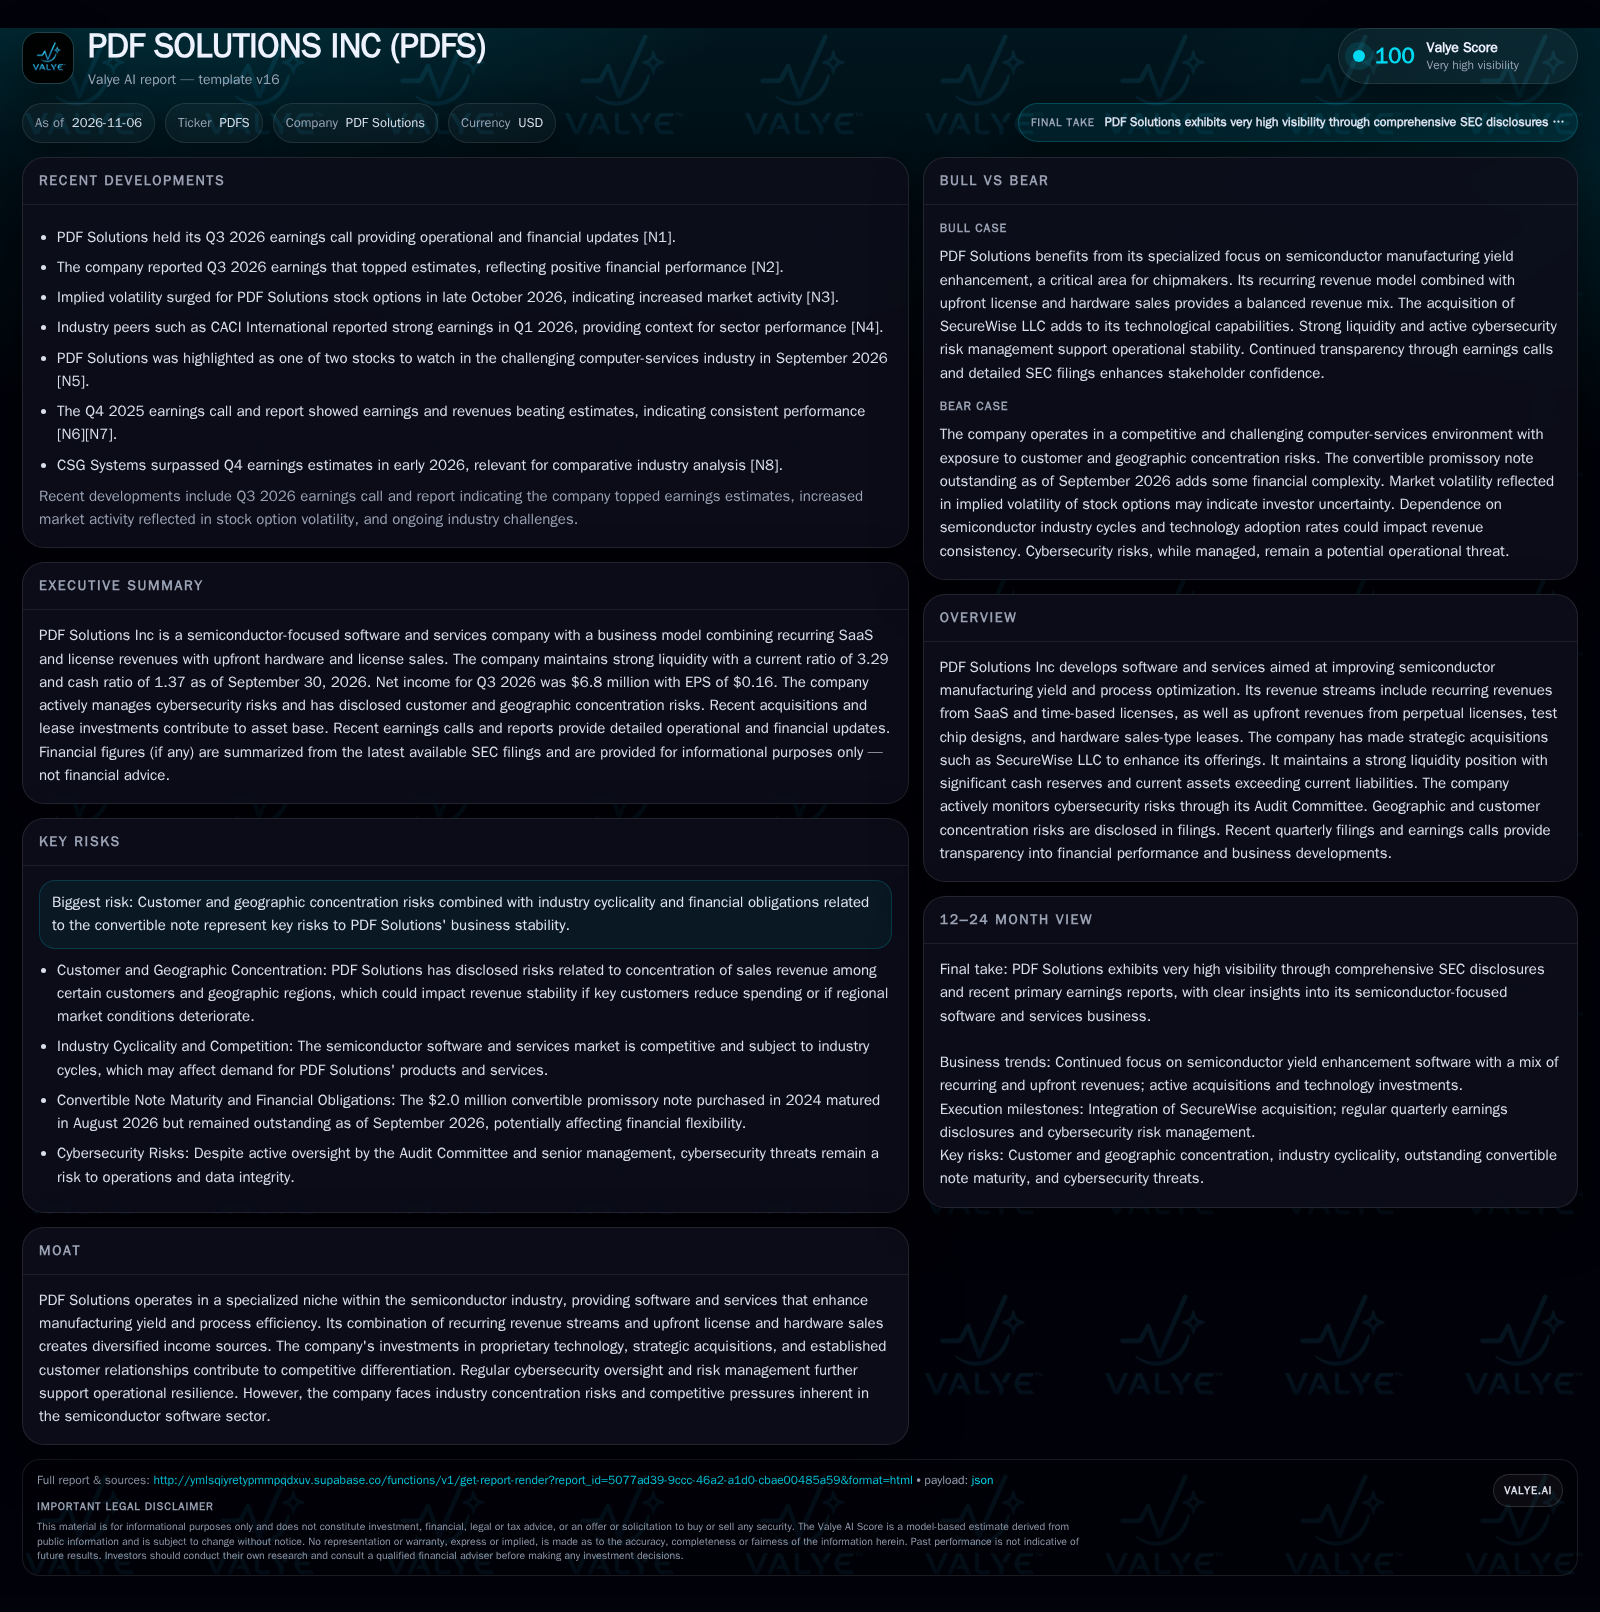
PDF Solutions reported Q3 2026 net income of $6.8 million and maintains a reported liquidity position with $107.1 million in cash. Its revenue streams span recurring SaaS and license fees plus upfront hardware and perpetual licenses, reflecting a hybrid business model. The SecureWise acquisition expands its technology base. However, customer and geographic concentration, plus industry cyclicality, are ongoing headwinds. Recent earnings have outperformed estimates, but volatility in the company’s options signals market uncertainty. [S2] [N1] [N2] [N3]
PDF Solutions occupies a specialized niche in semiconductor manufacturing—providing yield enhancement and process optimization technology to chipmakers globally. Its financials as of Q3 2026 reflect stable profitability and reported liquidity position, while the company’s hybrid revenue structure blends predictable SaaS streams with less predictable, but potentially high-margin, upfront hardware and license sales. Recent strategic moves, including the SecureWise acquisition, have broadened its technological scope. Yet, meaningful risks remain, particularly tied to customer concentration and the inherent cyclicality of the semiconductor industry. As the sector faces ongoing supply chain, technology, and macroeconomic headwinds, PDF Solutions’ ability to manage these risks while leveraging its differentiated offerings will be central to its future trajectory. [S2] [N1] [N2] [N3]
Recent Financial Performance and Strategic Moves Define PDF Solutions’ Position
As of September 30, 2026, PDF Solutions reported $6.8 million in net income for Q3 and maintained a cash balance of $107.1 million, with a current ratio of 3.29 and a cash ratio of 1.37—signaling a reported liquidity position [S2] [N1] [N2]. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. The March 2025 acquisition of SecureWise LLC added intangible assets and broadened the company’s technological capabilities [S2]. Recent quarterly earnings have exceeded analyst estimates, reflecting operational momentum, while surging implied volatility in late October 2026 suggests the market is increasingly uncertain about the company’s near-term prospects [N3]. Customer and geographic concentration risks remain disclosed, highlighting potential vulnerabilities if major clients or regions reduce spending [S2].
How PDF Solutions Monetizes Semiconductor Process Optimization
PDF Solutions operates a hybrid revenue model: recurring revenues are generated from SaaS subscriptions and time-based licenses, while upfront revenues come from perpetual software licenses, test chip design, and hardware sales-type leases [S2]. This model provides a measure of revenue predictability through ongoing contracts, but significant portions of sales—particularly hardware and perpetual licenses—are inherently more volatile. The recurring elements can provide higher gross margins and greater visibility, but the upfront segment may drive outsized profits in strong demand cycles.
Fixed costs likely include ongoing R&D, platform maintenance, and customer support, while variable costs are tied to hardware fulfillment, onboarding new clients, and direct project work. Operating leverage can materialize as software and SaaS revenue scales, but hardware and services may dilute margins if not managed carefully. [S2] The $2.0 million convertible promissory note purchased in 2024, still outstanding as of September 2026, introduces some financial complexity and could affect flexibility if not resolved [S2].
Specialization in Yield Enhancement Amidst Intense Industry Competition
PDF Solutions competes in a crowded landscape of semiconductor software and service providers, including large EDA (Electronic Design Automation) vendors and niche process optimization specialists. Its differentiation stems from a focus on yield enhancement and process optimization—mission-critical pain points for semiconductor manufacturers as process nodes shrink and defect tolerances tighten.
The company’s ability to combine SaaS-based analytics, proprietary test chip designs, and hardware-driven insights creates a multi-pronged value proposition. However, switching costs for customers may be modest if rival platforms offer similar integration and analytics capabilities. The acquisition of SecureWise is likely aimed at strengthening differentiation through expanded technology and service offerings, but the ultimate moat depends on how deeply PDF Solutions’ solutions are embedded in customer workflows and whether its data-driven insights materially outperform those of competitors.
Industry cyclicality and customer concentration remain counterforces: major chipmakers may have bargaining power, and the entrance of new technologies (such as AI-driven process control) could alter the competitive landscape. The company’s disclosed geographic concentration also exposes it to regional regulatory, economic, and supply chain shocks [S2].
Leveraging Recurring Revenue and Acquisitions to Deepen Customer Integration
A favorable scenario for PDF Solutions involves growing penetration of its SaaS and time-based license offerings, increasing the proportion of high-margin, recurring revenue in its mix. If the company successfully cross-sells SecureWise’s capabilities, embeds its analytics deeper into customer manufacturing processes, and demonstrates sustained revenue growth from existing and new chipmaker clients, operating leverage could expand margins and stabilize cash flows.
Confirmation of this scenario would include sequential increases in recurring revenue as a percentage of total sales (if disclosed), evidence of multi-year contract wins or renewals, and customer adoption of new technology modules stemming from recent acquisitions. Additional signs would be stable or expanding gross margins, and a decline in customer concentration as new clients are onboarded. Accelerating R&D output or new product launches—particularly those integrating SecureWise technology—would further validate the company’s ability to innovate and defend its niche.
Balancing Predictable SaaS Revenue with Cyclical Hardware and License Sales
The most plausible trajectory is continued growth in recurring SaaS and license income, offset by fluctuations in hardware and perpetual license sales tied to semiconductor capital spending cycles. PDF Solutions is likely to maintain profitability and a reported liquidity position, while incremental contributions from SecureWise and other technology investments provide modest top-line growth and product differentiation.
Supporting evidence would be stable or gradually increasing net income and cash position, with periodic earnings beats driven by strong execution in SaaS and services [N1] [N2] [S2]. However, customer and geographic concentration is likely to persist, and the business will remain exposed to the cyclicality of semiconductor manufacturing investments. If recurring revenue grows only incrementally and customer concentration metrics do not improve meaningfully, the company may be unable to fully escape industry volatility.
Exposure to Customer Concentration and Semiconductor Downturns
The principal risk is that one or more major customers reduce or delay spending, or that a downturn in semiconductor capex leads to a sharp drop in upfront license and hardware revenues. If PDF Solutions is unable to offset this with new client wins or expansion of recurring contracts, revenue and profitability could decline rapidly. Persistent customer concentration or a reversal in SaaS adoption would amplify this effect.
Downside confirmation would come from declining total revenue, shrinking net income, or a material drawdown in cash reserves without corresponding investments in growth. An uptick in customer churn, loss of major contracts (if disclosed), or a material cybersecurity incident disrupting operations would also validate the bear case. Unresolved financial obligations—such as the outstanding convertible note—could further constrain flexibility if the company faces cash flow stress.
Milestones and Metrics That Will Shape PDF Solutions’ Competitive Trajectory
Recurring revenue as a proportion of total revenue—if disclosed—would clarify the predictability and quality of the company’s income stream.
Trends in customer concentration: the share of revenue from the top one or five customers, and any new major client wins or losses.
Gross margin evolution, particularly as SaaS and software revenue grows versus hardware and perpetual license sales.
Integration progress and revenue contribution from SecureWise and any future acquisitions.
Updates on the status and resolution of the $2.0 million convertible promissory note and any new financing obligations.
Customer churn, renewal rates, and multi-year contract signings—would help test the stickiness of the platform.
Geographic revenue breakdown and exposure to macro/regional disruptions in key semiconductor markets.
Material cybersecurity incidents or disclosures, given the company’s stated focus on risk oversight.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments