
Protalix BioTherapeutics: Profitability Inflection, Partnership Leverage, and the Realities of Biotech Commercialization
Protalix BioTherapeutics has shifted from losses to notable net income in 2026, driven by increased revenues and contributions from key partnerships. The central question is whether this inflection is sustainable amid clinical, regulatory, and partnership dependencies that define the economics and risks of biotech commercialization.
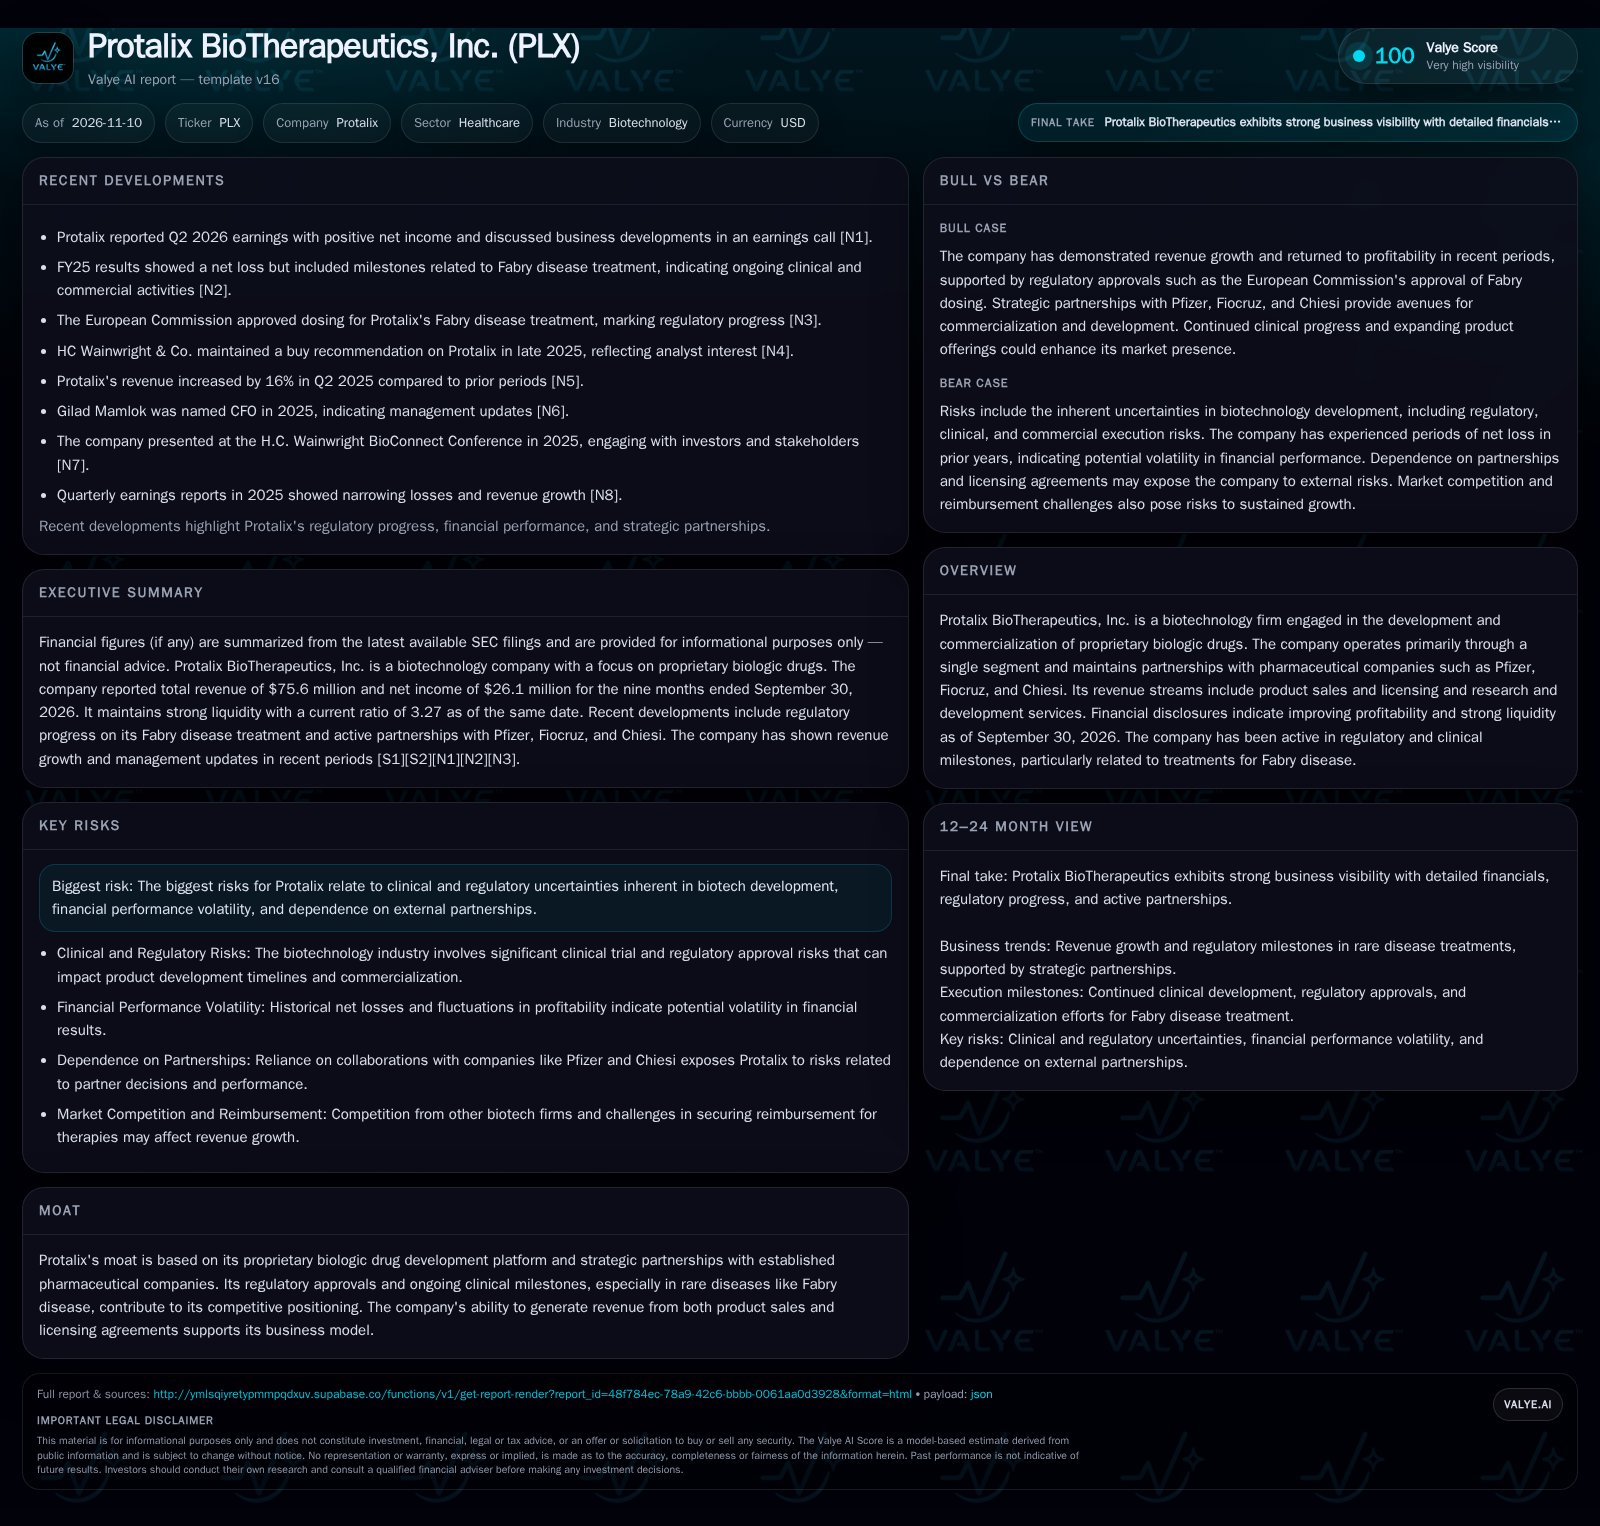
Protalix reported a sharp move to profitability in 2026, with $75.6 million in revenue and $26.1 million in net income for the first nine months. The company’s business model blends product sales and licensing/R&D deals, underpinned by major partnerships with Pfizer, Fiocruz, and Chiesi. Sustaining this trajectory depends on continued clinical progress, commercialization execution, and the reliability of external collaborators in a competitive, risk-prone biotech landscape. [S2]
Protalix BioTherapeutics has delivered a sharp financial turnaround in 2026, reporting robust revenue growth and a swing to net profitability after years of operating in the red. This performance, anchored by both product sales and licensing revenues through alliances with pharmaceutical majors, signals a potential inflection point. Yet, the company’s future trajectory hinges on the durability of its clinical pipeline, the reliability of its external partners, and its ability to manage the inherent volatility of biotech commercialization. Understanding these dynamics is crucial for assessing whether Protalix’s recent success marks the start of sustained value creation or merely a cyclical peak.
From Losses to Profits: Protalix’s 2026 Financial Inflection
Protalix reported $75.6 million in total revenue and $26.1 million in net income for the nine months ended September 30, 2026, a marked improvement from a $1.1 million net loss in the prior-year period. This shift to profitability is a material development, reflecting both top-line growth and operational leverage. The company’s basic earnings per share reached $0.33 in the same period, underscoring the scale of the turnaround. These results are underpinned by revenues from product sales and licensing/R&D agreements, as well as active collaborations with Pfizer, Fiocruz, and Chiesi. However, the sustainability of this profit inflection remains uncertain given the company’s historical financial volatility and the event-driven nature of biotech revenues. [S2]
The shift from net losses to profitability in biotech often signals a critical juncture but also introduces new strategic challenges. For Protalix, sustaining profitability requires not only maintaining revenue growth but also managing the timing and scale of R&D expenditures, which can be lumpy and unpredictable. The company’s ability to balance reinvestment in pipeline development with operational efficiency will be crucial. Moreover, profitability inflection points in biotech are frequently influenced by milestone recognition and partner payments, which can create episodic revenue spikes rather than steady income streams. Hence, a nuanced understanding of revenue quality and expense dynamics is essential to assess the durability of this financial transition.
How Protalix’s Model Converts Science into Revenue Streams
Protalix generates revenue through a hybrid model combining direct product sales with licensing and R&D service agreements. This structure allows the company to monetize both its proprietary biologic assets and its development expertise. Product sales likely offer higher gross margins, especially as scale grows and manufacturing costs are amortized. Licensing and R&D revenues provide upfront or milestone payments and may include royalties, which can smooth cash flows but are contingent on partner execution and regulatory success.
The company’s operating leverage is evident in its 2026 numbers: a sharp increase in revenue has translated into net profitability, suggesting that a significant portion of costs are fixed or semi-fixed. However, the capital intensity of biotech R&D means that Protalix’s profitability could be vulnerable to setbacks in clinical programs or the need for further investments. The modest $22 million cash balance underscores the ongoing need for prudent capital allocation, particularly if new trials or commercial launches are required. If product sales become a larger share of revenue over time, gross margins and earnings could improve further, but this is contingent on both market uptake and manufacturing scalability.
The hybrid revenue model employed by Protalix reflects a strategic attempt to diversify income sources and mitigate the inherent risks of biotech development. Licensing and R&D agreements can provide upfront capital and milestone payments that ease cash flow pressures, but these are often contingent on partner performance and regulatory milestones outside the company’s direct control. Conversely, product sales offer more predictable revenue streams but require successful market penetration and manufacturing scalability. The interplay between these revenue types means that shifts in one segment can disproportionately affect overall financial performance. For example, a delay in regulatory approval could stall royalty income, while manufacturing bottlenecks could constrain product sales growth, underscoring the importance of operational agility.
Operational leverage in biotech is inherently asymmetrical; fixed costs related to R&D and manufacturing infrastructure create a cost base that can amplify earnings as revenues grow, but also magnify losses if revenue targets are missed. Protalix’s reported profitability suggests it has reached a revenue threshold where fixed costs are effectively absorbed, but this equilibrium is delicate. Any requirement for expanded clinical trials or commercial scale-up could increase expenses materially. Therefore, the company’s future earnings trajectory will depend on its capacity to manage incremental costs relative to incremental revenues, and on its ability to secure additional capital if needed without excessive dilution or financial strain.
Partnership Leverage and the Realities of Biotech Competition
Protalix’s most distinctive strength is its network of partnerships with established pharmaceutical companies, notably Pfizer, Fiocruz, and Chiesi. These relationships provide access to broader commercialization capabilities, regulatory expertise, and global distribution channels—critical advantages for a relatively small biotech. However, this leverage comes with dependency risks: changes in partner priorities, commercial execution, or regulatory setbacks could disrupt revenue flows.
The biologics market is highly competitive, with rivals ranging from other small innovators to major pharma incumbents. Protalix’s moat relies on its proprietary drug development platform and the ability to address niche indications, such as Fabry disease. Yet, barriers to entry in biotech are often eroded by scientific advances, competing therapies, or shifts in reimbursement. The company’s future position will depend on demonstrating clear clinical benefit, operational execution, and the capacity to secure and retain advantageous partnership terms.
What a Sustained Commercial Ramp Could Look Like for Protalix
If Protalix maintains positive clinical momentum—particularly in Fabry disease—and commercial execution remains strong through its partners, the company could see a virtuous cycle of expanding sales, milestone payments, and growing royalties. This would likely lead to further margin expansion as fixed costs are leveraged, and could support new pipeline investments without the need for dilutive financing.
Evidence supporting this scenario would include: continued revenue growth from product sales (especially in key indications), additional regulatory approvals or expanded labels, new or expanded partnership announcements, and increasing contributions from royalties or sales-based milestones.
Operational Realism: Navigating Volatility and External Dependencies
The most plausible scenario is that Protalix experiences ongoing revenue and earnings volatility typical of mid-stage biotechs. While partnerships provide commercial leverage, revenue streams may fluctuate based on partner performance, regulatory events, and market uptake. The company could achieve intermittent profitability, punctuated by periods of re-investment or clinical setbacks.
Confirmation would come from quarterly results showing stable or slightly rising revenues, modest profitability, and continued R&D spend matched by milestone inflows. Falsification would involve a return to sustained losses, declining partner engagement, or major clinical/regulatory disappointments. The company’s ability to manage its modest cash resources without recurring equity raises will also be a key test of operational discipline.
How Clinical or Partnership Setbacks Could Reverse Recent Gains
Protalix is exposed to downside risk if key clinical programs encounter setbacks or if major partners reduce their commitment. A failed or delayed trial in a lead indication, negative regulatory outcomes, or the termination of a major licensing agreement could result in a sharp decline in revenues and a return to net losses. Given the company’s reported cash balance, such shocks could force cost-cutting, delay pipeline progress, or necessitate dilutive capital raises.
Downside confirmation would include a significant drop in quarterly revenue, the announcement of clinical/regulatory failures, or disclosures of partner withdrawal or renegotiation.
Milestones That Will Shape Protalix’s Value Trajectory
Quarterly revenue growth from both product sales and licensing/R&D agreements, with particular focus on the contribution mix between recurring and milestone-based income. [S2]
Updates on the progress and outcomes of Fabry disease clinical/commercial programs, including regulatory approvals or expanded label indications. [N2] [N3]
Announcements of new or expanded partnerships—especially with larger pharma players—or any changes in the status of existing collaborations. [S1] [S2]
Sustained net profitability and positive operating cash flow across multiple quarters, rather than single-period inflections. [S2]
Disclosures regarding manufacturing scalability, supply chain reliability, or gross margin impacts as product sales scale (if disclosed).
Regulatory developments or changes in reimbursement landscape affecting core indications and partner markets.
Management turnover or strategic shifts, particularly in business development or R&D leadership, as these could impact partner relations and pipeline execution.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments