
Precipio’s Operational Realignment: Cash Flow Gains, Dilution Measures, and the Profitability Hurdle
Precipio, Inc. has demonstrated revenue momentum and improved cash flow amid persistent net losses and active measures to address share dilution. The company's focus on performance-based incentives and investor transparency provides a foundation for operational improvement, but uncertainties around its sector, scalable economics, and competitive positioning remain key variables for future performance.
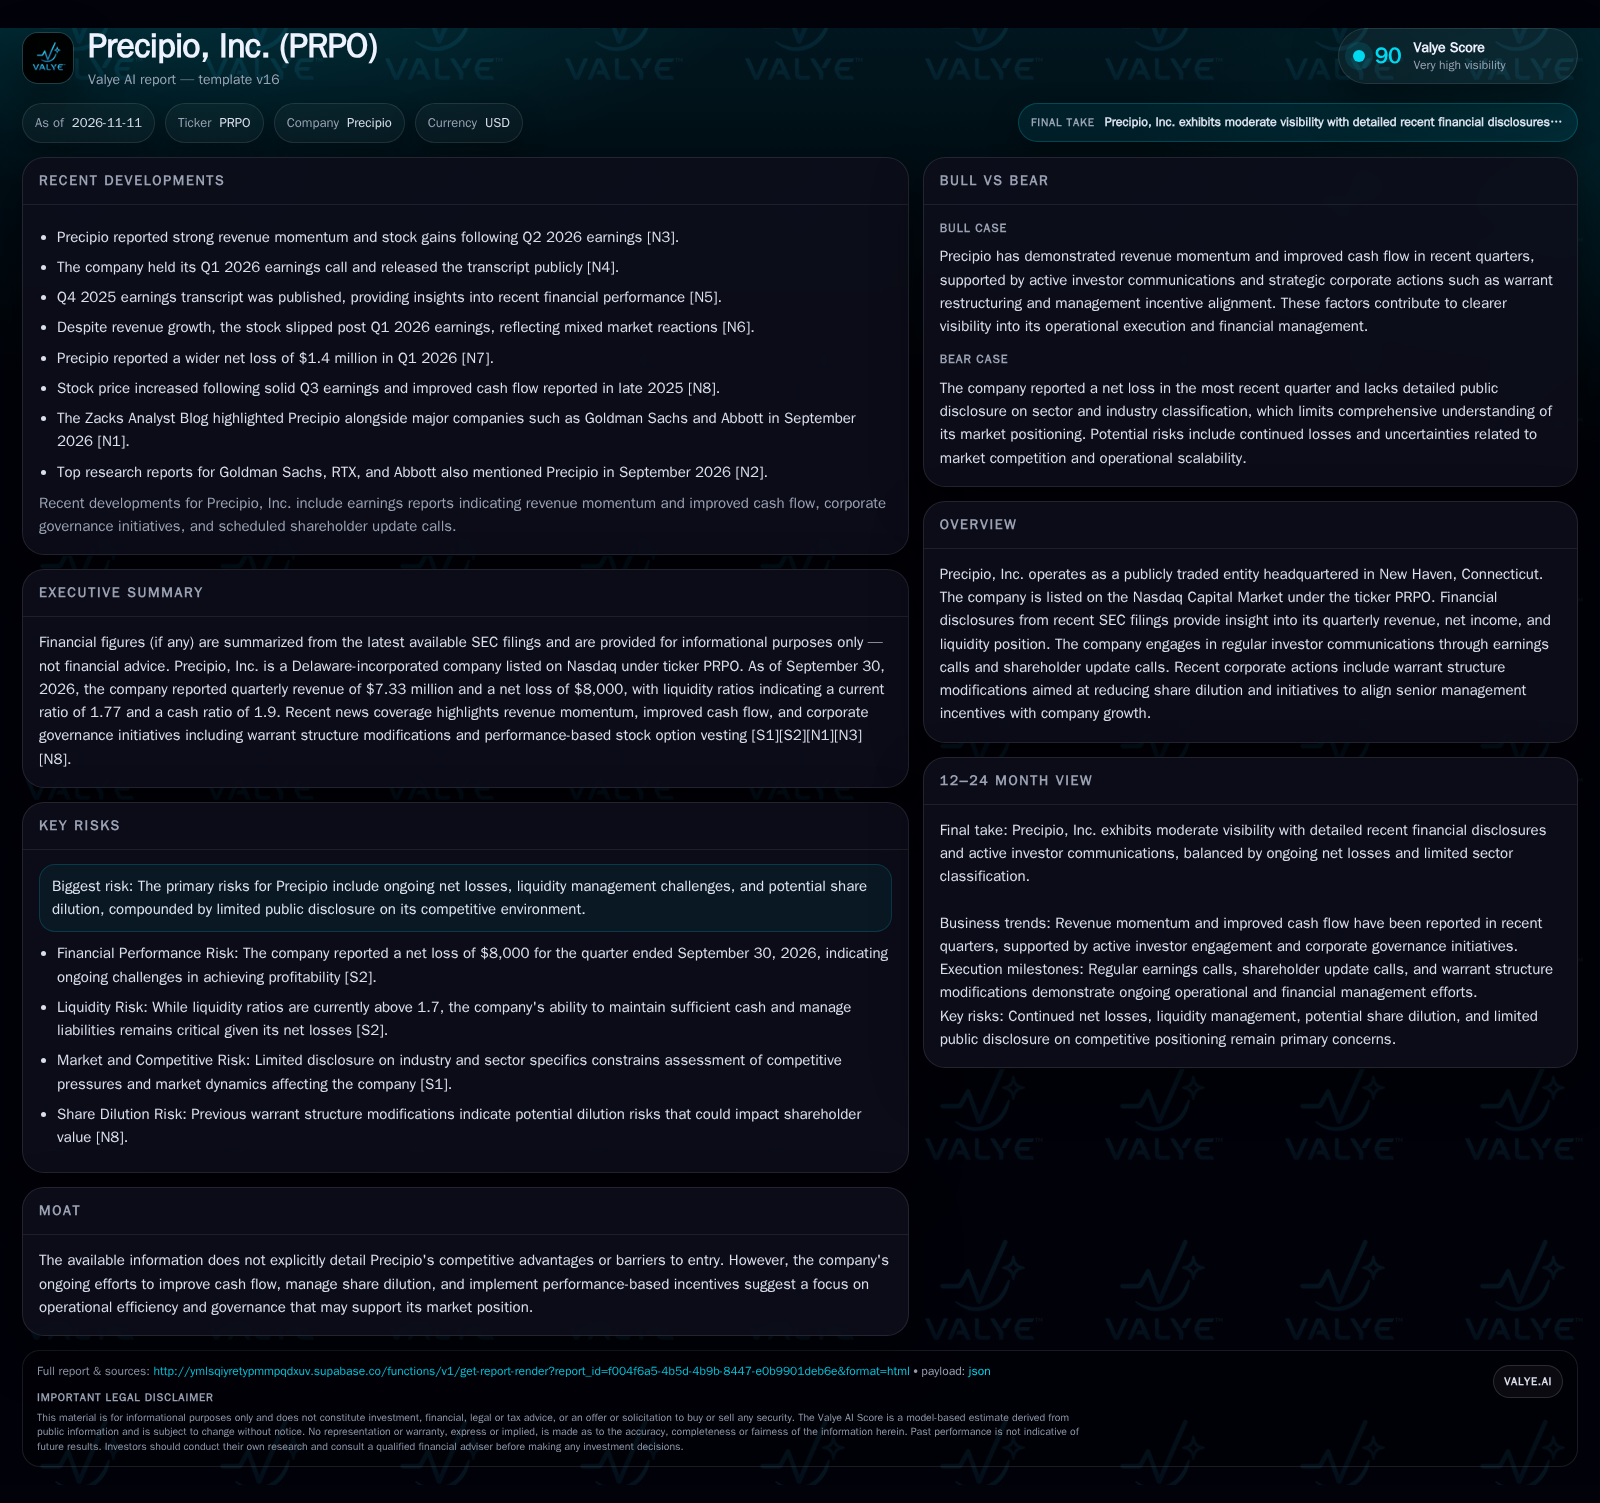
Precipio reported $7.33 million in Q3 2026 revenue and a near-breakeven net loss, signaling progress on cash flow and operational discipline. Recent actions to modify warrants and tie executive compensation to performance are designed to balance growth with shareholder value. However, continued net losses and limited public disclosure on its core market challenge the durability of its momentum and raise questions about long-term competitive differentiation. [S2] [N3] [N8]
Precipio, Inc. stands at a crossroad where recent operational improvements and active capital management collide with persistent net losses and a murky competitive landscape. The company’s latest quarter shows revenue growth and a near-breakeven net loss, paired with deliberate steps to limit dilution and incentivize management. Yet, absent disclosure on its core sector or peer set, the question remains whether these governance and financial maneuvers can translate into sustainable profitability and market relevance. As Precipio pursues improved cash flow and tighter alignment between executive performance and shareholder outcomes, investors are left weighing the durability of recent momentum against fundamental questions of scale and differentiation.
Recent Financial Performance and Governance Actions Take Center Stage
Precipio, Inc. reported $7.33 million in revenue for Q3 2026, with a net loss of just $8,000—an improvement over prior periods that saw significantly wider losses. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. Notably, Precipio has enacted changes to its warrant structure to reduce dilution risk and has introduced performance-based vesting for senior management stock options. These steps are designed to better align executive incentives with company performance and shareholder interests. The company continues to maintain active investor communication channels through regular earnings calls and updates. [S2] [N3] [N8]
How Precipio’s Financial Structure Could Shape Its Path to Profitability
Precipio’s recent revenue growth and near-breakeven net loss suggest incremental progress on cost management and operational efficiency. The relatively modest scale of revenue, however, raises questions about the company’s ability to achieve meaningful operating leverage. If Precipio’s business model relies on high fixed costs—such as laboratory infrastructure, specialized personnel, or proprietary technology platforms—scaling revenue could eventually drive margin expansion. On the other hand, if variable costs scale linearly with revenue, gross margin improvement may be elusive. The company’s history of net losses indicates that fixed costs or underutilized capacity may still be a drag on profitability.
The introduction of performance-based vesting for management stock options may help align leadership focus with key financial milestones, such as sustained revenue growth or EBITDA breakeven. Modifications to warrant structures to reduce dilution also suggest an effort to preserve shareholder value, but these moves alone do not alter the underlying economics. Capital needs are likely to persist unless the company can consistently generate positive cash flow, and the absence of explicit information about business segments or product mix limits visibility into where margin improvement could materialize.
Competitive Landscape: Assessing Precipio’s Position Without Industry Clarity
The lack of detailed public disclosure on Precipio’s sector and industry makes it difficult to assess its competitive environment or to benchmark its performance against direct peers. If Precipio operates in a diagnostics or laboratory services niche—as its headquarters and business model might suggest—it would face competition from both established industry incumbents and emerging technology-driven entrants. Key differentiators in such markets typically include proprietary technology, test menu breadth, turnaround time, payer relationships, and regulatory compliance.
Without explicit evidence of unique intellectual property, switching frictions, or network effects, Precipio’s ability to command premium pricing or retain customers could be limited. The company’s efforts to improve governance and reduce dilution are positive but may not, on their own, create a durable moat. The challenge is compounded by the risk of commoditization and price competition in clinical laboratory or diagnostics markets, where scale and automation often drive cost advantages.
Unlocking Margin Expansion Through Scale and Operational Discipline
In a favorable scenario, Precipio’s recent revenue momentum continues, enabling the company to leverage its fixed cost base and transition to sustained profitability. If the performance-based vesting mechanisms successfully incentivize management to drive both top-line growth and cost efficiency, incremental revenue could fall more directly to the bottom line. Reduction in dilution risk—through modified warrants—could help maintain per-share value as the company grows.
Confirmation of this scenario would include several quarters of sequential revenue growth, improving gross and operating margins, and consistent positive operating cash flow. Evidence of customer concentration reduction, expanded test menus (if disclosed), or new commercial contracts could further support the case for scale-driven margin expansion. Falsification would occur if revenue growth stalls, gross margins compress, or operating expenses scale in step with revenue, negating leverage.
Incremental Progress Amid Unresolved Profitability and Visibility Gaps
The most plausible outcome over the next 12-24 months is that Precipio achieves gradual revenue growth and continues to manage costs, but remains near breakeven or posts modest net losses. The company’s balance sheet is likely to remain stable in the absence of major shocks, although occasional capital raises or further dilution cannot be ruled out if cash burn persists. Governance enhancements and investor communications may help maintain market confidence, but without clear disclosure on business mix or sector dynamics, durable competitive advantage remains uncertain.
This scenario would be confirmed by continued positive working capital, regular investor updates, and incremental improvements in cash flow, but persistent ambiguity around core markets and margin structure. A material change in either direction—such as a significant contract win or a major competitive setback—would shift the base case toward one of the alternative scenarios.
Profitability Delays and Dilution Risks Could Undercut Recent Gains
If revenue growth slows or reverses and operating costs remain high, Precipio could return to more substantial net losses, quickly eroding its reported liquidity position cushion. In such a scenario, the company might be forced to seek additional capital through dilutive equity offerings or less favorable financing terms, despite prior efforts to control dilution. The absence of a clearly articulated competitive edge or differentiated product offering could compound these risks, especially if the company operates in a commoditized or rapidly evolving market.
This downside would be confirmed by widening quarterly losses, declining cash balances, and announcements of new equity raises or adverse changes to capital structure. Additional warning signs include management turnover, reduced investor communications, or loss of key customer relationships (if disclosed).
Milestones and Metrics That Will Define Precipio’s Next Chapter
Quarterly revenue growth rates and their sustainability, especially compared to prior periods.
Gross margin and operating margin trends, if disclosed, to assess the degree of operating leverage.
Net cash flow from operations and changes in cash/cash equivalents on the balance sheet.
Frequency and size of new equity offerings, warrant exercises, or other capital-raising activities.
Disclosure of customer concentration, contract wins, or test menu expansion, which would clarify revenue visibility and diversification.
Management turnover or changes in incentive structures, which may signal shifts in strategic direction.
Any updates on industry classification, peer benchmarking, or regulatory developments that clarify Precipio’s competitive positioning.
Investor communications cadence and transparency, as ongoing disclosure is critical for market confidence.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments