
Saratoga Investment Corp.: Leveraged Middle-Market Lending at a Crossroads of Yield, Liquidity, and Managerial Stability
Saratoga Investment Corp. operates a high-yield, highly-leveraged portfolio focused on U.S. middle-market loans and opportunistic assets.
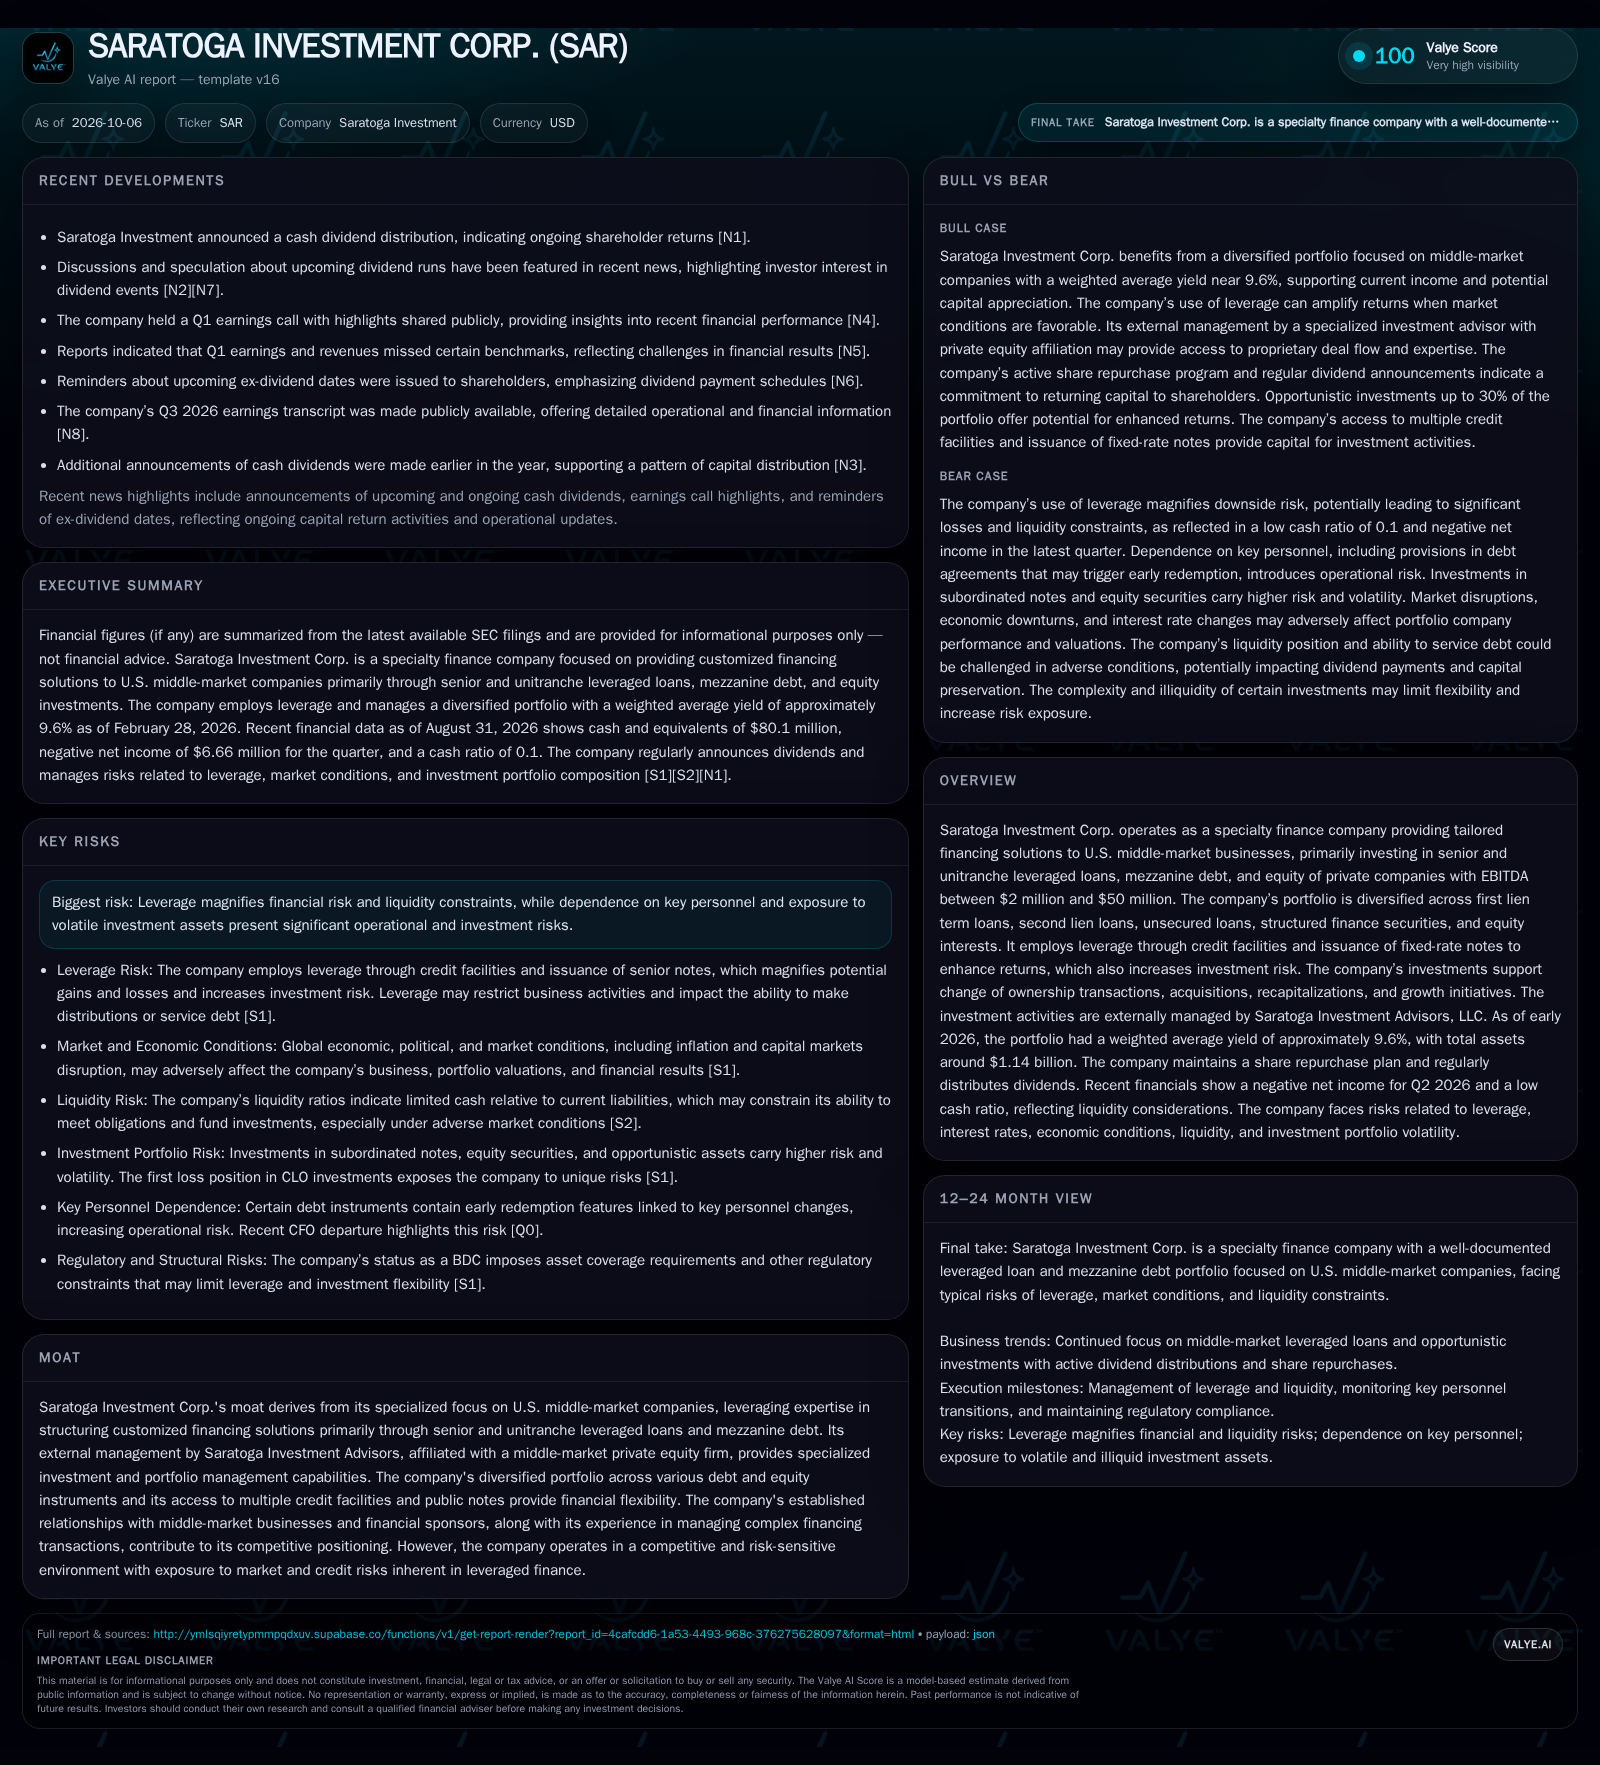
Saratoga Investment Corp. is a specialty finance company targeting U.S. middle-market lending with an externally managed, leveraged portfolio. The thesis now hinges on the company’s ability to manage leverage, preserve dividend capacity, and navigate key personnel transitions in a volatile credit environment. [S1] [S2]
Saratoga Investment Corp. sits at the intersection of high-yield middle-market lending and elevated financial risk. While its portfolio generates attractive yields and supports ongoing shareholder returns, the company’s reliance on leverage, recent negative earnings, and thin liquidity underscore its vulnerability to adverse credit cycles and execution missteps. With a key CFO departure triggering potential early debt redemption and amplifying operational risk, Saratoga’s near-term performance will hinge on its ability to prudently manage leverage, maintain credit discipline, and protect its dividend and buyback programs amid tightening financial conditions. [S1] [S2] [N1]
Recent Liquidity Strain, Negative Earnings, and Executive Turnover Shape Outlook
The company reported a cash ratio of 0.1 for the period. This liquidity constraint is compounded by a negative net income of $6.66 million for the quarter and negative $0.41 per share in basic and diluted EPS, signaling recent financial underperformance. The company’s weighted average yield on investments remains high at 9.6% before fees and expenses, but this has not translated into positive bottom-line results in the current period. Additionally, the announced departure of the CFO (effective October 31, 2026) activates early redemption risk on certain notes, heightening operational and financial uncertainty. [S1] [S2]
How Saratoga Generates (and Risks) Returns: Leveraged Yield and Capital Structure Dynamics
Saratoga’s business model centers on providing senior and unitranche loans, mezzanine debt, and select equity investments to U.S. middle-market companies, typically financing ownership changes, growth, or recapitalizations. The economics are driven by the spread between high-yield loan returns (9.6% portfolio yield as of February 2026) and the company’s cost of capital, with operating leverage amplified by the use of debt financing. Most of the portfolio (82.1%) is first lien term loans, which generally offer lower risk and higher recovery prospects, but the company also allocates up to 30% to higher-yielding, riskier assets like structured finance, distressed debt, and CLO equity tranches.
Leverage is a double-edged sword: it can enhance returns in benign markets but magnifies losses and liquidity risk when portfolio companies falter or capital markets tighten. Saratoga’s capital structure includes borrowings under credit facilities and multiple fixed-rate note issuances, including a recent $100 million 7.50% note due 2031. The externally managed structure adds a layer of fees, which can further pressure net returns in periods of underperformance. [S1] [S2]
Niche Focus in a Crowded Field: Middle-Market Lending Amidst Competition and Substitution
Saratoga’s competitive edge is rooted in its specialization in structuring customized financing for U.S. middle-market businesses, leveraging relationships with management teams, sponsors, and its private equity-affiliated advisor. This focus can provide access to proprietary deals and nuanced risk assessment that generic lenders may lack. However, the company operates in a highly competitive environment alongside other business development companies (BDCs), private credit funds, banks, and institutional investors all seeking attractive yields.
Competition is intense on pricing and terms—especially as capital chases limited high-quality deals—and the rise of direct lending platforms and alternative credit vehicles continues to compress spreads and increase borrower leverage. Substitution risk from banks in lower-rate environments or from larger credit funds with deeper pockets can erode Saratoga’s origination advantage. Furthermore, the company’s reliance on external management means fee structures must be justified by consistent outperformance, which is at risk if negative earnings persist or portfolio quality deteriorates. [S1]
If Credit Markets Stabilize and Underwriting Holds, Leverage Could Boost Returns and Dividend Capacity
In a favorable scenario, Saratoga’s portfolio companies continue to perform, supported by a resilient U.S. economy and stable credit markets. Loan defaults remain low, and the company is able to redeploy repayments into new high-yield opportunities without compromising underwriting discipline. The high portfolio yield (9.6%) converts into positive net income as credit losses normalize and fee drag is contained.
Opportunistic investments—up to 30% of the portfolio—could provide additional upside if market dislocations create attractive distressed or structured finance opportunities. Confirmation of this scenario would include a return to positive net income, stable or rising NAV per share, and consistent dividend coverage by net investment income. A successful CFO transition and no activation of early debt redemption would also support sentiment. [S1] [S2]
Navigating Tight Liquidity: Dividend Continuity Amid Margin Compression and Leadership Transition
The most plausible outcome is that Saratoga maintains its current dividend and buyback cadence but faces increasing pressure on margins and liquidity. The company manages to roll over or refinance maturing debt, but does so at higher costs, compressing net spreads. Portfolio performance is mixed: while most loans pay as agreed, a handful of credits require restructuring or additional monitoring, leading to modest realized losses or non-accruals.
The external manager seeks to optimize portfolio mix and carefully pace new investments, but fee drag and higher borrowing costs limit net income growth. The CFO transition proceeds without major disruption, but early redemption clauses in debt covenants remain a watchpoint. [S1] [S2]
Leverage Unwinds: Credit Deterioration, Forced Asset Sales, and Dividend Cuts in a Stressed Market
In an adverse scenario, a broader economic downturn or sector-specific stress increases defaults and impairments across Saratoga’s portfolio, particularly in subordinated, structured finance, or CLO first loss positions. Loan repayments slow, and new deal flow dries up or shifts to lower-yield, lower-risk assets, reducing overall portfolio yield. Rising credit losses and fee drag drive persistent negative net income, triggering pressure to cut or suspend dividends.
Liquidity constraints worsen as the company struggles to refinance maturing debt or is forced to sell assets at a discount to meet obligations. The reported cash ratio becomes acute, and debt covenants—potentially activated by the CFO departure or other key person events—lead to early redemption of notes, further straining cash. Share buybacks are halted, and the company’s NAV per share declines materially. Confirmation would include a dividend cut or suspension, asset sales below book value, rising non-accrual rates, and covenant breaches or distressed refinancing activity. [S1] [S2]
Testing the Saratoga Thesis: Metrics for Leverage, Liquidity, and Execution
Net investment income versus dividend payouts: A useful metric would be the ratio of recurring net investment income to dividend obligations, testing whether distributions remain covered on a cash basis.
Non-accrual rates and realized credit losses: If disclosed, rising non-accruals or credit losses would indicate portfolio stress and threaten future earnings and capital return.
Debt covenant headroom and refinancing activity: Updates on covenant compliance and the company’s ability to refinance or roll over maturing notes will be critical, especially following the CFO departure.
NAV per share trajectory: Persistent declines in NAV per share could signal underlying asset impairments or dilution from distressed asset sales.
Execution of opportunistic investments: Clarity on returns and risk management in the 30% opportunistic allocation would shed light on Saratoga’s ability to generate alpha and manage volatility.
Resolution of CFO transition and key personnel risk: Smooth leadership transitions and no activation of early note redemption clauses would reduce operational and refinancing risk.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments