
Skyline Bankshares: Growth Opportunities, Real Estate Focus, and Scaling Complexities
Skyline Bankshares, Inc. has expanded its regional footprint through acquisition while maintaining a conservative, real estate-heavy loan book. Its future will hinge on credit discipline, integration execution, and its ability to compete with larger institutions and fintechs for both deposits and loans in a shifting regulatory and economic landscape.
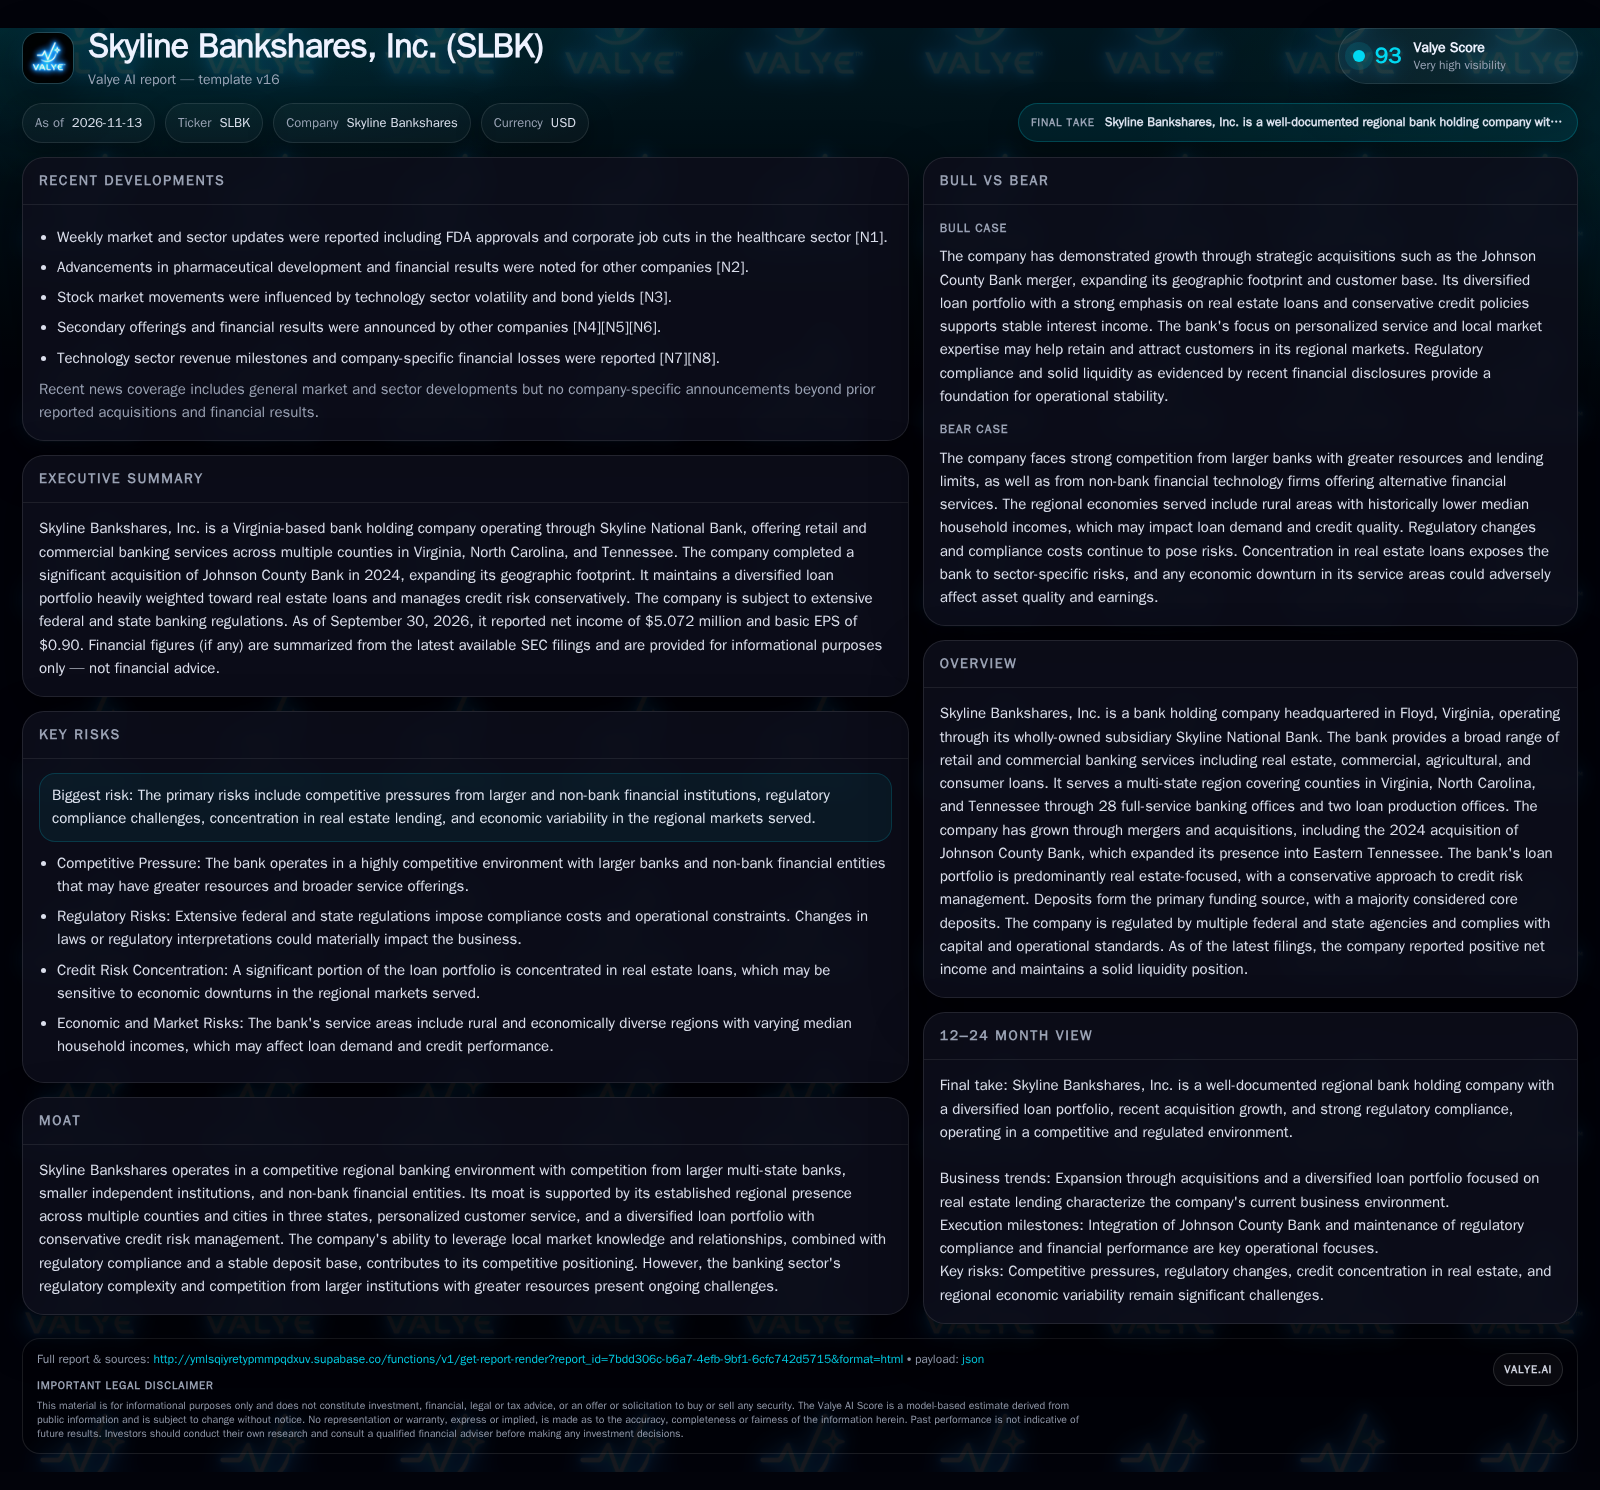
Skyline Bankshares is a Virginia-based bank holding company with a recent acquisition in Tennessee, a loan book concentrated in real estate, and a high proportion of core deposits. The bank’s ability to integrate acquisitions and defend its market share against larger and digital-first competitors will define its medium-term trajectory. [S1] [S2]
Skyline Bankshares, Inc. is a regional bank holding company that has steadily grown its footprint across Virginia, North Carolina, and Tennessee through targeted acquisitions and community-focused banking. Its recent purchase of Johnson County Bank marks a strategic move into Eastern Tennessee, adding scale and customer reach. However, the bank’s strong tilt toward real estate lending and its exposure to economically diverse, often rural areas, mean that credit quality and demand could fluctuate with local market conditions. As the competitive and regulatory landscape for regional banks intensifies, Skyline’s ability to manage risk, integrate acquisitions, and carve out defensible advantages will be tested.
Recent Acquisition and Earnings Shape Current Business Conditions
Skyline Bankshares completed the acquisition of Johnson County Bank in September 2024, adding $154.1 million in assets and assuming $133.8 million in liabilities, including $125.3 million in deposits. This move expanded its branch network and customer base into Eastern Tennessee, broadening the bank’s geographic presence beyond its core markets in Virginia and North Carolina. [S1]
As of September 30, 2026, Skyline reported net income of $5.072 million and basic earnings per share of $0.90, with cash and cash equivalents standing at $49.08 million. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S2]
Revenue Streams: Real Estate Loans, Core Deposits, and Margin Trends
Skyline’s economics are driven by traditional spread banking. The bank’s loan book is highly concentrated in real estate lending, with 56.35% in single and multi-family housing and 28.61% in non-farm, non-residential real estate as of December 31, 2025. [S1] This focus supports stable interest income in benign credit environments, but it exposes the bank to sectoral downturns and local economic shifts. Agricultural, construction, commercial, and consumer loans provide some diversification, but collectively represent a minority of the portfolio.
Funding is primarily sourced from core deposits (89.85%), providing a relatively stable and low-cost base to support lending. [S1] Certificates of deposit above FDIC limits account for 10.15%, potentially more rate-sensitive and less sticky in a rising rate environment. Net interest margin will be sensitive to competitive deposit pricing and the yield curve. Operating leverage is modest given the fixed costs associated with a 28-branch footprint, and efficiency gains from the Johnson County Bank integration could improve profitability if realized.
Capital adequacy, regulatory compliance, and liquidity are persistent constraints, especially given the heavy real estate exposure. While cash and cash equivalents totaled $49.08 million as of September 30, 2026, ongoing funding needs will depend on loan growth, deposit retention, and potential credit losses. [S2]
Maintaining Market Position Amid Regional Banking Competition
Skyline operates in a highly competitive environment. Its primary competitors include larger regional and national banks with greater lending capacity, more diversified funding sources, and broader technology offerings. Smaller community banks, credit unions, and increasingly, non-bank fintechs also contest for both deposits and loans, often with digital-first products or niche service models.
Skyline’s competitive advantages are rooted in local market knowledge, personalized service, and established relationships—factors that can foster retention in rural and semi-urban markets. The recent acquisition of Johnson County Bank provides a larger footprint and the potential for cross-selling, but also increases integration complexity and the risk of customer attrition if execution falters.
Switching frictions in banking can be high for core customers, particularly in communities with limited alternatives, but digital adoption is gradually lowering these barriers. The question is whether Skyline can sufficiently invest in technology and product breadth to defend and grow its share as customer expectations evolve.
Opportunities for Growth Through Integration and Market Strength
The most favorable outcome for Skyline would see the Johnson County Bank acquisition delivering cost and revenue synergies, with minimal customer attrition and effective cross-selling of loans and deposit products. If local economies in the bank’s expanded footprint remain stable or grow—particularly the real estate markets that underpin the majority of the loan book—interest income could rise without a corresponding increase in credit losses.
Additional upside could come from operational efficiencies, such as branch consolidation or technology enhancements that reduce overhead. A relatively high proportion of core deposits could insulate funding costs if interest rates rise, supporting net interest margin expansion.
Evidence supporting this scenario would include above-peer loan growth, stable or improving credit metrics (such as non-performing asset ratios, if disclosed), and expanding profitability metrics (ROA, ROE) in the wake of the acquisition.
Performance Outlook in a Challenging Growth Environment
The most plausible medium-term scenario is one of modest growth and stable, but unexceptional, profitability. The loan book remains heavily weighted toward real estate, and while core deposits provide funding stability, competitive pressure—especially for deposits—gradually erodes net interest margins. Integration of Johnson County Bank proceeds without major disruption but does not yield transformative synergies.
Credit quality remains broadly sound, but is periodically tested by economic fluctuations in rural and small-town markets. Regulatory costs and technology investments offset some operating leverage gains from consolidation. The bank maintains compliance with capital and liquidity standards, but does not generate outsized returns relative to larger competitors.
Confirming evidence would be steady EPS growth, stable efficiency ratios, and balance sheet growth roughly in line with regional peers. Falsifying evidence would include a spike in non-performing loans, significant deposit runoff, or persistent margin compression.
Risks from Credit Concentration and Regional Economic Pressures
The primary risk to Skyline’s model is a deterioration in regional real estate markets or broader economic stress in its rural and small-town footprint. Given that nearly 85% of loans are real estate-related, a downturn could drive up non-performing assets and provisioning costs, eroding profitability and potentially pressuring regulatory capital ratios.
Competition from larger banks and digital-first entrants could accelerate deposit outflows or force higher deposit costs, compressing net interest margins. Integration missteps with Johnson County Bank—such as systems failures or customer attrition—could further weaken performance.
Downside evidence would include a sharp rise in charge-offs, declining deposit balances, regulatory consent orders, or a material drop in quarterly profitability.
Upcoming Developments That Could Influence Skyline’s Market and Credit Health
Loan growth by type and geography, especially post-acquisition, would help assess whether the bank is gaining share or simply redeploying balances.
Non-performing asset ratios and net charge-offs, if disclosed, are essential to gauge real estate credit risk and the resilience of the loan book.
Deposit growth and retention rates, particularly for core deposits versus higher-cost certificates, will reveal competitive dynamics and funding stability.
Efficiency ratio trends and operating expense metrics will show whether integration and scale are translating into better profitability.
Branch consolidation or technology investment announcements could indicate management’s approach to cost control and service enhancement.
Capital adequacy metrics (such as Tier 1 capital ratio, if disclosed) would signal the bank’s ability to absorb future shocks.
Market share changes in key counties or cities, if available, would clarify competitive positioning in the expanded footprint.
Regulatory filings or commentary on compliance costs and examinations could help assess the evolving risk environment.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments