
TransUnion’s Data Ecosystem: AI Integration, Global Diversification, and the Evolving Economics of Trust
TransUnion’s latest results show accelerating revenue growth and ongoing AI-driven product innovation, but the company’s future will hinge on its ability to leverage proprietary data and analytics across diverse verticals while navigating regulatory, technological, and competitive headwinds.
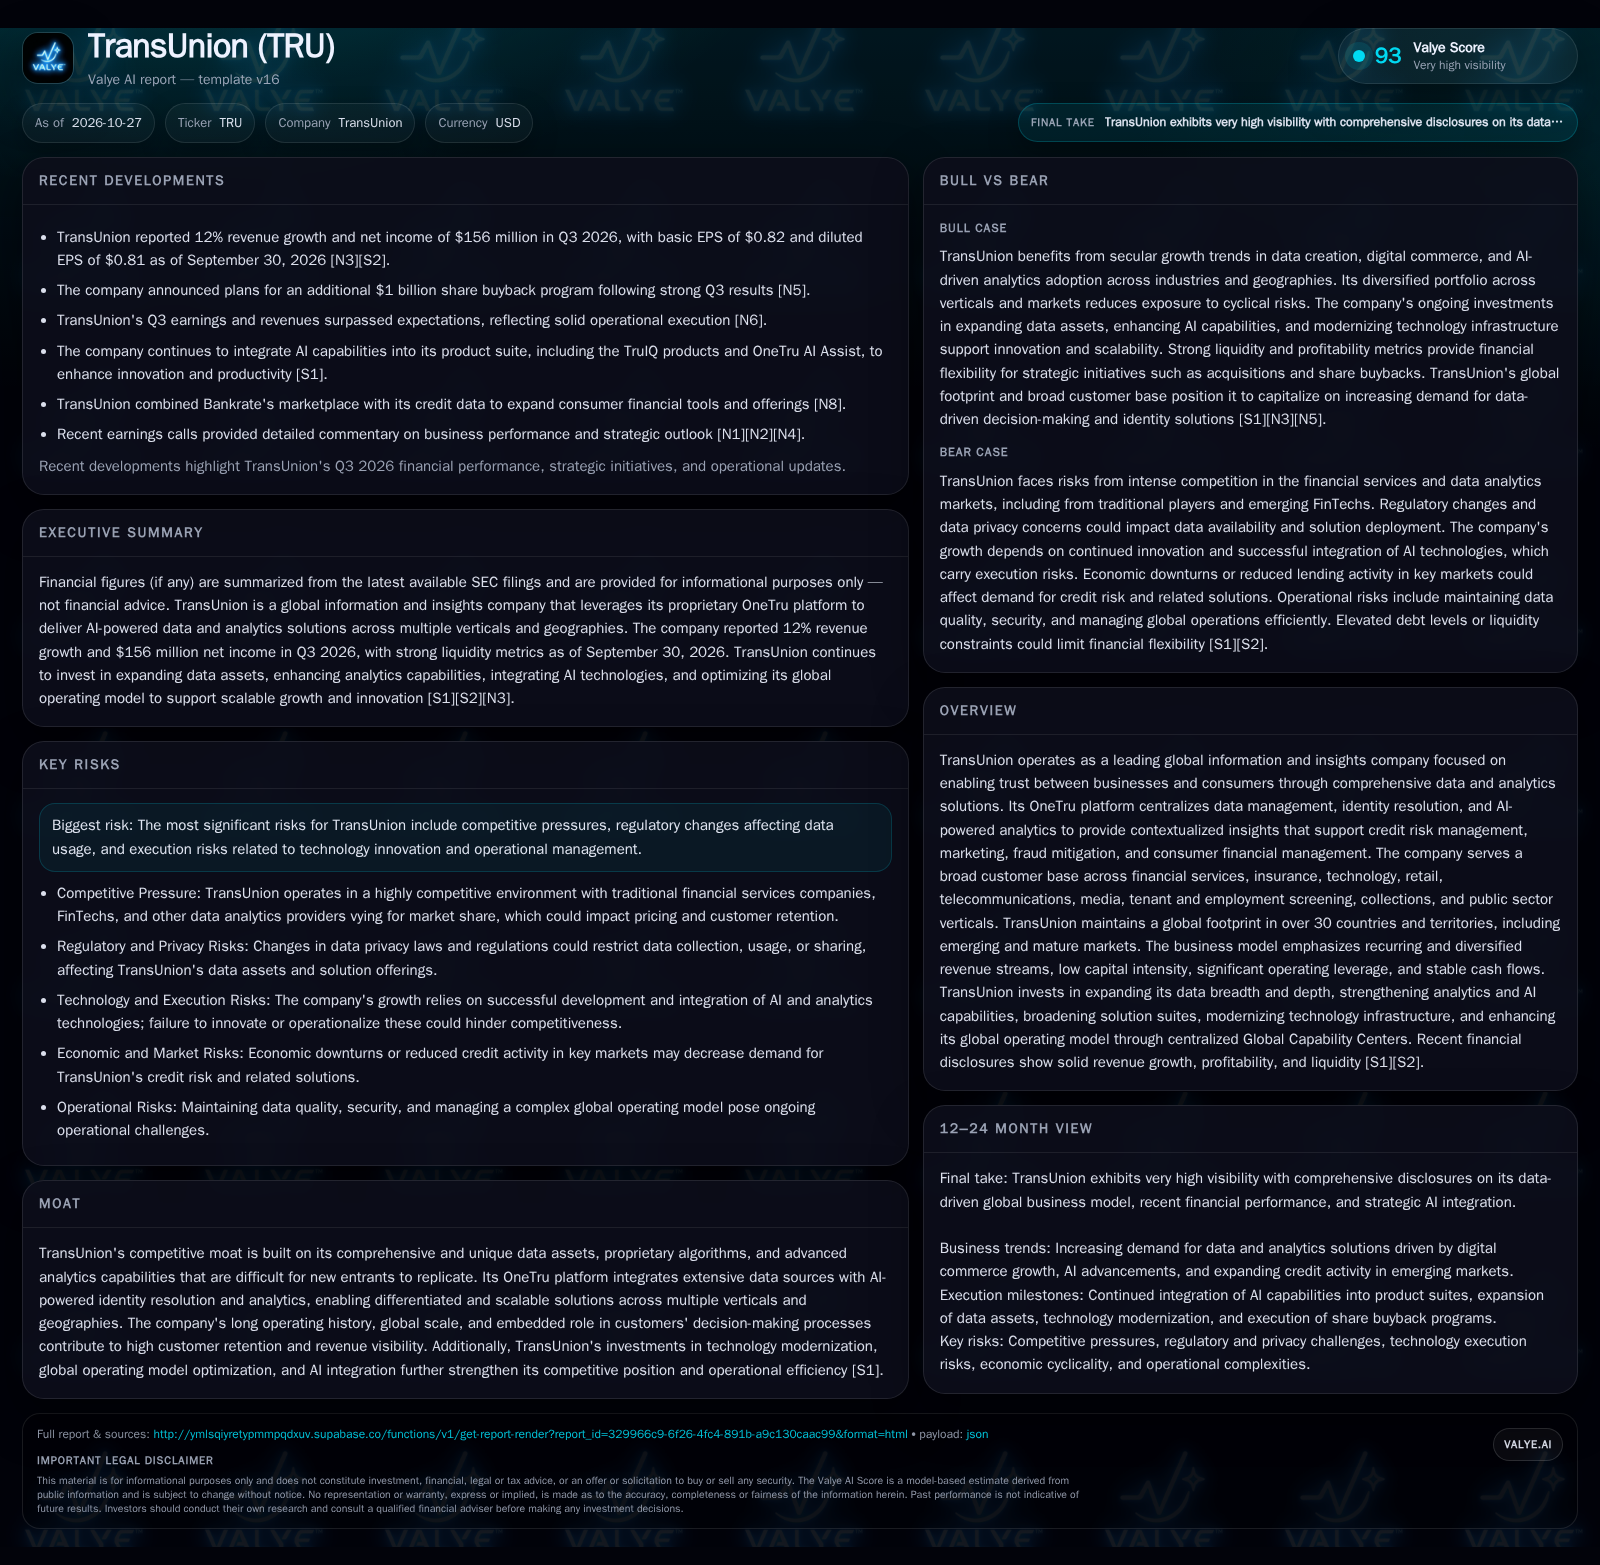
TransUnion reported 12% revenue growth and $156 million net income in Q3 2026, with continued integration of AI into its platforms and expansion of consumer offerings through partnerships like Bankrate. The company’s model is built on recurring, diversified revenues, low capital intensity, and operating leverage, but faces persistent regulatory and competitive risks as it seeks to scale its data ecosystem and analytics solutions globally. Sustained outperformance will depend on execution in AI, data breadth, and cross-vertical expansion while defending its moat against both traditional and emerging rivals. [S1] [S2] [N3] [N8]
TransUnion’s latest quarter marks a period of accelerating growth and innovation, with the company reporting 12% revenue growth and $156 million in net income. The integration of AI into its core platforms, expansion into consumer financial tools, and global reach across more than 30 countries underscore a business model designed for scale, resilience, and recurring revenues. Yet, as TransUnion deepens its reliance on data breadth and advanced analytics, it must contend with intensifying regulatory scrutiny and a crowded competitive landscape. The next phase of value creation will depend on whether TransUnion can sustain its data-driven moat and operational agility in an environment defined as much by trust and compliance as by technological advancement. [S1] [S2] [N3] [N8]
Recent Performance: Growth, AI Integration, and Product Expansion
TransUnion reported 12% year-over-year revenue growth and net income of $156 million in Q3 2026, with basic EPS of $0.82 and diluted EPS of $0.81 as of September 30, 2026 [N3] [S2]. This growth exceeded market expectations and was accompanied by ongoing integration of AI capabilities into the company’s product suite, including the TruIQ suite and OneTru AI Assist [S1]. Another notable development is the expansion of consumer offerings through the combination of Bankrate's marketplace with TransUnion’s credit data, which aims to deliver richer financial tools and insights to consumers [N8]. As of September 30, 2026, TransUnion reported $883.1 million in cash and equivalents, a current asset base of $2.2 billion, and a current ratio of 2.03 [S2]. While these liquidity metrics are descriptive, the operational focus remains on leveraging data and analytics to drive cross-vertical growth and innovation.
How TransUnion Monetizes Data: Recurring Revenue, Scale, and Operating Leverage
TransUnion’s core business economics are shaped by the aggregation, refinement, and monetization of vast, multi-source data assets. The company’s OneTru platform acts as a centralized hub for data management, identity resolution, and AI-powered analytics, enabling the delivery of contextualized insights to customers in financial services, insurance, technology, retail, telecom, and the public sector [S1]. Revenue is primarily generated through recurring contracts for data access, analytics-driven solutions, and decision support tools. These contracts may take the form of subscriptions, usage-based fees, or integrated platform arrangements, but the recurring nature and broad vertical mix dampen exposure to single-sector cyclicality.
The financial model is characterized by low capital intensity: data acquisition, algorithm development, and cloud-based infrastructure require upfront investment, but incremental delivery to additional customers is highly scalable. This creates significant operating leverage—fixed costs are spread across a growing base, and incremental gross margins on new business can be substantial, especially as AI and automation reduce marginal service costs. TransUnion’s Global Capability Centers further centralize and automate operational tasks, driving down per-unit costs as the company grows [S1].
The company’s cash flows are described as stable, reflecting the stickiness of embedded data and analytics in customer workflows, although true revenue retention and contract renewal metrics would provide a clearer picture if disclosed. A central question is whether ongoing investments in AI, data expansion, and digital infrastructure will yield enough differentiation to support pricing power and margin expansion as competitive intensity rises.
Defending the Data Moat: Differentiation, Substitution, and New Entrants
TransUnion’s competitive position rests on a combination of differentiated data assets, proprietary algorithms, and integration into customer decision processes [S1]. Its OneTru platform aggregates credit, alternative financial, identity, and behavioral data from thousands of sources, which are then enhanced through AI-driven analytics and entity resolution. This breadth—across both data types and geographies—creates barriers for new entrants, who would need to replicate not just the data but also the relationships and compliance infrastructure required for regulated markets.
However, the company operates in a fast-evolving landscape. Traditional credit bureaus, specialized analytics providers, FinTechs, and big technology firms are all vying to capture value from data-driven decisioning. Substitution risk is rising as alternative data sources, open banking, and direct-to-consumer credit models proliferate. AI lowers the cost of developing predictive models, potentially eroding advantages based purely on analytics expertise.
TransUnion’s response—investing in AI, expanding data breadth, and forming partnerships (such as with Bankrate)—is designed to reinforce its moat by making its solutions more comprehensive and harder to displace. The effectiveness of this strategy will depend on maintaining unique data access, sustaining regulatory compliance, and keeping pace with technology innovation. Customer switching costs are meaningful where TransUnion’s insights are deeply embedded in workflows, but price competition and new data paradigms could pressure both retention and margins over time.
AI-Driven Expansion and Cross-Vertical Penetration Accelerate Value Creation
The most favorable scenario for TransUnion is one where its ongoing investments in AI, data breadth, and product innovation translate into sustained above-market growth and margin expansion. In this scenario, the OneTru platform becomes increasingly indispensable for risk management, identity resolution, and consumer engagement across a widening set of verticals—from traditional lending and insurance to emerging areas such as digital identity, e-commerce, and public sector analytics.
Key to this outcome would be successful scaling of AI-powered products like TruIQ and OneTru AI Assist, resulting in higher per-customer revenue and improved retention as customers rely more heavily on TransUnion’s contextualized insights. The integration of consumer-facing offerings (as with Bankrate) could unlock new monetization channels and deepen consumer engagement, potentially creating network effects if adoption broadens.
Evidence that would confirm this trajectory includes accelerating multi-vertical revenue growth, expanding gross and operating margins, increased customer win rates in competitive RFPs, and rising average revenue per user (if disclosed). Falsification would come from a slowdown in new product adoption, stagnant margins despite technology investment, or visible share loss to alternative data and analytics providers.
Sustained but Competitive Growth Amid Regulatory and Technology Shifts
The most plausible scenario is that TransUnion continues to post steady revenue growth slightly above GDP and sector averages, driven by ongoing digitization, expanding data usage, and the gradual rollout of enhanced analytics solutions across established and adjacent verticals. Operating leverage remains a tailwind, but margin gains are moderated by persistent investment needs and competitive pricing pressure.
Regulatory complexity—particularly around data privacy, cross-border data flows, and AI explainability—remains a structural headwind, requiring ongoing compliance investment and occasionally slowing product deployment in certain markets. Customer relationships remain sticky in core financial services and regulated sectors, but pricing power is tested as new entrants and alternative data sources challenge the status quo.
This scenario would be confirmed by consistent mid-to-high single-digit revenue growth, stable to modestly expanding margins, continued product launches, and incremental cross-vertical wins. Falsification would be signaled by sudden regulatory setbacks, material customer churn, or margin compression outpacing revenue gains.
Regulatory Clampdown, Data Disintermediation, and Margin Compression
A negative scenario for TransUnion involves a confluence of regulatory tightening, data ecosystem disruption, and competitive pricing pressure. If major jurisdictions impose stricter controls on data collection, usage, or cross-border transfers, TransUnion’s ability to access and monetize proprietary data could be significantly impaired. Simultaneously, if alternative data sources (such as open banking, decentralized identity, or direct consumer consent models) gain traction, traditional credit and identity bureaus may face disintermediation.
In this scenario, the company could experience slowing or declining revenues in key segments, rising compliance and technology costs, and margin erosion as customers push for lower prices or shift to new providers. Execution risk in AI and analytics integration adds further downside if investments fail to generate expected efficiencies or product differentiation.
Confirmation of this scenario would come from regulatory actions limiting data access, revenue declines in core geographies, elevated customer churn, and shrinking operating margins despite stable or rising technology spend. Falsification would require evidence of regulatory stability, robust customer retention, and successful product innovation that protects margins.
Benchmarks for Validating TransUnion’s Competitive Durability and Growth Ambitions
Sustained multi-vertical revenue growth rates, especially in newer sectors such as digital identity, insurance, and public sector analytics, would help test the breadth of TransUnion’s expansion.
Gross and operating margin trends, particularly relative to technology and compliance investments, will clarify whether operating leverage and AI integration are translating into improved profitability.
Customer retention rates and average revenue per customer, if disclosed, would provide evidence of solution stickiness and pricing power.
Adoption rates and revenue contribution from new AI-driven products (e.g., TruIQ, OneTru AI Assist) will indicate the success of innovation initiatives.
The impact of regulatory changes on data access, cross-border data flows, and product deployment in key markets should be monitored closely.
The scale, integration, and revenue contribution of consumer-facing partnerships (such as with Bankrate) will shed light on the viability of new monetization channels.
Operational efficiency gains from Global Capability Centers, measured by cost per transaction or per customer (if disclosed), would help assess scalability.
Competitive win rates in RFPs and new customer logos, especially in verticals where alternative data providers are gaining ground, would signal ongoing market relevance.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments